


Press release
DRI Sponge Iron Manufacturing Plant Project Report, Feasibility Study 2026: CapEx/OpEx , ROI Analysis and Business Plan
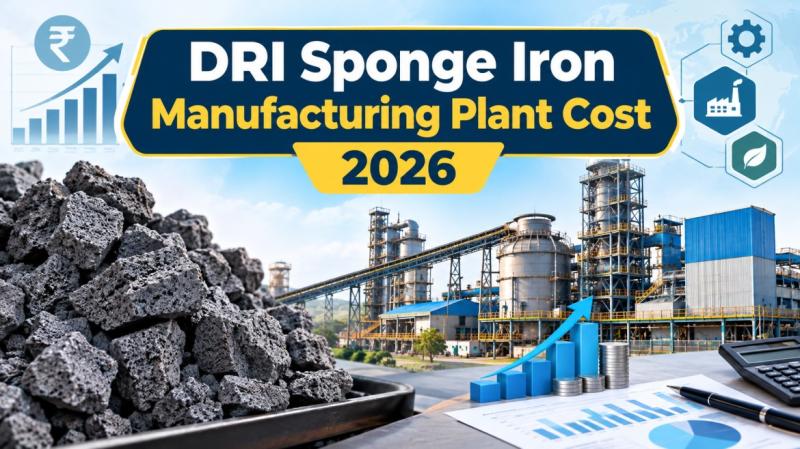
This business plan report covers what capacity to target, which raw materials to secure, what machinery and site conditions are required, how capital and operating costs break down, and what profitability and regulatory factors determine commercial viability for a DRI sponge iron manufacturing plant. It draws on IMARC Group's DRI Sponge Iron Manufacturing Plant Project Report 2026, which benchmarks a facility with an annual production capacity of 100,000-500,000 MT. Asia Pacific holds the largest share of the global market, at over 56.0%.
Minimum Cost Required to Set Up a DRI Sponge Iron Plant:
Industry cost benchmarking indicates that setting up a DRI sponge iron manufacturing plant may require an initial investment of approximately USD 15-25 million for a smaller-scale facility producing around 100,000 MT annually, covering essential equipment such as rotary kilns, raw material handling systems, rotary coolers, magnetic separators, screening units, conveyors, and pollution control systems. Capital requirements can increase to approximately USD 30-60 million for mid-sized plants producing around 200,000-300,000 MT per year, while large-scale facilities may require USD 80-150 million or more for capacities approaching 500,000 MT annually, particularly where waste heat recovery boilers, advanced emission control systems, and captive power generation infrastructure are incorporated. The key manufacturing stages include iron ore preparation and sizing, solid-state reduction using non-coking coal or natural gas, cooling, magnetic separation, screening, and product storage and dispatch.
1. Why DRI Sponge Iron Manufacturing Matters in 2026:
DRI sponge iron manufacturing sits at the intersection of the steel value chain and the push for cleaner steelmaking. The market is fueled by rising demand for steel across construction, automobiles, and infrastructure, and as urbanization and industrialization increase in emerging markets, including Asia and Africa, demand for high-quality, low-carbon steel feedstock such as DRI sponge iron is expected to grow. According to the United Nations ESCAP, the population in urban areas is expected to rise by 50% by 2050 - a trend that directly stimulates iron-making and steel capacity across the supply chain.
The accelerating focus on sustainable and cleaner steel production further drives the market, since DRI technology provides a cleaner alternative to traditional steel production methods. The rising cost of scrap metal and the demand for higher-quality steel also support demand, as DRI sponge iron offers an effective way to reduce dependency on scrap while maintaining steel quality.
Request Sample: https://www.imarcgroup.com/dri-sponge-iron-manufacturing-plant-project-report/requestsample
Why Invest in DRI Sponge Iron Manufacturing?
Four factors make DRI sponge iron manufacturing a comparatively attractive steel-chain investment:
● Eco-friendly alternative: Producing DRI sponge iron is cleaner than the blast furnace-based conventional process of producing iron, making it an eco-friendlier option for the iron and steel industry.
● High demand in steel production: With the increasing global need for steel, especially in developing countries, there is high demand for high-grade feedstock materials, and DRI sponge iron is no exception.
● Efficient and cost-effective: The process is cost-effective, especially in countries with access to natural gas, and offers the steel industry a flexible alternative to scrap-based electric arc furnace routes.
● Lower carbon emissions: The DRI process emits much lower carbon than conventional ironmaking, an advantage as steelmakers face tightening decarbonization expectations.
2. What is DRI Sponge Iron and Where is It Used:
Direct Reduced Iron (DRI), also known as sponge iron, is a form of iron produced by reducing iron ore (primarily iron oxide) using a reducing gas, usually hydrogen or carbon monoxide. Unlike traditional blast furnace methods, DRI is produced at lower temperatures and in a more environmentally friendly manner.
The process produces iron with a high degree of purity and minimal carbon content, which suits steelmaking, and the resulting sponge iron is highly porous and is used as a feedstock in electric arc furnaces or as an alternative to scrap iron. Commercial production generally involves raw material sourcing, the reduction process, a production furnace, cooling and pelletizing, and packaging:
● Steel manufacturing: The majority of DRI is used in steelmaking, particularly in electric arc furnaces, where it is a high-quality feedstock that reduces reliance on scrap.
● Foundries: Used for casting metal components that require specific mechanical properties.
● Automotive: Used in making steel-based components such as engine blocks and wheels, benefiting from DRI's purity and low carbon content.
● Construction and infrastructure: Used in producing long steel products such as bars, rods, and beams for roads, bridges, and commercial buildings.
3. DRI Sponge Iron Manufacturing Process:
DRI sponge iron manufacturing follows a defined sequence of unit operations:
● Raw material sourcing and preparation - iron ore, coal or natural gas, and dolomite are sourced, sized, and charged to the process.
● Reduction process - iron oxide is reduced to metallic iron using a reducing gas (or coal-derived reductant) at temperatures below the melting point of iron.
● Production furnace/kiln - the reduction takes place in a rotary kiln or shaft-type furnace, supported by gas reforming where a natural gas route is used.
● Cooling and pelletizing - the hot product is cooled to prevent re-oxidation and handled in the required product form.
● Packaging and dispatch - the finished sponge iron is screened, stored, and dispatched to steel plants and foundries.
A comprehensive quality management system should be implemented across all stages of operations, with appropriate testing, monitoring, and validation processes, standard operating procedures, documentation and traceability mechanisms, and regular audits and corrective action frameworks to support consistent product standards such as metallization and carbon content.
Regional Insights:
The cost of establishing a Direct Reduced Iron (DRI) sponge iron manufacturing plant varies across regions depending on the availability and prices of iron ore, non-coking coal or natural gas, dolomite, electricity, water, industrial land, and skilled labour. Investment requirements are also influenced by production capacity, reduction technology, energy efficiency, environmental controls, and transportation infrastructure. Sponge iron is an important feedstock for steelmaking, particularly in electric arc furnaces and induction furnaces. According to IMARC Group, Asia Pacific accounts for more than 56% of the global DRI sponge iron market, supported by its extensive steel production base and growing infrastructure demand.
Asia Pacific (China, India, Japan, South Korea, Australia, Indonesia, Thailand, Malaysia, Vietnam, Philippines, Singapore): The region benefits from established steelmaking industries, infrastructure investment, and access to iron ore and coal supply chains. India is a particularly important market for coal-based DRI production. Plant setup costs depend on proximity to iron ore mines, coal suppliers, ports, and steel manufacturers, as well as access to reliable utilities, rotary kilns, material-handling systems, and pollution-control equipment.
North America (U.S., Canada, Mexico): Demand from steel producers, infrastructure projects, and electric arc furnace operations creates opportunities for DRI production. Investment considerations include iron ore pellet availability, natural gas or hydrogen supply, electricity prices, labour expenses, environmental requirements, and the cost of specialised reduction technology. Locations near steelmaking facilities and reliable energy infrastructure can improve operating efficiency.
Europe (Germany, U.K., France, Italy, Spain, Netherlands, Belgium, Poland, Sweden, Norway, Denmark, Switzerland): The region's steel decarbonisation initiatives and demand for lower-emission metallic feedstocks support investment in DRI technology. Plant economics are influenced by electricity and gas prices, access to high-grade iron ore pellets, labour costs, environmental regulations, and investment in energy-efficient reduction systems. Hydrogen-based production may require additional investment in hydrogen supply and associated infrastructure.
Latin America (Brazil, Argentina, Mexico, Colombia, Chile, Peru, Paraguay, Uruguay, Ecuador): The region offers opportunities through its iron ore resources, steel industry, and infrastructure development. Plant establishment costs depend on raw material quality, access to coal or natural gas, electricity availability, transport links, and proximity to steelmaking customers. Integrated supply chains and access to ports can help manage procurement and distribution expenses.
Middle East & Africa (Saudi Arabia, UAE, Qatar, Kuwait, Oman, Israel, Egypt, South Africa, Nigeria, Morocco, Algeria, Kenya, Ethiopia, Tanzania, Ghana): Industrial development, steel capacity expansion, and investment in alternative ironmaking technologies create opportunities for DRI production. Costs depend on iron ore pellet sourcing, natural gas availability, power infrastructure, water supply, equipment procurement, and environmental compliance. Locations with reliable energy supplies and access to steel manufacturers or export markets may offer advantages.
4. Raw Materials and Sourcing:
Reliable raw material supply is the single most important operating input for a DRI sponge iron plant, given that raw materials account for the large majority of operating expenses, with iron ore the largest single item. Core raw material inputs include:
● Iron ore
● Coal or natural gas
● Dolomite
Sourcing strategy should prioritize reliable suppliers of these materials to ensure consistent production quality, alongside minimizing transportation costs by selecting nearby suppliers, which matters particularly for bulky, low-value-density inputs like iron ore and coal. Sustainability and supply chain risks should be assessed as part of supplier selection, and long-term contracts should be negotiated to stabilize pricing and secure a steady supply, since iron ore and energy price volatility flows directly into margin.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=30549&flag=C
5. Site Selection and Plant Layout:
Site selection for a DRI sponge iron manufacturing business should prioritize:
● Proximity to raw materials - easy access to iron ore, coal or natural gas, and dolomite supplies, ideally with rail or port connectivity.
● Proximity to target markets - minimizing distribution costs, with nearby steel plants and foundries the natural customers.
● Infrastructure robustness - reliable transportation, utilities, and waste management systems.
● Regulatory fit - compliance with local zoning laws and environmental regulations, with particular attention to air emissions and dust.
● Plant layout should be optimized to enhance workflow efficiency, safety, and minimize material handling, with separate areas designated for raw material storage, production, quality control, and finished goods storage.
● Sponsors should also incorporate space for future expansion, since iron and steel plants tend to scale capacity over their operating life rather than remain static.
6. Machinery and Equipment Requirements:
Key equipment categories for a DRI sponge iron manufacturing plant include:
● Rotary kilns
● Gas reformers
● Cooling systems
● Pelletizing machines
● Packaging machines
All machinery must be corrosion-resistant, precision-calibrated, and comply with industry standards for safety, efficiency, and reliability, with refractory-lined, high-temperature equipment and dust and gas handling systems a particular consideration. Equipment selection and automation level are the primary determinants of machinery cost, which represents the largest single component of capital expenditure.
7. Capital Investment (CapEx) for a DRI Sponge Iron Plant:
Total capital investment for a DRI sponge iron plant depends on plant capacity, technology, and location, and covers land acquisition, site preparation, and necessary infrastructure.
IMARC's cost analysis breaks CapEx into four categories:
Land and Site Development Costs: Land registration, boundary development, and related site-preparation charges
Civil Works Costs: Construction of production halls, storage, and supporting civil infrastructure
Machinery Costs: Rotary kilns, gas reformers, cooling systems, pelletizing machines, and packaging machines
Other Capital Costs: Pre-operative expenses and miscellaneous capital items
Machinery costs account for the largest portion of total capital expenditure, while land and site development costs - covering registration, boundary development, and related charges - form a substantial part of the overall investment as well.
Because the exact split varies significantly with capacity, technology, and location, sponsors evaluating a specific project should work from a capacity- and location-specific cost model rather than a generic industry average.
8. Operating Cost (OpEx) Structure:
Operating expenditure for a DRI sponge iron plant is overwhelmingly dominated by feedstock cost, particularly iron ore.
Based on IMARC's analysis:
● Raw Materials (iron ore, coal/natural gas, dolomite): 70-80% of total OpEx
● Utilities: 15-20% of total OpEx
● Transportation, Packaging, Salaries & Wages, Depreciation, Taxes, Other Expenses: Remaining balance of total OpEx
This cost structure has a direct strategic implication: iron ore and reductant procurement strategy is by far the dominant lever for OpEx control in a DRI plant, with utilities a meaningful secondary cost given the energy-intensive reduction step. In the first year of operations, operating costs cover raw materials, utilities, depreciation, taxes, packing, transportation, and repairs and maintenance; by the fifth year, total operational cost is expected to increase substantially due to inflation, market fluctuations, and potential rises in the cost of key materials, alongside supply chain disruptions, rising consumer demand, and shifts in the global economy.
Buy Now: https://www.imarcgroup.com/checkout?id=30549&method=2175
9. Profitability and Financial Outlook:
A DRI sponge iron manufacturing plant demonstrates healthy profitability potential under normal operating conditions, supported by stable demand and value-added applications:
● Gross Profit Margin: 25-35%
● Net Profit Margin: 12-18%
Financial projections for a specific project should be developed from realistic assumptions on capital investment, operating costs, production capacity utilization, pricing trends, and demand outlook, and should incorporate ROI, net present value (NPV), payback period, and a full profit-and-loss analysis rather than relying on the industry-average margins above as a substitute. These averages are useful for feasibility screening, not for financing-stage decisions. Because sponge iron prices track the steel cycle and input costs move with iron ore and energy markets, sensitivity analysis on spreads is especially important for this plant type.
10. Regulatory and Policy Landscape:
Project sponsors evaluating a DRI sponge iron manufacturing plant should plan for:
Business registration and factory licensing
● Environmental clearances, typically including air emission, dust, and water-use approvals for heavy industry
● Fire and industrial safety certifications, with particular attention to high-temperature equipment and gas handling
● Mining or raw material linkage and transport approvals, where ore and coal are sourced under licensed arrangements
● Effluent treatment and emission control compliance systems
Industry-specific permits, which vary by local, state, and national jurisdiction
Advanced monitoring systems to detect leaks or process deviations should be installed alongside these compliance measures, and government incentives - capital subsidies, tax exemptions, reduced utility tariffs, export benefits, or interest subsidies - may also be available depending on the region and should be factored into project financing. Because DRI plants are carbon- and energy-intensive heavy industry, tightening emissions rules and carbon-pricing schemes are a design and financing consideration, and also a reason green-hydrogen-based routes are attracting investment.
11. Leading DRI Sponge Iron Manufacturers:
Leading manufacturers in the global DRI sponge iron industry include several multinational companies with extensive production capacities and diverse application portfolios, including:
● AM/NS India
● ArcelorMittal
● Ghadir Iron and Steel Company
● Jindal Shadeed Iron & Steel LLC
● Khorasan Steel II
● Khouzestan Steel Company
● Kobe Steel Ltd
These companies collectively serve end-use sectors spanning steel manufacturing, foundries, automotive, and construction and infrastructure.
Browse Full Report: https://www.imarcgroup.com/dri-sponge-iron-manufacturing-plant-project-report
Frequently Asked Questions:
1. How much capital is required to start a DRI sponge iron manufacturing plant?
Capital requirements generally include land acquisition, construction, equipment procurement (rotary kilns, gas reformers, cooling systems, pelletizing machines, packaging machines), installation, pre-operative expenses, and initial working capital. The total amount varies with capacity, process route, and location, and is substantially higher than for most other plant types.
2. How do I start a DRI sponge iron manufacturing business?
Starting a DRI sponge iron manufacturing business requires a market feasibility study, securing required licenses and environmental clearances, arranging funding, selecting suitable land with good raw material and rail or port access, procuring equipment, recruiting skilled labor, and establishing long-term supply arrangements for ore and energy and a customer base among steel plants.
3. What raw materials are required for DRI sponge iron manufacturing?
DRI sponge iron manufacturing primarily uses iron ore, coal or natural gas as the reductant and energy source, and dolomite.
4. What machinery and equipment are required to start a DRI sponge iron factory?
A DRI sponge iron factory typically requires rotary kilns, gas reformers, cooling systems, pelletizing machines, and packaging machines, along with raw material handling and environmental control systems.
5. What are the biggest challenges in starting a DRI sponge iron manufacturing business?
Very high capital requirements, securing environmental and other regulatory approvals, exposure to iron ore and energy price swings, dependence on the steel cycle, access to natural gas or suitable coal, and meeting emissions and decarbonization expectations.
6. Who are the top DRI sponge iron manufacturers in the world?
AM/NS India, ArcelorMittal, Ghadir Iron and Steel Company, Jindal Shadeed Iron & Steel LLC, Khorasan Steel II, Khouzestan Steel Company, and Kobe Steel Ltd.
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers create a lasting impact. The company excels in understanding its clients' business priorities and delivering tailored solutions that drive meaningful outcomes. IMARC Group provides a comprehensive suite of market entry and expansion services, including market assessment, greenfield plant feasibility study, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: (+1-201-971-6302)
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release DRI Sponge Iron Manufacturing Plant Project Report, Feasibility Study 2026: CapEx/OpEx , ROI Analysis and Business Plan here
News-ID: 4662253 • Views: …
More Releases from IMARC Group
Water Heater Plant Setup Cost 2026: Manufacturing Business Opportunity, Investme …
Setting up a water heater manufacturing plant in 2026 requires clarity on a few core variables: tank and component sourcing, production capacity, capital investment, operating cost structure, and profitability under prevailing market conditions. This feasibility study covers the water heater manufacturing plant cost, and the machinery and raw materials needed. The India water heater market was valued at USD 1.23 Billion in 2025 and is projected to reach USD 2.15…
India Power Market 2026-2034: Capacity Expected to Reach 1,154.2 GW at 7.24% CAG …
How Is India's Power Market Performing?
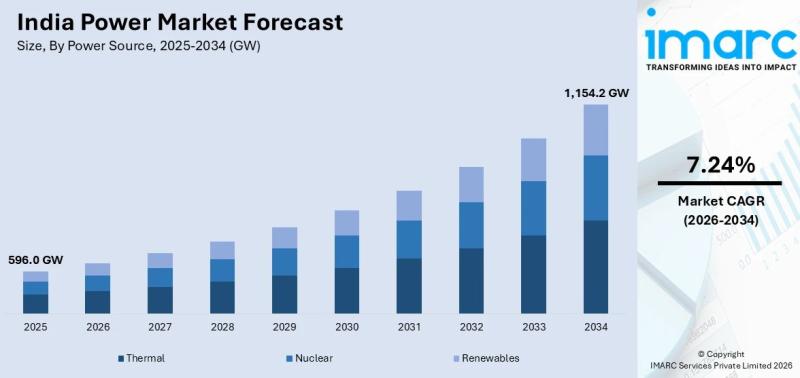
India's power sector is moving from a supply-focused system into a smarter, cleaner, and more digitally managed energy network. The market covers generation capacity across thermal, nuclear, and renewable sources, serving utilities, commercial and industrial users, and households across the country's four regions. The India power market reached 596.0 GW in 2025 and is projected to reach 1,154.2 GW by 2034, exhibiting a CAGR of…
Smart Greenhouse Market to Reach USD 4.3 Billion by 2034, Growing at 7.56% CAGR
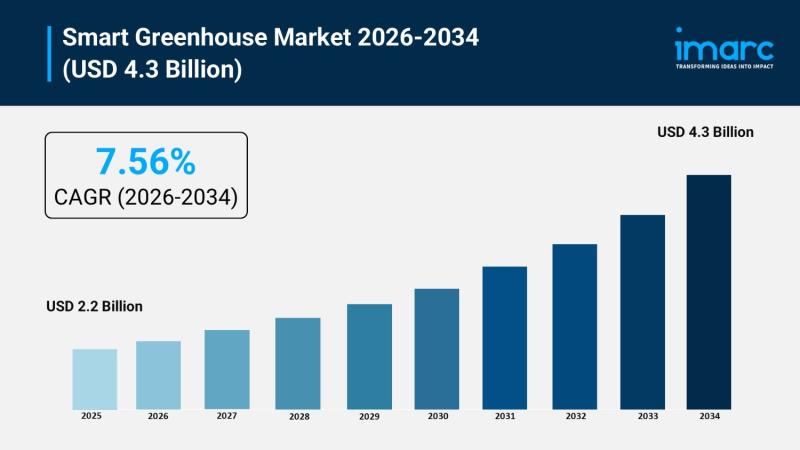
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the smart greenhouse market. The global smart greenhouse market size was valued at USD 2.2 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 4.3 Billion by 2034, exhibiting a CAGR of 7.56% from 2026-2034, driven by the adoption of IoT and AI-driven automation for real-time climate…
Diethyl Ether Plant Setup Cost 2026: Production Technology, Machinery, Operating …
Setting up a diethyl ether production plant in 2026 requires selecting an appropriate production route, ensuring a reliable feedstock supply, determining plant capacity, and planning for process equipment, investment, and operating costs. This feasibility study examines the diethyl ether production plant cost, including the machinery and raw materials required for manufacturing. Diethyl ether is a highly volatile solvent used in pharmaceutical processing, chemical synthesis, laboratory applications, and various industrial operations.…
More Releases for DRI
Direct Reduced Iron (DRI) Market Status, Share, Growth & Outlook | 2025 - 2032
Global Direct Reduced Iron (DRI) Market Report Summary
According to industry estimates the Direct Reduced Iron (DRI) market growth is projected to expand 5.2% CAGR during the 2025 to 2032 assessment period.
The Latest Market Research report on "Global Direct Reduced Iron (DRI) Market Report 2025 - Future Opportunities, Latest Trends, In-depth Analysis, and Forecast To 2032" offers strategic visions into the global Direct Reduced Iron (DRI) market along with the market…
How To Setup a DRI Sponge Iron Manufacturing Plant: Machinery Requirement
Setting up a DRI sponge iron manufacturing facility necessitates a detailed market analysis alongside granular insights into various operational aspects, including unit processes, raw material procurement, utility provisions, infrastructure setup, machinery and technology specifications, workforce planning, logistics, and financial considerations.
IMARC Group's report titled "DRI Sponge Iron Manufacturing Plant Project Report 2025: Industry Trends, Plant Setup, Machinery, Raw Materials, Investment Opportunities, Cost and Revenue" offers a comprehensive guide for establishing…
Direct Reduced Iron (DRI) Market to Set Phenomenal Growth by 2031
𝐃𝐢𝐫𝐞𝐜𝐭 𝐑𝐞𝐝𝐮𝐜𝐞𝐝 𝐈𝐫𝐨𝐧 𝐌𝐚𝐫𝐤𝐞𝐭: 𝐈𝐧𝐭𝐫𝐨𝐝𝐮𝐜𝐭𝐢𝐨𝐧
Transparency Market Research delivers key insights on the global direct reduced iron market. In terms of revenue, the global direct reduced iron market is estimated to expand at a CAGR of 8% during the forecast period, owing to numerous factors regarding which TMR offers thorough insights and forecast in its report on the global direct reduced iron market.
The global direct reduced iron market is broadly affected by several factors…
Direct Reduced Iron (DRI) Market Promising Growth Opportunities over 2020-2030
A recent market study published by FMI on the DRI market includes the global industry analysis of 2015-2019 & opportunity assessment for 2020-2030, and delivers a comprehensive assessment of the most important market dynamics. Our analysts conduct thorough research on the historical as well as current growth parameters of the market to obtain growth prospects with maximum precision.
Request Report Sample@ https://www.futuremarketinsights.com/reports/sample/rep-gb-11635
Direct Reduced Iron (DRI) Market: Segmentation
Production Process
• Coal-based
• Gas-based
Application
• Steel Production
• Construction
Form
• Lumps
• Pellets
Region
• North America
• Latin America
• Europe
• South…
Global Cat Litter Market 2019 - Nestle, Clorox, Church & Dwight, Oil-Dri
This new report by Eon Market Research, titled “Global Cat Litter Market 2019 Research Report, 2015 – 2025” offers a comprehensive analysis of Cat Litter industry at a global as well as regional and country level. Key facts analyzed in this report include the Cat Litter market size by players, regions, product types and end industries, history data 2014-2018 and forecast data 2019-2025. This report primarily focuses on the study…
Global Soda Crystals Market 2019 - Solvay, Tata Chemicals, Bexters, Dri-Pak
A new market research study by Apex Market Research has projected that Soda Crystalsrevenues will exceed $XX Billion by 2023 at a CAGR of XX%. Market statistics is published in Global Soda Crystals Market 2019-2026 report.
The Global Soda Crystals Market 2019-2026 report delivers comprehensive information about the Soda Crystals industry including valuable facts and figures, important aspects, and skilled opinions providing businesses with decisive information. The report covers global perspective…

