


Press release
Australia Semiconductor Market 2026 | Worth USD 25.35 Billion by 2034
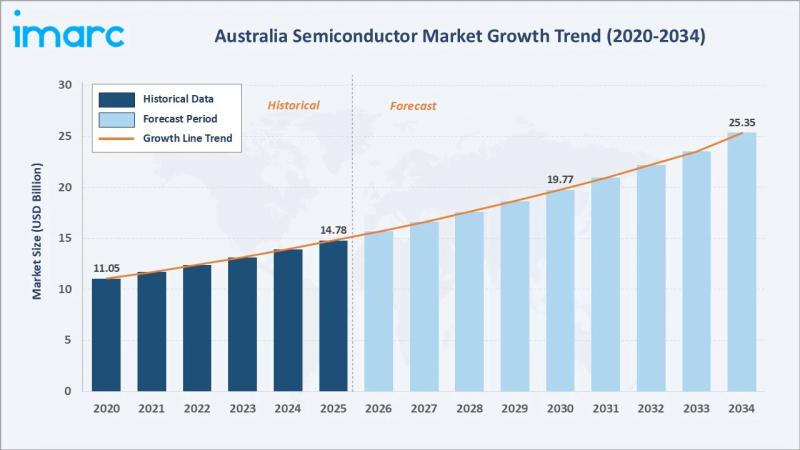
The Australia semiconductor market is experiencing strong growth, driven by strong government incentives, rising IoT and consumer electronics demand, proximity to Asia-Pacific supply chains, and cross-sector innovation culture. According to IMARC Group, the market size increased from USD 14.78 Billion in 2025 to USD 15.92 Billion in 2026 and is projected to reach USD 25.35 Billion by 2034, exhibiting a CAGR of 5.99% during 2026-2034.
Semiconductors underpin Australia's defence, telecommunications, mining, clean energy, and quantum computing sectors, creating non-discretionary demand for diverse chip architectures. The growth trajectory from 2020 through 2034, with the historical expansion to USD 14.78 Billion in 2025 and an estimated USD 15.92 Billion in 2026, reflects consistent government-driven and innovation-led demand, while the forecast to USD 25.35 Billion captures accelerating domestic manufacturing, quantum technology investment, and IoT-driven chip demand. Memory Devices lead the component mix at 22.8%, Silicon Carbide dominates materials at 34.7%, and ACT & New South Wales commands 33.4% regional share in 2025.
The Australia semiconductor market is on track to reach USD 25.35 Billion by 2034, expanding at a 5.99% CAGR. Supported by government incentives, quantum technology investment, and clean energy semiconductor demand, the sector offers compelling opportunities for chip designers, technology providers, and investors across the value chain.
Request a Sample Report for In Depth Market Insights:
https://www.imarcgroup.com/australia-semiconductor-market/requestsample
Australia Semiconductor Market Summary
Semiconductors are the foundational electronic components enabling computing, communication, sensing, power conversion, and memory storage. The Australian ecosystem spans chip designers, EDA software providers, test and measurement companies, packaging partners, foundry collaborations, and diverse end-use industries spanning defence, mining, clean energy, healthcare, and telecommunications. The national ecosystem integrates university research centres, government-funded innovation hubs, international semiconductor companies with local design and sales offices, and a growing cohort of semiconductor startups targeting niche applications in quantum, IoT, and defence electronics.
By component, Memory Devices command a 22.8% majority share in 2025 owing to Australia's accelerating data centre buildout, cloud services adoption, and consumer electronics demand. Logic Devices at 18.6% in 2025 reflect the expanding embedded processing requirements of industrial automation, telecommunications infrastructure, and defence systems. Analog ICs (14.2%), MPUs (11.3%), and Discrete Power Devices (10.4%) collectively serve industrial control, computing, and power management applications. MCUs (9.6%) and Sensors (7.8%) address the rapidly expanding IoT and smart infrastructure segments. By material used, Silicon Carbide dominates at 34.7% in 2025, driven by Australia's clean energy transition agenda. Gallium Manganese Arsenide at 22.6% serves high-frequency RF and microwave applications. Copper Indium Gallium Selenide (16.8%) addresses photovoltaic and optoelectronic applications. Molybdenum Disulfide (12.4%) is gaining traction in next-generation transistor research. Regionally, ACT & New South Wales leads at 33.4%, followed by Victoria & Tasmania at 24.2%, Queensland at 17.6%, Western Australia at 13.9%, and NT & South Australia at 10.9%.
Key Trends Shaping the Australia Semiconductor Market
Quantum Semiconductor Commercialisation Gaining Momentum
Australia's significant quantum technology investments, including a large-scale fault-tolerant silicon quantum computer facility under construction in Brisbane, combined with private sector quantum ventures raising substantial funding in 2024, are establishing Australia as a global quantum semiconductor commercialisation leader through 2034. Australia leads globally in silicon-spin qubit research, with leading university groups demonstrating record-fidelity two-qubit gates in silicon.
Compound Semiconductors Enabling Clean Energy and Defence Applications
Silicon Carbide and Gallium Nitride compound semiconductor devices are enabling Australia's solar inverters, EV charging infrastructure, and defence radar systems to achieve superior switching efficiency and thermal performance, driving above-market growth in the materials and discrete power device segments throughout the forecast period. Silicon Carbide devices achieve blocking voltages above 3.3 kV and switching frequencies beyond 100 kHz, enabling compact, efficient power converters for utility-scale solar farms and battery storage systems.
AI-Driven Edge Computing Generating Specialised Chip Demand
Industrial AI applications in Australian mining automation, precision agriculture, and predictive healthcare are driving demand for edge AI inference chips optimised for low power consumption and harsh environmental conditions, creating differentiated opportunities for local semiconductor design startups focused on uniquely Australian challenges.
Advanced Packaging and Chiplet Architecture Reducing Foundry Dependency
Advanced packaging technologies including 2.5D interposers, fan-out wafer-level packaging, and chiplet integration enable Australian designers to combine best-of-breed chips from multiple foundries, reducing single-source dependency and creating local value-add in assembly and integration services.
Silicon Photonics and Quantum Device Technologies
Australia leads globally in silicon-spin qubit research, with leading university groups demonstrating record-fidelity two-qubit gates in silicon. These advances are translating into commercial quantum chip development through local ventures, positioning Australia at the frontier of next-generation semiconductor architectures with significant global commercialisation potential.
Market Growth Drivers
The Australia semiconductor market is propelled by multiple robust demand drivers that collectively support sustained expansion through 2034:
Strategic Government Support and Policy Initiatives: Australian federal and state governments have deployed coordinated incentive frameworks, including national semiconductor R&D grants, the National Semiconductor Manufacturing Hub initiative, and targeted university-industry co-investment programs that have created a virtuous cycle of talent development and private sector investment.
Asia-Pacific Tech Ecosystem Proximity and Supply Chain Resilience: Australia's geographic proximity to key semiconductor production centres in Taiwan, South Korea, Singapore, and Japan enables just-in-time procurement and design collaboration. Its stable political environment and advanced logistics infrastructure attract international semiconductor firms seeking diversified supply chain nodes.
Rising Demand for Consumer Electronics and IoT Devices: Expanding 5G network coverage, smart home device proliferation, connected mining equipment, precision agriculture sensors, and digital health monitoring devices are generating substantial incremental semiconductor demand across all component categories, particularly memory, sensors, and microcontrollers.
Innovation Culture Anchored by Cross-Sector Applications: Australia's unique cross-sector application landscape, ruggedised mining electronics, outback remote sensing, offshore environmental monitoring, and clean energy power management, drives custom semiconductor IP development that serves both domestic and global markets with differentiated, application-specific solutions.
Australia Semiconductor Market Segmentation
• By Components: Memory Devices (22.8% share in 2025), Logic Devices (18.6%), Analog IC (14.2%), MPU (11.3%), Discrete Power Devices (10.4%), MCU (9.6%), Sensors (7.8%), Others
• By Material Used: Silicon Carbide (34.7% share in 2025), Gallium Manganese Arsenide (22.6%), Copper Indium Gallium Selenide (16.8%), Molybdenum Disulfide (12.4%), Others
• By End User: Automotive, Industrial, Data Centre, Telecommunication, Consumer Electronics, Aerospace and Defense, Healthcare, Others
• By Region: Australia Capital Territory & New South Wales (33.4% share in 2025), Victoria & Tasmania (24.2%), Queensland (17.6%), Western Australia (13.9%), Northern Territory & Southern Australia (10.9%)
Government Policies and Regulatory Landscape
The Australian government has implemented supportive policy frameworks that positively influence the semiconductor market. Australian federal and state governments have deployed coordinated incentive frameworks, including national semiconductor R&D grants, the National Semiconductor Manufacturing Hub initiative, and targeted university-industry co-investment programs that have created a virtuous cycle of talent development and private sector investment.
Australia's stable regulatory framework and advanced port infrastructure position it to develop pilot packaging, testing, and niche wafer fabrication lines, serving mining, healthcare, and renewable energy customers with accelerated delivery and enhanced supply security against global disruptions. Australia's National Semiconductor Manufacturing Hub, targeting pilot fabrication scale-up by 2027, will catalyse downstream ecosystem formation, reduce import dependency for niche applications, and anchor talent retention through competitive local career pathways in advanced semiconductor manufacturing.
Competitive Landscape
The Australian semiconductor market is served primarily by subsidiaries, design centres, and distribution operations of major global semiconductor corporations, alongside a growing cohort of domestically founded design startups targeting niche quantum, mining, and clean energy applications. The market is moderately concentrated at the distribution level, with global leaders holding strong positions, while the domestic design and startup ecosystem remains fragmented. No single company holds more than 10-12% of total Australian semiconductor market revenue.
Key players in the Australia semiconductor market include:
• Intel Corporation - Leader; Xeon 6, Core Ultra, Agilex FPGA; data centres, AI compute, defense HPC, local design, and government technology partnerships
• Qualcomm Incorporated - Leader; Snapdragon; mobile, IoT, 5G chipsets; 5G network infrastructure and carrier partnerships
• Samsung - Leader; DRAM, NAND Flash, Exynos; memory supply; consumer electronics and enterprise storage
• Texas Instruments Incorporated - Leader; Analog ICs, MCUs, DSPs; industrial, automotive, clean energy, power management; broad distributor network
• Infineon Technologies AG - Leader; SiC, IGBT, Security ICs; power electronics, automotive, clean energy; SiC growth in the renewable energy segment
• NXP Semiconductors - Challenger; Automotive ICs, i.MX, RF; automotive, industrial IoT, secure connectivity, and smart infrastructure applications
Browse Full Report with TOC & List of Figures for In Depth Market Insights:
https://www.imarcgroup.com/australia-semiconductor-market
Porter's Five Forces Analysis - Australia Semiconductor Market
Competitive Rivalry: Moderate. The Australia semiconductor market is moderately concentrated at the distribution level, with global leaders holding strong positions, while the domestic design and startup ecosystem remains fragmented. No single company holds more than 10-12% of total Australian semiconductor market revenue, reflecting the market's diverse end-use base and the absence of a dominant domestic manufacturer. Business implication: Companies must differentiate through application-specific solutions, government partnerships, and niche technology capabilities to capture and retain market share.
Supplier Power (Foundries and Materials): Moderate to High. Suppliers of silicon wafers, process chemicals, and advanced-node foundry capacity hold significant influence. Australia lacks advanced-node semiconductor fabrication facilities, compelling even locally designed chips to rely on overseas foundries for high-volume production, creating extended lead times, supply vulnerability, and limited opportunity to build ancillary manufacturing industries domestically. Business implication: Companies must diversify foundry partnerships and invest in advanced packaging capabilities to reduce single-source dependency.
Buyer Power (Industrial and Government End Users): Moderate to High. Buyers range from defence agencies and mining companies to telecommunications operators and consumer electronics manufacturers. Government and defence customers with significant procurement volumes negotiate favourable terms and require sovereign capability assurances. However, specialised application requirements and technology expertise remain critical differentiators. Business implication: Suppliers must demonstrate application expertise, supply security, and sovereign capability credentials to secure and retain major contracts.
Threat of Substitutes: Low. Direct substitutes for semiconductors are limited in most applications. Alternative technologies such as photonics and quantum computing represent complementary rather than substitute technologies. For computing, communication, sensing, and power conversion applications, semiconductors remain the foundational technology. Business implication: Semiconductor demand benefits from sustained growth as digital transformation accelerates across all industries.
Threat of New Entrants: Moderate. Significant capital requirements for chip design, EDA tools, and testing facilities create meaningful entry barriers. However, the growing market, government support, and cloud-based EDA platforms offer opportunities for specialised entrants focusing on niche applications. Cloud EDA models lower capital barriers for startups and university spinouts targeting niche markets in defence, quantum, and industrial IoT. Business implication: Niche and innovation-focused entrants can access the growing market by targeting specialised applications or emerging technology categories.
Regional Analysis
The Australia semiconductor market exhibits distinct regional dynamics, with ACT & New South Wales commanding the largest share at 33.4% in 2025, followed by Victoria & Tasmania at 24.2%, Queensland at 17.6%, Western Australia at 13.9%, and NT & South Australia at 10.9%.
ACT & New South Wales (33.4%): ACT & New South Wales' dominance in 2025 is driven by the highest concentration of semiconductor-linked research institutions, federal government procurement, defence facilities, and technology startup density in Australia. University quantum computing research groups and national fabrication facilities anchor regional market leadership. Highest concentration of government R&D investment, research institutions, defence precincts, and technology innovation hubs.
Victoria & Tasmania (24.2%): Victoria & Tasmania benefits from Melbourne's advanced manufacturing ecosystem, strong university research, and proximity to defence and aerospace industry clusters across metropolitan and regional Victoria. Advanced manufacturing ecosystem, strong university research output, defence aerospace industry, and technology startup activity support market growth.
Queensland (17.6%): Queensland is experiencing the most dynamic growth inflection, anchored by large-scale quantum computing facility investments in Brisbane, which are expected to catalyse downstream semiconductor supply chain investment and talent cluster formation through the forecast period. Quantum technology investment, university research and development, mining electronics, and defence technology programs.
Western Australia (13.9%): Western Australia's market is driven by mining ruggedised electronics, remote sensing applications, port logistics infrastructure, and resources sector technology demand. Mining ruggedised electronics, remote sensing applications, port logistics infrastructure, and resources sector technology demand support market growth.
NT & South Australia (10.9%): NT & South Australia benefits from defence industry presence, autonomous systems development, remote connectivity semiconductor demand, and government technology programs.
Key Aspects Required for the Australia Semiconductor Market
• Demand spans multiple end-use industries: Automotive, industrial, data centre, telecommunication, consumer electronics, aerospace and defense, healthcare, and others all contribute to the diversified demand base.
• Strong government support tailwinds: Australian federal and state governments have deployed coordinated incentive frameworks, including national semiconductor R&D grants and the National Semiconductor Manufacturing Hub initiative.
• Memory Devices lead the component mix: Memory Devices command a 22.8% majority share in 2025, driven by Australia's accelerating data centre buildout, cloud services adoption, and consumer electronics demand.
• Silicon Carbide leads the material segment: Silicon Carbide dominates at 34.7% in 2025, driven by Australia's clean energy transition agenda, electric vehicle charging infrastructure rollout, and power electronics demand.
• Quantum technology is a key growth accelerator: Australia's significant quantum technology investments, including a large-scale fault-tolerant silicon quantum computer facility under construction in Brisbane, are establishing Australia as a global quantum semiconductor commercialisation leader.
• ACT & New South Wales dominates regionally: ACT & New South Wales commands a dominant 33.4% market share in 2025, driven by federal R&D investment, national fabrication facilities, defence precincts, and leading semiconductor-linked universities.
• Positive market outlook: The market is projected to grow from USD 14.78 Billion in 2025 to USD 25.35 Billion by 2034 at a CAGR of 5.99%, adding USD 10.57 Billion in incremental annual market value over the forecast period.
Recent Industry Developments
Important note: Specific recent industry developments with dates and company names were not available in the source page content provided beyond the company profiles and market trends outlined above. The market is driven by ongoing government investment, quantum technology commercialisation, and clean energy semiconductor demand.
Report Format, Delivery, and Customization Details
• Report Format Mode: PPT, PDF, and Excel
• Report Delivery Mode: Online Delivery, Physical Delivery
• Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
• Report Confirmation Mode: Yes via Email
• Report Customization Mode: Yes via Email / Call
• Report Table of Content: Yes
• Report List of Figures: Yes
• Report Methodology Mode: Yes
• Request For Sample Report: Yes
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
https://www.imarcgroup.com/request?type=report&id=36010&flag=E
Other reports by IMARC Group
Australia MedTech Market
https://www.imarcgroup.com/australia-medtech-market
Australia Green Hydrogen Market
https://www.imarcgroup.com/australia-green-hydrogen-market
Australia Beverage Packaging Market
https://www.imarcgroup.com/australia-beverage-packaging-market
Contact Us
IMARC Group
134 N 4th St., Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-631-791-1145
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Australia Semiconductor Market 2026 | Worth USD 25.35 Billion by 2034 here
News-ID: 4649337 • Views: …
More Releases from IMARC Group
Australia Fertilizer Market 2026 | Worth USD 3.9 Billion by 2034
Market Overview
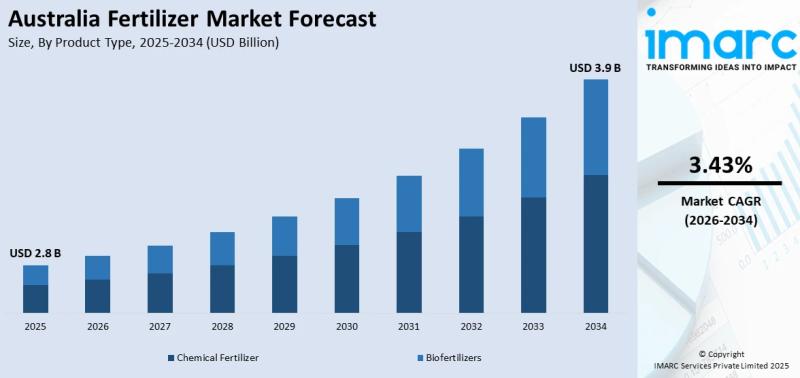
The Australia fertilizer market is experiencing steady growth, driven by increasing preferences among farmers across the country towards organic product variants that promote soil health and minimize ecological impact. According to IMARC Group, the market size increased from USD 2.8 Billion in 2025 to USD 2.9 Billion in 2026 and is projected to reach USD 3.9 Billion by 2034, exhibiting a growth rate (CAGR) of 3.43% during 2026-2034.
Fertilizer is…
Germany Pharmaceutical Market Size to Reach USD 120.79 Billion by 2034 at 6.44% …
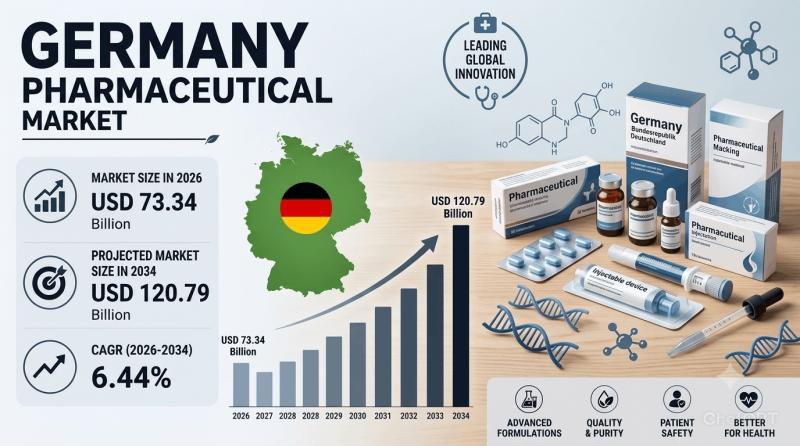
The Germany pharmaceutical market is experiencing robust growth, driven by a high burden of chronic diseases, an aging population, strong R&D investment, and universal health insurance coverage. The market size increased from USD 68.91 Billion in 2025 to USD 73.34 Billion in 2026 and is projected to reach USD 120.79 Billion by 2034, exhibiting a robust CAGR of 6.44% during 2026-2034. In 2024, 53.7% of adults in Germany were living…
Europe Wine Market 2026 | Worth USD 116.9 Billion by 2034
Market Overview
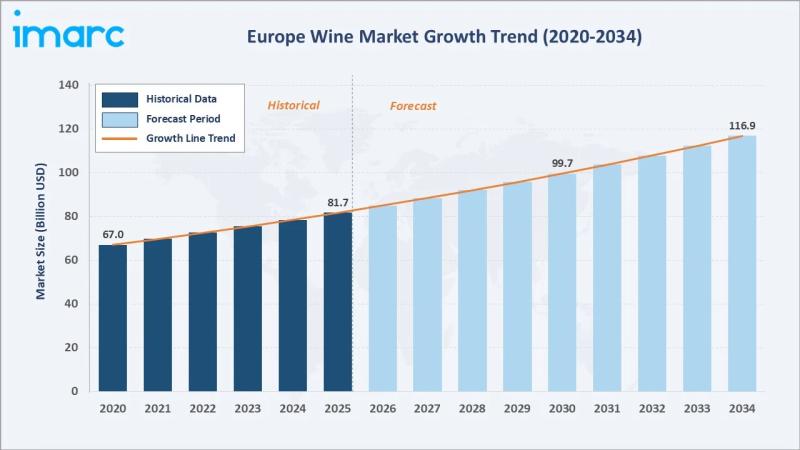
The Europe wine market is experiencing steady growth, driven by strong cultural consumption, premiumization, tourism-linked demand, and the region's established wine-producing heritage. According to IMARC Group, the market grew from USD 81.7 Billion in 2025 to USD 85.0 Billion in 2026 and is projected to reach USD 116.9 Billion by 2034, growing at a CAGR of 4.06% during 2026-2034.
Growth is also supported by rising demand for organic, sustainable, and…
Brazil Freight and Logistics Market Size to Reach USD 162.03 Billion by 2034, Gr …
Brazil Freight and Logistics Market Report 2026
Market Size in 2025: USD 110.26 Billion
Market Size in 2026: USD 115.08 Billion
Market Forecast in 2034: USD 162.03 Billion
Market Growth Rate: 4.37% (2026-2034)
According to the latest report by IMARC Group, titled "Brazil Freight and Logistics Market: Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034," the Brazil freight and logistics market grew from USD 110.26 Billion in 2025 to USD 115.08 Billion in 2026.…
More Releases for Australia
Derila Memory foam pillow Australia: Honest Reviews About Derila Australia
Derila is one of the best memory foam pillows sold in Australia today.
Priced at around 30 dollars (USD), derila is currently the most reviewed and the cheapest memory pillow available in Australia.
What is Derila? Is Derila Pillow the best in Australia? Keep reading to discover everything worth knowing about Derila Australia.
OVERVIEW
Recently, Memory foam pillow has been trending and there is a lot of brands to choose from. Which one is…
CeraCare Australia - Where to Buy Legit CeraCare Supplement in Australia?
CeraCare Australia - Ceracare is a glucose support supplement that proposes to augment cardiovascular prosperity and to stay aware of perfect glucose assimilation in Australia. CeraCare supplement is conceptualized and executed by a threesome – Christine, Dr. Jihn and Michael. It is a natural supplement that helps one stay aware of ideal glucose levels, cardiovascular prosperity, and glucose assimilation.
Take Advantage of 80% Discount Offer in Australia >> https://boostsxproaustralia.com/ceracare-new
The indications…
Glucofort Australia - Where to Buy Legit Glucofort Supplement in Australia?
Glucofort Australia - Glucofort is an efficient, all-natural progressive glucose support supplement in Australia. This formula is made out of 12 key ingredients, 7 nutrients, and minerals, and a little of Vanadium. This supplement upholds regulated glucose levels and glucose digestion. Glucofort prides itself as the most inventive supplements available in Oceania, accentuating its solidarity, wellbeing, and quality.
Take Advantage of 75% Discount Offer in Australia >> https://boostsxproaustralia.com/glucofort-new
Rather than simply…
Australia Agriculture Market, Australia Agriculture Industry, Australia Agricult …
Australia Agriculture has been as vital within the development of Australia, because it was within the United States. Australia's ancient dominance in wheat and sheep continues into the 21st century. Recently Australian agriculture has become more and more diversified. The considerable expanses of productive land have helped Australia to become a number one world exporter of grains, meats, and wool. Each grains (predominantly wheat and barley) and wool markets round…
Australia Conveyor Maintenance Analysis by Top Companies Habasit Australia Pty l …
Global Australia Conveyor Maintenance Market and Competitive Analysis
Know your current market situation! Not only a vital element for brand new products but also for current products given the ever-changing market dynamics. The study allows marketers to remain involved with current consumer trends and segments where they'll face a rapid market share drop. Discover who you actually compete against within the marketplace, with Market Share Analysis know market position, to push…
Australia Conveyor Maintenance Market Analysis By Manufacturers Rema Tip Top Aus …
A conveyor system is a common piece of mechanical handling device that moves materials/objects from one location. A conveyor is often lifeline to a company’s ability to effectively move its products in a timely manner. While it is used constantly in a manufacturing plant, proper maintenance from trained technicians can extend the lifespan of conveyor. Furthermore, conveyor maintenance is essential as it may be subjected to different types of failures…

