


Press release
Europe Wine Market 2026 | Worth USD 116.9 Billion by 2034
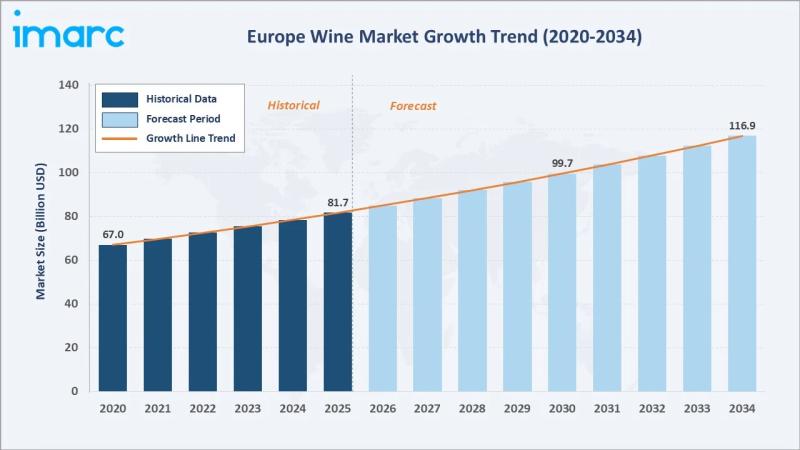
The Europe wine market is experiencing steady growth, driven by strong cultural consumption, premiumization, tourism-linked demand, and the region's established wine-producing heritage. According to IMARC Group, the market grew from USD 81.7 Billion in 2025 to USD 85.0 Billion in 2026 and is projected to reach USD 116.9 Billion by 2034, growing at a CAGR of 4.06% during 2026-2034.
Growth is also supported by rising demand for organic, sustainable, and low-alcohol wine varieties. The European Union remains the leading wine producer, with an average annual production of 157 million hectolitres between 2020 and 2025. This strong production base supports Europe's wine market by ensuring wide availability, export strength, product variety, and continued investment in vineyards, wineries, and premium wine categories. The market expanded from USD 67.0 Billion in 2020 to USD 81.7 Billion in 2025 and an estimated USD 85.0 Billion in 2026, anchored at USD 99.7 Billion in 2030 and forecast to reach USD 116.9 Billion by 2034. Still wine dominates at 68.4%. Red wine leads color at 47.6%. France commands 24.8% of the European market.
The Europe wine market is on track to reach USD 116.9 Billion by 2034, expanding at a 4.06% CAGR. Supported by premiumization trends, e-commerce expansion, and low-alcohol category innovation, the sector offers compelling opportunities for producers, distributors, and investors across the value chain.
Request a Sample Report for In Depth Market Insights:
https://www.imarcgroup.com/europe-wine-market/requestsample
Europe Wine Market Summary
The European wine market encompasses production, trade, and consumption across the full range of wine categories. The European wine ecosystem integrates vineyards across Europe, individual wine producers ranging from single-hectare artisan vignerons to industrial cooperative wineries, regional wine trade organizations, national wine institutes, and global wine trade organizations. Macroeconomic factors include stable disposable incomes, strong tourism activity, hospitality sector growth, and export-oriented wine trade.
By product type, still wine leads at 68.4% in 2025. The still wine category's commercial architecture spans from everyday table wine through regional PDO wines, through premium appellations, to the fine wine tier. Sparkling wine at 21.7% growing at ~4.6% CAGR is the market's most commercially dynamic segment. Fortified wine and vermouth at 9.9% encompasses port and sherry as heritage categories alongside Vermouth's cocktail culture revival. By color, red wine leads at 47.6% in 2025, reflecting its dominance in European food culture and its concentration in the fine wine investment market. White wine at 38.2% is growing fastest at ~4.1% CAGR through its dominance, mass market accessibility, and emerging premium whites. Rose wine at 14.2% is sustained by Provence Rose's lifestyle positioning. Regionally, France leads at 24.8%, followed by Italy at 21.6%, Germany at 18.3%, the United Kingdom at 14.7%, Spain at 12.1%, and others at 8.5%.
Key Trends Shaping the Europe Wine Market
Natural Wine Movement Reshaping Consumer Expectations
The natural wine movement is increasing demand for minimal-intervention, artisanal and terroir-driven wines. Consumers are showing greater interest in authenticity, transparency, organic farming and unique flavor profiles. This trend is influencing wine bars, restaurants and specialty retailers to expand natural wine selections. It is also encouraging producers to experiment with traditional methods, lower additives and more sustainable vineyard practices.
Climate Change Enabling English Sparkling Wine and New European Wine Regions
Climate change is enabling new wine-producing areas, including English sparkling wine regions and emerging viticulture zones across parts of Northern and Central Europe. Warmer temperatures and longer growing seasons are improving grape cultivation conditions in areas previously considered unsuitable for winemaking. This is diversifying Europe's wine landscape and encouraging investment in new vineyards and production regions. The trend is also creating opportunities for innovative wine styles and regional differentiation.
Growth of Wine Subscriptions and Personalized Wine Discovery Platforms
Wine subscriptions and personalized discovery platforms are emerging as consumers seek convenient, curated and experience-led wine purchasing. These platforms use preferences, tasting profiles and purchase history to recommend wines suited to individual tastes. They help smaller wineries reach new consumers while supporting repeat purchases and brand loyalty. This trend is strengthening D2C sales and making wine discovery more engaging for younger digital consumers.
Low-Carbon Packaging Solutions Transforming European Wine Branding
Low-carbon packaging solutions are transforming European wine branding as producers use lightweight bottles, recycled materials, cans, bag-in-box and paper-based formats to reduce environmental impact. These formats help wineries communicate sustainability, modernity and convenience to eco-conscious consumers. Packaging innovation also lowers transport emissions and supports differentiation on retail shelves. In April 2026, Puklavec Family Wines partnered with Vaider and JRE-Jeunes Restaurateurs to launch Trois Femmes wine, combining its long winemaking heritage with modern, lower-carbon packaging. The project uses Vaider's carbon-neutral wine bottle, helping lower the product's overall environmental footprint.
Wine Tourism as Experiential Consumption Driver
France, Italy and Spain lead Europe's wine tourism market, followed by Portugal and Greece. Germany, Hungary, Romania, Austria and Bulgaria are also gaining recognition as emerging wine tourism destinations. This rising European wine tourism is turning wine consumption into an experiential activity linked to vineyard visits, tastings, festivals and regional food culture. It helps wineries build direct relationships with consumers and promote premium, local and heritage wines.
Market Growth Drivers
The Europe wine market is propelled by multiple robust demand drivers that collectively support sustained expansion through 2034:
Premium and Luxury Wine Premiumization: Premium and luxury wine premiumization demand is boosting as consumers increasingly prefer high-quality, heritage-led and origin-certified wines. Demand for aged wines, limited editions, organic labels and wines from renowned regions supports higher-value sales. Premiumization also benefits wineries by improving margins and encouraging investment in branding, packaging and wine tourism. This trend is especially strong across gifting, fine dining and export-oriented channels.
E-commerce and Direct-to-Consumer Wine Channel Development: E-commerce and direct-to-consumer wine channels are making wine discovery, comparison and purchasing more convenient for consumers. Online platforms help wineries reach customers beyond traditional retail and hospitality channels. D2C models also allow producers to build stronger customer relationships, offer subscriptions, curated boxes and exclusive labels. This supports premium wine sales and improves brand visibility across regional and international markets.
Wine Tourism as Experiential Consumption Driver: Rising European wine tourism is turning wine consumption into an experiential activity linked to vineyard visits, tastings, festivals and regional food culture. It helps wineries build direct relationships with consumers and promote premium, local and heritage wines.
Low and No-Alcohol Wine Category Development: Low and no-alcohol wine category development offers an opportunity by addressing the growing health-conscious and moderation-focused consumer base. These products allow wineries to retain younger consumers who are reducing alcohol intake without leaving the wine category.
Europe Wine Market Segmentation
• By Product Type: Still Wine (68.4% share in 2025), Sparkling Wine (21.7%, fastest-growing at ~4.6% CAGR), Fortified Wine and Vermouth (9.9%)
• By Color: Red Wine (47.6% share in 2025), White Wine (38.2%, fastest-growing at ~4.1% CAGR), Rose Wine (14.2%)
• By Distribution Channel: Off-Trade, On-Trade
• By Country: France (24.8% share in 2025), Italy (21.6%), Germany (18.3%), United Kingdom (14.7%), Spain (12.1%), Others (8.5%)
Government Policies and Regulatory Landscape
The European Union has implemented comprehensive regulatory frameworks that significantly influence the wine market. The European wine market operates within the wine sector regulations, which govern production standards, labeling requirements, and quality classifications across member states. The appellation system creates legally protected production zones that sustain hundreds of independent producers, ensuring product authenticity and origin protection.
Climate change is affecting grape quality, harvest timing, and yield consistency across key wine-producing regions. Rising temperatures, droughts, heatwaves and extreme weather events can alter grape composition and impact traditional wine profiles. Producers may face higher costs for irrigation, vineyard adaptation and climate-resilient cultivation practices. These challenges create uncertainty in production quality and long-term viticulture sustainability, encouraging investment in sustainable vineyard practices and cleaner production methods.
Competitive Landscape
The European wine market's competitive landscape is highly fragmented at the production tier but increasingly concentrated at the premium and luxury tier, where Champagne and fine wine estate portfolios command a disproportionate share of fine wine consumer spending through the brand architecture. The European wine market's concentration level is unusually low relative to most consumer goods categories. This fragmentation is structurally embedded in European wine through the appellation system. Concentration is notably higher in sparkling wine.
Key players in the Europe wine market include:
• LVMH - Market Leader; Moët & Chandon, Dom Pérignon, Veuve Clicquot, Krug, Ruinart, Château d'Yquem, Chandon, Cloudy Bay; dominant force in the European wine industry, focusing on ultra-premium, historic Maisons
• Pernod Ricard - Strong Challenger; G.H. MUMM, Perrier-Jouet; major player in the European wine and spirits market, acting as one of the largest producers with a comprehensive portfolio of premium brands
• E. & J. Gallo Winery - Market Leader; BAREFOOT, ALAMOS, ANDRE, BLACK BOX, DARK HORSE; massive importer and distributor in Europe, bridging California wines with European consumers
• Constellation Brands, Inc. - Strong Challenger; Kim Crawford, Mount Veeder Winery; major international producer and premium marketer with key strategic footprints in Europe
• Treasury Wine Estates Ltd - Strong Challenger; Penfolds, Matua, 19 Crimes, St Hubert's The Stag, Pepperjack; major premium wine player in Europe, importing and distributing New World brands
Browse Full Report with TOC & List of Figures for In Depth Market Insights:
https://www.imarcgroup.com/europe-wine-market
Porter's Five Forces Analysis - Europe Wine Market
Competitive Rivalry: Moderate to High. The European wine market's competitive landscape is highly fragmented at the production tier but increasingly concentrated at the premium and luxury tier, where Champagne and fine wine estate portfolios command a disproportionate share of fine wine consumer spending. Cross-continental ownership changes are creating hybrid marketing approaches that leverage European authenticity with wine marketing investment infrastructure. Business implication: Producers must differentiate through heritage branding, premium positioning, and direct-to-consumer channel development to capture and retain market share.
Supplier Power (Vineyards and Grape Growers): Moderate. Suppliers of grapes, vineyard inputs, and wine production materials hold moderate influence. The appellation system creates legally protected production zones that sustain hundreds of independent producers whose wines are non-substitutable for each other in a strict sense. Climate change is affecting grape quality, harvest timing, and yield consistency, creating supply-side uncertainty. Business implication: Producers must invest in sustainable vineyard practices and climate-resilient cultivation to manage supply risk and ensure quality consistency.
Buyer Power (Consumers and Retailers): Moderate to High. Consumers have extensive access to wine through multiple retail channels, including off-trade and on-trade. E-commerce platforms and direct-to-consumer channels give buyers significant choice and price transparency. However, brand loyalty, appellation prestige, and provenance remain critical factors that moderate pure price-based purchasing pressure. Business implication: Producers must maintain brand equity, appellation credentials, and provenance transparency to justify pricing and build customer loyalty.
Threat of Substitutes: Moderate. Direct substitutes for wine include beer, spirits, and low/no-alcohol alternatives. The moderation and low/no-alcohol movement is limiting Europe's wine market as younger consumers increasingly reduce drinking frequency or shift toward lighter alternatives. Health awareness, wellness lifestyles and changing social habits are weakening traditional wine consumption occasions. Business implication: Producers must adapt through low-alcohol wines, smaller formats and lifestyle-focused branding to defend against substitution.
Threat of New Entrants: Moderate. Significant capital requirements for vineyard acquisition, wine production, and brand establishment create meaningful entry barriers. The appellation system creates legally protected production zones that limit new entrant access to premium designations. However, the growing market, e-commerce proliferation, and emerging wine regions offer opportunities for specialised entrants. Business implication: Niche and innovation-focused entrants can access the growing market by focusing on natural wine, low-alcohol categories, or emerging wine regions.
Regional Analysis
The Europe wine market exhibits distinct regional dynamics, with France commanding the largest share at 24.8% in 2025, followed by Italy at 21.6%, Germany at 18.3%, the United Kingdom at 14.7%, Spain at 12.1%, and others at 8.5%.
France (24.8%): France dominates due to its strong wine heritage, premium vineyard regions, and reputation for high-quality wines. Strong domestic consumption, exports, wine tourism, and established appellation systems further support its leading market position. France's commercial leadership is reinforced by Champagne's exceptional premium pricing concentration.
Italy (21.6%): Italy's volume production leadership, combined with annual bottle production and prestige, creates the most commercially diverse European wine value creation model. Supported by large-scale wine production, diverse wine regions, strong domestic consumption and export-oriented wineries.
Germany (18.3%): Germany's dual role as consumer and producer creates a distinct market structure where domestic prestige coexists with industrial history. Germany benefits from growing demand for premium, organic and low-alcohol wines, supported by strong retail and wine import activity.
United Kingdom (14.7%): The UK's fine wine trading infrastructure sustains its market share above domestic production, making London uniquely the world's fine wine commercial capital despite minimal wine production. Driven by high wine consumption, premiumization trends, expanding sparkling wine production and strong off-trade channels.
Spain (12.1%): Spain's growing premium wine recognition sustains Spain's above-GDP wine market value growth. Supported by extensive vineyard areas, wine exports, tourism-driven consumption and growing premium wine demand.
Others (8.5%): Other European countries contribute through emerging wine regions, specialty wines, wine tourism and niche premium offerings, representing Europe's most commercially dynamic emerging premium wine value creation opportunities.
Key Aspects Required for the Europe Wine Market
• Demand spans multiple product categories: Still wine, sparkling wine, and fortified wine/vermouth all contribute to the diversified demand base. Still wine leads with 68.4% share in 2025.
• Strong premiumization tailwinds: Premium and luxury wine premiumization demand is boosting as consumers increasingly prefer high-quality, heritage-led and origin-certified wines.
• E-commerce is transforming distribution: E-commerce and direct-to-consumer wine channels are making wine discovery, comparison and purchasing more convenient for consumers, with D2C models allowing producers to build stronger customer relationships.
• Wine tourism is driving experiential consumption: France, Italy and Spain lead Europe's wine tourism market, turning wine consumption into an experiential activity linked to vineyard visits, tastings, festivals and regional food culture.
• Low/no-alcohol wine is the fastest-growing category: Low and no-alcohol wine category development offers significant opportunity by addressing the growing health-conscious and moderation-focused consumer base.
• Climate change is reshaping the wine landscape: Climate change is enabling new wine-producing areas, including English sparkling wine regions and emerging viticulture zones across parts of Northern and Central Europe.
• Positive market outlook: The market is projected to grow from USD 81.7 Billion in 2025 to USD 116.9 Billion by 2034 at a CAGR of 4.06%, with an anchor value of USD 99.7 Billion by 2030.
Recent Industry Developments
• April 2026: Puklavec Family Wines partnered with Vaider and JRE-Jeunes Restaurateurs to launch Trois Femmes wine, combining its long winemaking heritage with modern, lower-carbon packaging. The project uses Vaider's carbon-neutral wine bottle, helping lower the product's overall environmental footprint.
• October 2025: A new dealcoholization facility by Solos opened in Valencia, Spain, giving premium wine producers in Southern Europe access to advanced technology for no- and low-alcohol wine production. The plant will help wineries reduce alcohol content while preserving flavor quality and premium brand positioning.
• October 2024: Moët Hennessy, LVMH's Wines and Spirits division, made a strategic minority investment in French Bloom, a leading prestige alcohol-free sparkling wine brand. The partnership highlights both companies' ambition to shape the future of premium non-alcoholic sparkling wines.
Report Format, Delivery, and Customization Details
• Report Format Mode: PPT, PDF, and Excel
• Report Delivery Mode: Online Delivery, Physical Delivery
• Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
• Report Confirmation Mode: Yes via Email
• Report Customization Mode: Yes via Email / Call
• Report Table of Content: Yes
• Report List of Figures: Yes
• Report Methodology Mode: Yes
• Request For Sample Report: Yes
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
https://www.imarcgroup.com/request?type=report&id=9435&flag=E
Other reports by IMARC Group
Europe Watch Market https://www.imarcgroup.com/europe-watch-market
Europe Wax Market https://www.imarcgroup.com/europe-wax-market
Contact Us
IMARC Group
134 N 4th St., Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-631-791-1145
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Europe Wine Market 2026 | Worth USD 116.9 Billion by 2034 here
News-ID: 4649334 • Views: …
More Releases from IMARC Group
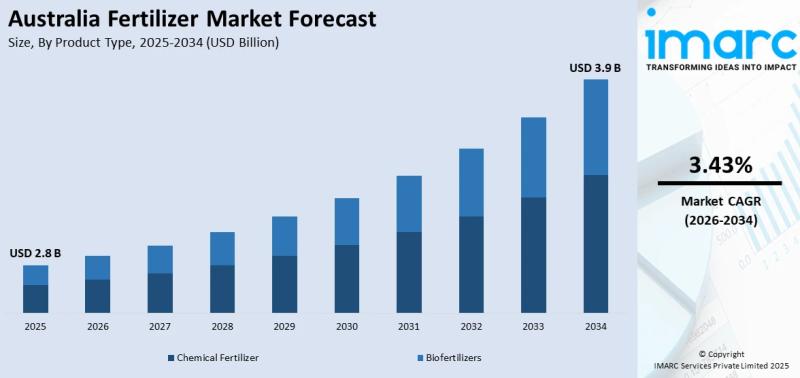
Australia Fertilizer Market 2026 | Worth USD 3.9 Billion by 2034
Market Overview
The Australia fertilizer market is experiencing steady growth, driven by increasing preferences among farmers across the country towards organic product variants that promote soil health and minimize ecological impact. According to IMARC Group, the market size increased from USD 2.8 Billion in 2025 to USD 2.9 Billion in 2026 and is projected to reach USD 3.9 Billion by 2034, exhibiting a growth rate (CAGR) of 3.43% during 2026-2034.
Fertilizer is…
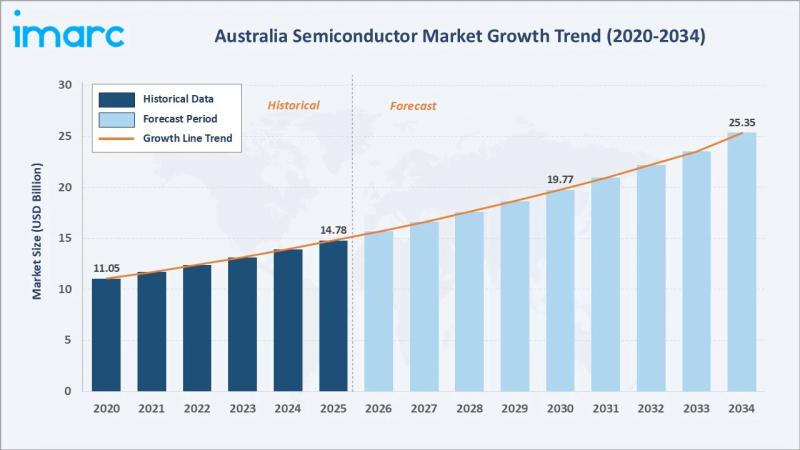
Australia Semiconductor Market 2026 | Worth USD 25.35 Billion by 2034
Market Overview
The Australia semiconductor market is experiencing strong growth, driven by strong government incentives, rising IoT and consumer electronics demand, proximity to Asia-Pacific supply chains, and cross-sector innovation culture. According to IMARC Group, the market size increased from USD 14.78 Billion in 2025 to USD 15.92 Billion in 2026 and is projected to reach USD 25.35 Billion by 2034, exhibiting a CAGR of 5.99% during 2026-2034.
Semiconductors underpin Australia's defence, telecommunications,…
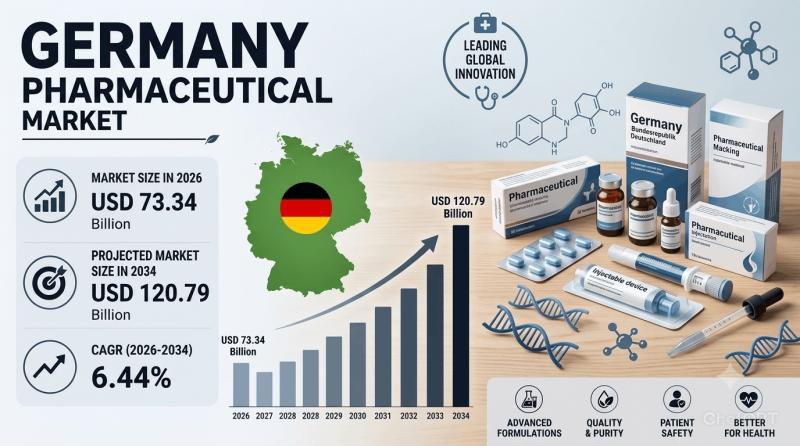
Germany Pharmaceutical Market Size to Reach USD 120.79 Billion by 2034 at 6.44% …
The Germany pharmaceutical market is experiencing robust growth, driven by a high burden of chronic diseases, an aging population, strong R&D investment, and universal health insurance coverage. The market size increased from USD 68.91 Billion in 2025 to USD 73.34 Billion in 2026 and is projected to reach USD 120.79 Billion by 2034, exhibiting a robust CAGR of 6.44% during 2026-2034. In 2024, 53.7% of adults in Germany were living…
Brazil Freight and Logistics Market Size to Reach USD 162.03 Billion by 2034, Gr …
Brazil Freight and Logistics Market Report 2026
Market Size in 2025: USD 110.26 Billion
Market Size in 2026: USD 115.08 Billion
Market Forecast in 2034: USD 162.03 Billion
Market Growth Rate: 4.37% (2026-2034)
According to the latest report by IMARC Group, titled "Brazil Freight and Logistics Market: Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034," the Brazil freight and logistics market grew from USD 110.26 Billion in 2025 to USD 115.08 Billion in 2026.…
More Releases for Europe
2019 Strategy Consulting Market Analysis | McKinsey, The Boston Consulting Group …
Strategy Consulting Market reports also offer important insights which help the industry experts, product managers, CEOs, and business executives to draft their policies on various parameters including expansion, acquisition, and new product launch as well as analyzing and understanding the market trends
Need for strategic planning in highly competitive environment and to develop business capabilities to meet & exceed the emerging requirements are the major drivers which help in surging…
Strategy Consulting Market 2025 | Analysis By Top Key Players: Booz & Co. , Rola …
Global Strategy Consulting Market 2019-2025, has been prepared based on an in-depth market analysis with inputs from industry experts. This report covers the market landscape and its growth prospects over the coming years. The report also includes a discussion of the key vendors operating in this market.
The key players covered in this study
McKinsey , The Boston Consulting Group , Bain & Company , Booz & Co. , Roland Berger Europe…
Digital Strategy Consulting Market is Thriving Worldwide with Deloitte, McKinsey …
A Digital Strategy is a form of strategic management and a business answer or response to a digital question, often best addressed as part of an overall business strategy. A digital strategy is often characterized by the application of new technologies to existing business activity and focus on the enablement of new digital capabilities to their business.
A new report as a Digital Strategy Consulting market that includes a comprehensive analysis…
Strategy Consulting Market 2019: By McKinsey, The Boston Consulting Group, Bain …
This report studies the global Strategy Consulting market, analyzes and researches the Strategy Consulting development status and forecast in United States, EU, Japan, China, India and Southeast Asia. This report focuses on the top players in global market, like
• McKinsey
• The Boston Consulting Group
• Bain & Company
• Booz & Co.
• Roland Berger Europe
• Oliver Wyman Europe
• A.T. Kearney Europe
• Deloitte
• Accenture Europe
Get Sample Report@ https://www.reporthive.com/enquiry.php?id=1247388&req_type=smpl&utm_source=AB
Market segment by Type, the product can be split into
• Operations Consultants
• Business Strategy Consultants
• Investment Consultants
• Sales and…
Strategy Consulting Market Analysis 2018: McKinsey, The Boston Consulting Group, …
Orbis Research Present’s “Global Strategy Consulting Market” magnify the decision making potentiality and helps to create an effective counter strategies to gain competitive advantage.
The global Strategy Consulting status, future forecast, growth opportunity, key market and key players. The study objectives are to present the Strategy Consulting development in United States, Europe and China.
In 2017, the global Strategy Consulting market size was million US$ and it is expected to reach million…
Influenza Vaccination Market Global Forecast 2018-25 Estimated with Top Key Play …
UpMarketResearch published an exclusive report on “Influenza Vaccination market” delivering key insights and providing a competitive advantage to clients through a detailed report. The report contains 115 pages which highly exhibits on current market analysis scenario, upcoming as well as future opportunities, revenue growth, pricing and profitability. This report focuses on the Influenza Vaccination market, especially in North America, Europe and Asia-Pacific, South America, Middle East and Africa. This…

