
Press release
Atomic Layer Deposition Equipment (ALD) Market 2026 : Production Capacity of 2,800 Units, Equipment Pricing, Manufacturing Economics & Business Opportunities
Atomic Layer Deposition Equipment (ALD) Market
Request for a Sample Report - Includes Full TOC, Market Forecasts, Company Profiles, Tables & Charts : https://qyresearch.in/request-sample/machinery-equipment-global-atomic-layer-deposition-equipment-ald-market-insights-industry-share-sales-projections-and-demand-outlook-2026-2032
Semiconductor manufacturers, display producers, photovoltaic companies and advanced materials developers are facing growing pressure to produce increasingly complex structures while controlling film thickness, interface quality, uniformity and material properties at extremely small dimensions. Conventional deposition methods may struggle when devices require highly conformal coatings on three-dimensional or high-aspect-ratio structures, particularly as semiconductor processes advance toward 5nm, 3nm and even smaller technology nodes. Atomic Layer Deposition Equipment addresses this challenge by enabling sequential, self-limiting surface reactions that deposit materials one atomic layer at a time, offering exceptional thickness control and conformity.
Market Overview
Atomic Layer Deposition Equipment is a specialized thin-film deposition platform used for thermal ALD, plasma-enhanced ALD and other atomic-scale deposition processes. ALD is a subclass of chemical vapor deposition in which two or more precursor chemicals are introduced sequentially and react with a surface in a self-limiting manner, allowing extremely precise control of film thickness and composition. The process is particularly suitable for applications requiring ultra-thin, highly uniform and conformal films on complex structures. In semiconductor manufacturing, ALD is used for high-k gate dielectrics, interface layers, barriers, liners and advanced metal filling, while in displays, photovoltaics, batteries and MEMS, it supports passivation, encapsulation, functional coatings and nanostructured materials. As device architectures become more complex, ALD is emerging as one of the most technologically advanced and strategically important thin-film deposition technologies.
Why This Market Matters
The Atomic Layer Deposition Equipment Market matters because modern electronics increasingly depend on atomic-scale control over material interfaces and thin-film structures. In semiconductor manufacturing, small deviations in film thickness or composition can affect transistor performance, leakage, reliability and yield, making deposition precision increasingly important as device geometries shrink. In advanced packaging and memory devices, ALD enables conformal coatings inside deep trenches and high-aspect-ratio structures that are difficult to address using conventional deposition. In displays, solar cells, batteries and MEMS, the technology helps improve performance, protection, efficiency and service life. For manufacturers, ALD equipment represents a high-value process tool; for investors, the market provides exposure to advanced semiconductor manufacturing and nanotechnology; and for downstream users, ALD supports the development of smaller, faster, more efficient and more reliable devices.
Why Companies Are Investing in Underwater Surveillance Systems
Underwater surveillance systems are not identified as a direct downstream application within the supplied Atomic Layer Deposition Equipment Market information. However, ALD technology can support broader advanced electronics, sensors, MEMS devices, protective coatings and high-performance materials used across specialized industrial or defense systems. The directly supported applications in the supplied market information remain scientific research, power and compound semiconductors, integrated circuits, display manufacturing, photovoltaics, battery-related coatings and MEMS. Therefore, the investment case for ALD equipment should primarily be linked to advanced manufacturing, high-precision thin films and next-generation electronic devices rather than underwater surveillance specifically.
Industry Challenges
The ALD equipment industry faces significant technological and manufacturing challenges because system performance depends on precise control of precursor delivery, temperature stability, vacuum conditions, gas isolation, chamber design, plasma coupling and reaction timing. Equipment must achieve highly uniform films while minimizing contamination and ensuring repeatable performance across wafers, batches or large-area substrates. Different materials also require different precursor chemistries and process windows, increasing R&D complexity. High equipment cost and process-development requirements can limit adoption in price-sensitive applications, while customers in semiconductor manufacturing demand extremely high reliability, uptime and process consistency. Suppliers must therefore combine hardware engineering, chemistry expertise, software control and application-specific process integration to remain competitive.
Technology Solutions
Technology development in the ALD market is focused on improving deposition speed, film uniformity, precursor utilization, plasma performance, chamber productivity and compatibility with increasingly complex device structures. Thermal ALD remains important for highly controlled surface reactions, while PEALD uses plasma energy to enable lower-temperature processing or enhance film properties. Batch ALD improves throughput for applications such as DRAM, NAND and photovoltaics, while Spatial ALD increases deposition speed by separating precursor zones spatially rather than temporally and is particularly suitable for display and large-area applications. Manufacturers are also improving gas-path design, reaction chamber geometry, thermal-field control and software algorithms to increase uniformity and process repeatability. These advances are enabling ALD to expand from specialized applications into broader high-volume manufacturing.
Market Driving Growth and Restraint
The strongest market driver is the continued advancement of semiconductor process technology toward smaller geometries and increasingly complex three-dimensional structures. As chip manufacturers move toward 5nm, 3nm and even smaller nodes, ALD becomes increasingly important for high-k dielectrics, interface layers, metal barriers and conformal films. Growth in 3D NAND and DRAM also increases demand because high-aspect-ratio structures require uniform deposition throughout deep features. Beyond semiconductors, OLED, Micro-LED, photovoltaic, battery, MEMS and nanotechnology applications provide additional growth opportunities. However, market expansion can be restrained by high equipment costs, expensive precursor materials, complex process development and long customer qualification cycles. Adoption also depends on whether ALD provides sufficient performance advantages compared with competing deposition technologies
Emerging Trends & Dynamics
The ALD equipment market is evolving toward higher throughput, greater automation, more advanced plasma technologies and broader application diversity. One of the most important trends is the increasing use of ALD in advanced logic and memory, especially as high-aspect-ratio structures and new materials become more common. Spatial ALD is gaining attention in large-area manufacturing and display applications, while batch processing remains important for high-volume wafer production. Another trend is the expansion of ALD into batteries, where ultra-thin coatings can improve electrode stability and cycle life, as well as into photovoltaics, where passivation layers help improve solar-cell efficiency. The technology is also becoming increasingly important in nanotechnology research, where atomic-level material control enables new catalysts, sensors and functional nanostructures
Market Challenges
A major challenge in the Atomic Layer Deposition Equipment Market is balancing atomic-level precision with production throughput. Traditional ALD is inherently sequential and can be slower than some other deposition technologies, which creates productivity concerns in high-volume manufacturing. Equipment suppliers are therefore investing in batch architectures, spatial processing and faster precursor switching to improve throughput without sacrificing film quality. Another challenge is the availability and cost of suitable precursor chemicals, especially for newer metals or specialty materials. Process contamination, precursor stability and by-product management also require careful engineering. In semiconductor applications, the qualification process can be lengthy because customers need strong evidence of uniformity, reliability, particle control and integration compatibility before introducing new ALD platforms into production.
Key Business Opportunities
The strongest business opportunities are expected in advanced logic, memory, compound semiconductors, OLED and Micro-LED displays, photovoltaics, batteries, MEMS and research applications. Advanced logic offers significant opportunity because gate-all-around structures and increasingly complex transistor architectures require conformal thin films with tight atomic-level control. DRAM and 3D NAND create demand for dielectric and conductive layers inside extremely deep structures, while compound semiconductors benefit from high-quality interface engineering. Display manufacturers can use ALD for barrier and functional layers, solar manufacturers for Al2O3 passivation, and battery developers for electrode and separator coatings. Additional opportunities exist in scientific research and emerging nanotechnology applications where material properties must be precisely engineered at the nanoscale.
Market Segmentation
The global Atomic Layer Deposition Equipment Market is segmented by technology type and application. By type, the market includes Thermal ALD, PE-ALD, Spatial ALD and Others, with each platform addressing different process conditions, temperature requirements, throughput demands and substrate geometries. By application, the market includes Scientific Research, Power/Compound Semiconductors, Integrated Circuits, Display Industry, Photovoltaics and Others. Integrated circuits represent one of the most strategically important applications because ALD is critical for advanced semiconductor structures, while power and compound semiconductors are creating additional opportunities as GaN, SiC and other materials gain broader use. Display, photovoltaic and research applications further diversify the market and reduce dependence on a single downstream industry.
Regional Market Insights
North America represents an important market supported by advanced semiconductor R&D, equipment development and nanotechnology research. Europe maintains strong capabilities in semiconductor equipment, vacuum technology, precision components and scientific instrumentation. Asia-Pacific is one of the most important regions because China, Japan, South Korea, Southeast Asia and other markets host significant semiconductor, display and photovoltaic manufacturing capacity. Japan and South Korea have advanced semiconductor and display ecosystems, while China continues to expand domestic semiconductor equipment and advanced manufacturing capacity. Southeast Asia and India are also gaining attention as semiconductor investment expands. Regional demand is closely linked to wafer fab construction, memory investment, display production, photovoltaic capacity and local equipment development initiatives.
Regions Covered
The Global Atomic Layer Deposition Equipment Market Report covers North America, including the United States, Canada and Mexico; Europe, including Germany, France, the United Kingdom, Italy and other European markets; Asia Pacific, including China, Japan, South Korea, Southeast Asia, India and other regional economies; South America, including Brazil and other markets; and the Middle East and Africa, including Turkey, GCC Countries, Africa and other developing markets. Regional analysis evaluates semiconductor manufacturing capacity, technology investment, equipment demand, display and photovoltaic expansion, research activity and competitive positioning across each major geography.
Competitive Landscape - Key Players Are Investing In
Competition in the Atomic Layer Deposition Equipment Market is centered on process performance, thin-film uniformity, chamber productivity, precursor efficiency, plasma capability and customer qualification. Major global suppliers include companies with deep experience in semiconductor manufacturing equipment, while specialized ALD companies compete through advanced process platforms and niche applications. Leading manufacturers are investing in Thermal ALD, PEALD, batch systems, Spatial ALD, chamber architecture, precursor management and process-control software. As semiconductor structures become more complex, suppliers with strong process libraries, customer support and system integration capabilities are likely to gain greater competitive advantage. Regional manufacturers are also expanding, particularly in Asia, as local semiconductor equipment ecosystems continue to develop.
Major Global Manufacturers Include
ASM International
Tokyo Electron
Lam Research
Applied Materials
Eugenus
Veeco
Picosun
SRI Intellectual Technology Co.
Leadmicro
Ideal Deposition
NAURA
Oxford Instruments
Songyu Technology
Forge Nano
Solaytec
NCD
CN1
Wonik IPS
Jusung
Samco
ULVAC
Arradiance
SENTECH Instruments
SVT Associates
Piotech
ANAME
Superald, LLC
Nexusbe
Swiss Cluster
MNT Technology
Shenyang Piotech
Shenzhen Nashe Intelligent Equipment Co., Ltd.
These companies represent major participants identified in the supplied market information. Competitive positioning varies according to ALD technology route, chamber design, semiconductor process integration, application focus, throughput, regional customer base and manufacturing scale.
Industry Chain Analysis
The Atomic Layer Deposition Equipment industry chain includes precursor chemicals, core components, equipment manufacturers and downstream applications. The upstream segment includes metal-organic precursors such as TMA, TDMAT, HCDS and Ru-, Co- and W-based precursors, together with rare gases, high-purity carrier gases, mass flow controllers, vacuum pumps, ALD-specific valves, plasma sources, evaporators, heating platforms, temperature-control systems, quartz or SiC reaction chambers and high-purity piping, with suppliers including Entegris, CKD, VAT, Edwards, Pfeiffer, MKS and Horiba. The midstream segment consists of ALD equipment manufacturers responsible for chamber design, precursor pulse control, gas-path isolation, thermal uniformity, plasma coupling and film-uniformity algorithms. The downstream market includes front-end semiconductor manufacturing, back-end metallization, 3D NAND, DRAM, OLED, Micro-LED, photovoltaics, batteries, MEMS and scientific research, making ALD an increasingly important equipment category across multiple high-tech value chains.
Market Entry Opportunities for New Companies and Investors:-
Companies considering entry into the Atomic Layer Deposition Equipment (ALD) market must evaluate customer requirements, competitive conditions, business regulations, supplier availability, pricing structures, and the resources required to establish operations. Potential opportunities may exist in specialized customer segments, differentiated offerings, alternative service models, or geographic markets where an entrant can deliver relevant commercial value. New manufacturers and service providers should assess operating requirements, investment costs, quality expectations, and prospective customer relationships before committing resources. Distribution businesses may focus on sourcing arrangements, customer access, and commercial positioning, while investors may investigate market structure and competitive barriers. A structured market-entry assessment can help businesses identify relevant risks, compare strategic alternatives, and develop plans aligned with their capabilities.
Why Companies Need the Global Atomic Layer Deposition Equipment (ALD) Market Research Report:-
Businesses evaluating the Atomic Layer Deposition Equipment (ALD) industry require information that helps connect market developments with practical purchasing, investment, and strategic planning decisions. Manufacturers may need to examine product differentiation, customer needs, competing companies, and expansion opportunities, while suppliers and distributors may focus on commercial relationships, pricing, and sourcing requirements. Enterprise buyers may seek information about available offerings and supplier capabilities, while investors may evaluate market structure, competitive positioning, and business risks. QY Research's Global Atomic Layer Deposition Equipment (ALD) Market analysis provides a framework for investigating industry conditions, competitive intelligence, commercial considerations, and potential strategic opportunities. The objective is to help organizations identify relevant questions, evaluate market alternatives, and improve decision-making based on their individual business requirements.
Purchase the Full Report or Customize It to Match Your Business Requirements : https://qyresearch.in/pre-order-inquiry/machinery-equipment-global-atomic-layer-deposition-equipment-ald-market-insights-industry-share-sales-projections-and-demand-outlook-2026-2032
Market Troubles & QY Solutions
Companies participating in the ALD equipment market face several strategic questions: Which technology route offers the strongest growth potential? Which applications will generate the highest equipment demand? How quickly will 3nm and below processes increase ALD intensity? Which equipment manufacturers have the strongest process capability? How will display, photovoltaic and battery applications affect future demand? QY Research helps address these questions through market sizing, competitor benchmarking, technology-route analysis, application studies, supply-chain assessment, regional demand analysis and customized research. The objective is to help equipment suppliers, investors, component manufacturers and downstream users identify growth opportunities, reduce investment risk, understand competitive positioning and improve strategic decision-making.
Who Should Buy This Report?
The Global Atomic Layer Deposition Equipment Market Report 2026-2032 is designed for semiconductor equipment manufacturers, wafer fabs, foundries, integrated device manufacturers, display companies, photovoltaic manufacturers, battery developers, precursor suppliers, vacuum component suppliers, institutional investors, consultants and market researchers. Equipment manufacturers can use the report to evaluate technology trends and competitor positioning, while semiconductor companies can assess equipment supply and process development. Investors can evaluate exposure to advanced semiconductor manufacturing and nanotechnology, upstream suppliers can identify opportunities in precursor chemicals and precision components, and business development teams can examine demand across integrated circuits, power semiconductors, displays, photovoltaics and emerging applications.
Frequently Asked Questions and Answers
Q1. What is the global Atomic Layer Deposition Equipment Market size?
The global market was valued at approximately US$ 4,674 million in 2025 and is anticipated to reach approximately US$ 9,037 million by 2032.
Q2. What is the expected CAGR during 2026-2032?
The market is projected to grow at approximately 9.7%.
Q3. What was global ALD equipment production in 2025?
Global production reached approximately 2,244 units against production capacity of around 2,800 units.
Q4. What was the average equipment price?
The supplied market information indicates an average global market price of approximately US$ 2 million per unit in 2025.
Q5. What are typical industry gross margins?
Gross margins are mainly in the range of approximately 35%-45%.
Q6. What are the main ALD technology types?
Major types include Thermal ALD, PE-ALD, Spatial ALD and other architectures.
Q7. What are the main applications?
Major applications include scientific research, power and compound semiconductors, integrated circuits, displays, photovoltaics and other advanced manufacturing applications.
Q8. Why is ALD important in advanced semiconductor manufacturing?
ALD provides atomic-level film-thickness control and highly conformal coatings on complex and high-aspect-ratio device structures.
Q9. What technologies are driving future demand?
Advanced logic, 3D NAND, DRAM, OLED, Micro-LED, photovoltaics, batteries, MEMS and nanotechnology are important demand areas.
Q10. What are the major market challenges?
Important challenges include equipment cost, precursor complexity, deposition speed, process qualification and the need to maintain film uniformity and high throughput.
About Us:
QYResearch founded in California, USA in 2007, which is a leading global market research and consulting company. Our primary business include market research reports, custom reports, commissioned research, IPO consultancy, business plans, etc. With over 19 years of experience and a dedicated research team, we are well placed to provide useful information and data for your business, and we have established offices in 7 countries (include United States, Germany, Switzerland, Japan, Korea, China and India) and business partners in over 30 countries. We have provided industrial information services to more than 60,000 companies in over the world.
Contact Us:
Arshad Shaha | Marketing Executive
QY Research, INC.
315 Work Avenue, Raheja Woods,
Survey No. 222/1, Plot No. 25, 6th Floor,
Kayani Nagar, Yervada, Pune 411006, Maharashtra
Tel: +91-8669986909
Emails - arshad@qyrindia.com
Web - https://www.qyresearch.in
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Atomic Layer Deposition Equipment (ALD) Market 2026 : Production Capacity of 2,800 Units, Equipment Pricing, Manufacturing Economics & Business Opportunities here
News-ID: 4675097 • Views: …
More Releases from QYResearch.Inc
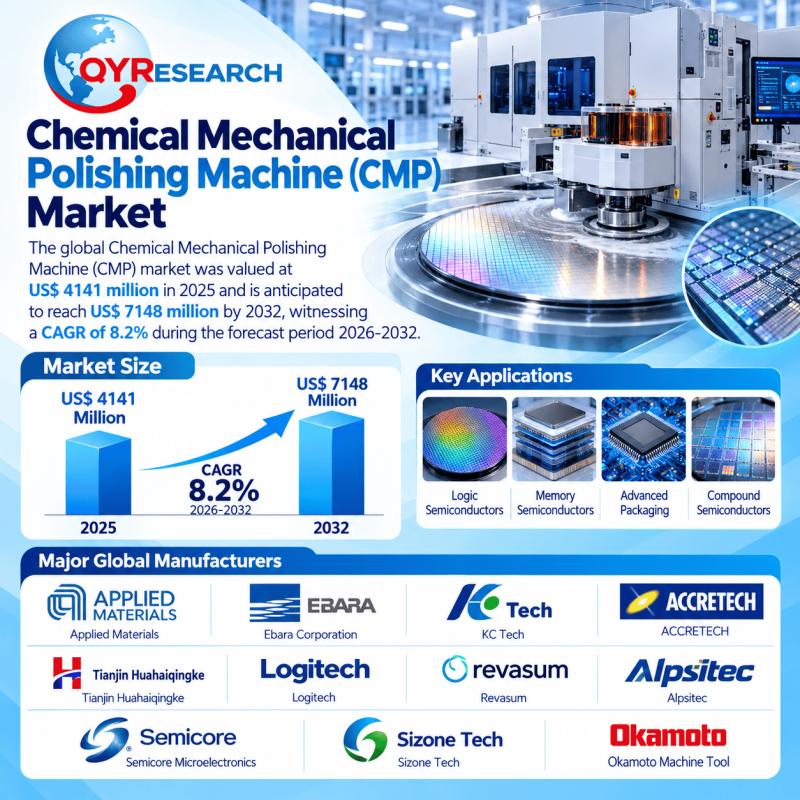
Chemical Mechanical Polishing Machine (CMP) Market Size to Reach $7,148 Million …
According to QY Research has released its latest industry-focused analysis titled Global Chemical Mechanical Polishing Machine (CMP) Market Insights - Industry Share, Sales Projections, and Demand Outlook 2026-2032. The study provides a structured perspective on changing market conditions, competitive developments, business opportunities, and factors influencing purchasing and investment decisions. As companies continue to evaluate opportunities for improving operational performance, strengthening supplier relationships, managing costs, and expanding into new markets, reliable…
High Purity Cleaning and Etching Gases for Semiconductor Front-End Market to Gro …
According to QY Research has released its latest industry-focused analysis titled Global High Purity Cleaning and Etching Gases for Semiconductor Front-End Market Insights - Industry Share, Sales Projections, and Demand Outlook 2026-2032. The study provides a structured perspective on changing market conditions, competitive developments, business opportunities, and factors influencing purchasing and investment decisions. As companies continue to evaluate opportunities for improving operational performance, strengthening supplier relationships, managing costs, and expanding…
Plasma Etching Equipment Market : Semiconductor Manufacturing Investment, Equipm …
According to QY Research has released its latest industry-focused analysis titled Global Plasma Etching Equipment Market Insights - Industry Share, Sales Projections, and Demand Outlook 2026-2032. The study provides a structured perspective on changing market conditions, competitive developments, business opportunities, and factors influencing purchasing and investment decisions. As companies continue to evaluate opportunities for improving operational performance, strengthening supplier relationships, managing costs, and expanding into new markets, reliable industry intelligence…
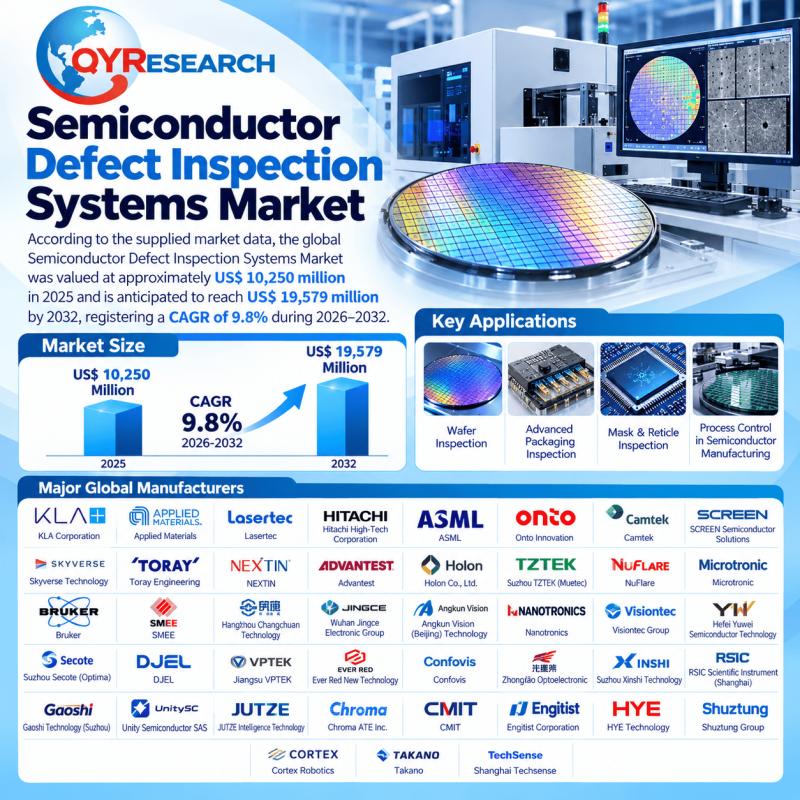
Semiconductor Defect Inspection Systems Market to Reach USD 19.58 Billion by 203 …
According to QY Research has released its latest industry-focused analysis titled Global Semiconductor Defect Inspection Systems Market Insights - Industry Share, Sales Projections, and Demand Outlook 2026-2032. The study provides a structured perspective on changing market conditions, competitive developments, business opportunities, and factors influencing purchasing and investment decisions. As companies continue to evaluate opportunities for improving operational performance, strengthening supplier relationships, managing costs, and expanding into new markets, reliable industry…
More Releases for ALD
Adrenoleukodystrophy (ALD) Market Opportunities in 2034
Market Overview
The Adrenoleukodystrophy (ALD) Market is growing steadily as improvements in newborn screening, genetic diagnostics, and awareness of rare neurodegenerative disorders lead to earlier detection and clinical intervention.
ALD is a genetically inherited X-linked disorder caused by mutations in the ABCD1 gene, leading to the toxic accumulation of very long-chain fatty acids (VLCFAs) in the brain, adrenal glands, and spinal cord. The condition manifests in multiple forms, including childhood cerebral…
Technological Advances Propel Growth In The Ald Equipment Market Industry Trends …
Stay ahead with our updated market reports featuring the latest on tariffs, trade flows, and supply chain transformations.
ALD Equipment Market Size Valuation Forecast: What Will the Market Be Worth by 2025?
There has been a significant expansion in the ALD equipment market size in the past few years. The market is predicted to rise from $3.41 billion in 2024 to $3.7 billion in 2025, indicating a compound annual growth rate (CAGR)…
Surge In Electronics And Semiconductor Sector Propels Ald Equipment Market: Key …
The ALD Equipment Market Report by The Business Research Company delivers a detailed market assessment, covering size projections from 2025 to 2034. This report explores crucial market trends, major drivers and market segmentation by [key segment categories].
What Is the Expected ALD Equipment Market Size During the Forecast Period?
The market size for ALD equipment has significantly expanded in the last few years, poised to rise from $3.41 billion in 2024 to…
Primary Catalyst Driving ALD Equipment Market Evolution in 2025: Surge In Electr …
What combination of drivers is leading to accelerated growth in the ald equipment market?
Anticipations of a surge in the electronics and semiconductor industry are set to boost the ALD equipment market. The realm of electronics includes firms that engineer, produce, and distribute devices such as radios, televisions, music systems, computers, semiconductors, transistors, integrated circuits, etc. ALD equipment finds its use in these industries to fabricate substrates for microelectronics and nanotechnology.…
Atomic Layer Deposition Market May See a Big Move|ALD Vacuum Technologies, ALD N …
A Latest intelligence report published by Pro Market Reports with title "Global Atomic Layer Deposition Market Outlook to 2032". A detailed study accumulated to offer Latest insights about acute features of the Atomic Layer Deposition market. This report provides a detailed overview of key factors in the Global Atomic Layer Deposition Market and factors such as driver, restraint, past and current trends, regulatory scenarios and technology development. Some of the…