
Press release
Luxury Cosmetics Market Growth Drivers, Premium Beauty Trends and Industry Forecast 2026-2034
Luxury Cosmetics Market
The market is experiencing strong growth momentum as rising disposable incomes, heritage brand equity, and a shift toward science-backed, experience-led premium beauty converge. Even when economic conditions tighten, the lipstick effect keeps shoppers trading up to small luxuries, so prestige lipsticks, serums, and fragrances tend to hold up when larger discretionary purchases are deferred. Heritage houses in France, Italy, and the United Kingdom anchor global supply through deep research and development infrastructure. Fashion and leather goods maisons are increasingly extending their brand equity into beauty through licensing and acquisition. Meanwhile, virtual try-on, AI skin analysis, and personalized loyalty programs are blurring the line between online convenience and in-store consultation. Asia Pacific, the Middle East, and India are adding affluent consumers who are trading up from masstige to prestige, which broadens demand well beyond traditional Western markets.
Luxury Cosmetics Market at a Glance:
● Market Size 2025: USD 57.17 Billion
● Market Size 2026: USD 59.41 Billion
● Projected Market Size 2034: USD 80.83 Billion
● Growth Rate 2026-2034: CAGR of 3.92%
● Leading Product Type: Skincare, with a 37.8% share
● Leading Type: Conventional, with a 70.6% share
● Leading Distribution Channel: Specialty and Monobrand Stores, with a 46.5% share
● Dominant Region: Europe, with a 38.5% share, while Asia Pacific is the fastest growing region
How AI is Reshaping the Future of the Luxury Cosmetics Market
● AI Skin Diagnostics and Virtual Try-On at Global Scale: L'Oréal's ModiFace platform, which powers makeup try-on, hair colour simulation, and AI skin analysis across its brands, has delivered more than one billion virtual try-on sessions.
L'Oréal Paris has extended this foundation with Beauty Genius, an agentic AI beauty assistant available through WhatsApp in partnership with Meta. This combines diagnostic AI, generative conversation, and proactive guidance, and it turns a product search into a personalized consultation that prestige counters have traditionally delivered only in person.
● Generative AI Across Brand Operations and the Discovery Layer: The Estée Lauder Companies built an AI Innovation Lab with Microsoft on Azure OpenAI Service to serve more than 20 beauty brands. Its internal chatbot draws on a proprietary database of product and claim data so brands can launch locally relevant campaigns faster. L'Oréal has also announced that Maybelline virtual try-on will run inside ChatGPT, positioning the group inside the AI answer layer where beauty discovery is increasingly starting.
● AI-Assisted Bioscience and Formulation Research: L'Oréal has announced that OpenAI's GPT-Rosalind model will support skin microbiome research tied to future skincare development, starting with La Roche-Posay. This reflects a wider shift in which biotechnology-derived actives, fermentation, and microbiome science are moving luxury skincare closer to cosmeceuticals, and AI is shortening the path from ingredient discovery to clinically validated formulation.
Grab a sample PDF of this report: https://www.imarcgroup.com/luxury-cosmetics-market/requestsample
Luxury Cosmetics Market Trends and Drivers:
The global luxury cosmetics market is witnessing steady expansion, fueled by wealth creation at the top of the pyramid, structural shifts in how prestige brands sell and package their products, and rising consumer scrutiny of what goes into every formulation. Affluence is the foundational demand driver. Capgemini's World Wealth Report places the global high-net-worth population at 25.3 million individuals holding a record USD 98.3 trillion in wealth, with Asia Pacific posting the fastest regional wealth growth at 10.5%. This expanding base of affluent consumers supports both aspirational entry points and ultra-premium ranges. When Louis Vuitton launched its first lipstick at USD 160 with a USD 69 refill, it signalled how confidently the category is pricing small luxuries for a wealthier global customer.
Sustainability and trade integrity are the structural differentiators reshaping brand strategy. Refillable packaging has moved from a niche gesture to a core luxury design principle, and the price ladder between an heirloom case and a lower-cost refill rewards repeat purchase while reducing packaging waste per use. At the same time, the OECD and the EUIPO estimate counterfeit goods at around USD 467 billion in global trade, roughly 2.3% of global imports, and flag fake cosmetics among the hazardous product categories that threaten consumer safety. That risk strengthens the case for authenticated, brand-controlled channels such as specialty and monobrand stores and direct-to-consumer platforms, which already command the largest channel share. Trade policy is also opening new corridors, with the India and European Union free trade agreement set to phase out duties of up to 22% on cosmetics.
Clean beauty and ingredient transparency are the third driver, and they set up a rapidly tightening regulatory environment. Organic luxury cosmetics already account for 29.4% of the market by type, representing a segment value of approximately USD 16.8 Billion, as younger affluent consumers reward verified natural credentials and brands reformulate to meet stricter ingredient rules. The European Union has expanded its mandatory fragrance allergen labelling list from 26 to 82 substances, while in the United States the FDA now tracks 14,299 active cosmetic facility registrations under its modernized oversight framework. Brands that can reformulate, document, and certify across divergent regimes are positioned to convert compliance into a competitive advantage.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=5547&flag=E
Global Regulatory, Trade, and Sustainability Landscape Shaping Demand:
● ISO 22716 and ISO 16128 (International Organization for Standardization): ISO 22716 sets the internationally recognized good manufacturing practice guidelines for cosmetics, while ISO 16128 defines how natural and organic origin indexes are calculated. Together they give luxury brands a common technical language for manufacturing quality and for substantiating natural and organic claims across borders.
● EU Cosmetics Regulation, Fragrance Allergen Labelling: The amendment expands individually declarable fragrance allergens from 26 to 82 substances by adding 56 new entries, with disclosure required above 0.001% in leave-on products and 0.01% in rinse-off products. New products placed on the EU market must comply from 31 July, while products already on the market have a two-year sell-through window. This directly affects prestige fragrance and skincare houses.
● OECD and EUIPO, Counterfeit Trade Monitoring: The joint study estimates counterfeit trade at about USD 467 billion, equal to roughly 2.3% of global imports, and shows fake goods making up up to 4.7% of EU imports. Cosmetics are flagged as a hazardous counterfeit category, reinforcing the importance of authenticated distribution and customs cooperation for luxury brands.
● COSMOS Standard, Natural and Organic Certification: The COSMOS certification framework, cited by IMARC as a driver of organic adoption, gives luxury brands a harmonized third-party route to verify natural and organic claims across multiple regulatory regions. It supports premium pricing for organic ranges as consumer scrutiny of greenwashing increases.
Key Government Schemes and Policy Programs Supporting the Industry:
● India, India and European Union Free Trade Agreement: Concluded in January after nearly two decades of negotiation, the agreement phases out import duties on cosmetics of up to 22% over five or seven years. India will eliminate tariffs on 86% of tariff lines covering 93% of trade value, within bilateral goods trade of EUR 120 billion, of which EU exports to India are nearly EUR 49 billion. French and European luxury beauty houses are investing in India ahead of the duty cuts.
● United States, Modernization of Cosmetics Regulation Act (MoCRA): The law gave the FDA mandatory facility registration, product listing, adverse event reporting, and recall authority for cosmetics. As of early January, the FDA's system showed 14,299 unique active facility registrations and 992,907 unique active product listings, with facility registrations required to be renewed every two years. The final good manufacturing practice rule and fragrance allergen labelling rules remain pending.
● European Union, Packaging and Packaging Waste Regulation: This regulation applies directly across all 27 member states after an 18-month transition period, with its first requirements applying from 12 August, including a Declaration of Conformity and technical documentation for each packaging type. It sets the course toward fully recyclable packaging, recycled-content targets for plastics, and refill obligations, which makes refillable luxury formats a compliance advantage.
● China, NMPA Announcement No. 70 on Cosmetic Registration and Filing: Issued on 29 July, the announcement introduces optimization measures across eight dimensions, including encouraging international new products to launch first in China without proof of sale in the home market, and conditional exemptions from animal testing data for selected special cosmetics and general cosmetics using new ingredients. Separate new ingredient rules that took effect on 15 July narrowed the higher-risk registration scope from ten functions to five.
Luxury Cosmetics Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Product Type:
● Skincare
● Haircare
● Makeup
● Fragrances
Skincare leads the product type segment with a 37.8% share, followed by makeup at 27.4% and fragrances at 21.6%. Demand is driven by growing consumer focus on skin health, anti-aging regimens, hyaluronic acid-infused serums, and dermatologist-endorsed prestige formulations, supported by AI skin diagnostics that connect consumers to the right regimen. Makeup is sustained by celebrity-led and limited-edition collections, while fragrance is benefiting from a renaissance in niche and artisanal houses, particularly in the Middle East.
Breakup By Type:
● Organic
● Conventional
Conventional formulations account for the largest type share at 70.6%, anchored by decades of brand trust in proven actives such as retinoids, peptides, and alpha hydroxy acids that deliver clinically validated efficacy at premium price points. Organic luxury cosmetics hold the remaining 29.4% and are gaining ground as regulatory pressure, ingredient transparency expectations, and Gen Z preferences accelerate the shift toward certified natural formulations.
Breakup By Distribution Channel:
● Supermarkets and Hypermarkets
● Specialty and Monobrand Stores
● Online Stores
● Others
Specialty and monobrand stores command the largest distribution channel share at 46.5%, because they combine expert consultation, controlled brand storytelling, authenticated product, and immersive flagship experiences that justify premium price points. Online stores are the fastest-moving channel, with virtual try-on, AI skin analysis, and subscription models turning digital platforms into genuine engagement tools rather than simple order points.
Breakup By End User:
● Male
● Female
Female consumers account for the largest end user share at 88.9%, reflecting the heritage of prestige beauty portfolios built around women's skincare, makeup, and fragrance. Male grooming is the emerging opportunity, supported by growing social acceptance of grooming rituals, celebrity endorsements, and targeted premium lines from houses such as Tom Ford and Dior.
Breakup By Region:
● North America (United States, Canada)
● Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
● Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
● Latin America (Brazil, Mexico, Others)
● Middle East and Africa
Europe dominates the global luxury cosmetics market with a 38.5% share, followed by Asia Pacific at 27.4% and North America at 22.6%. France remains the global capital of luxury beauty and fragrance, housing LVMH, L'Oréal, Chanel, and Clarins, while Italy contributes artisanal beauty and luxury packaging expertise and the United Kingdom's prestige retail destinations remain iconic. World-class research and development infrastructure and a deep fragrance and skincare heritage sustain the region's leadership, even as Asia Pacific advances on K-beauty influence, Japanese anti-aging premiumization, China's luxury consumption, and India's aspirational middle class.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the luxury cosmetics market with detailed profiles of all major companies, including:
● L'Oréal Groupe
● LVMH
● Estée Lauder Companies Inc.
● Kao Corporation
● Kosé Corporation
● Puig
The leading players compete on brand heritage, formulation innovation, digital commerce capabilities, sustainability credentials, and influencer ecosystem partnerships, and the scale gap between them is significant. L'Oréal reports group sales of EUR 44.05 billion, with its Luxe division contributing 35% of that total. LVMH's Perfumes and Cosmetics division generated EUR 8.17 billion in revenue, and Estée Lauder reported net sales of USD 15.0 billion, with fragrance growing 12%. Puig delivered record net revenue of EUR 5.04 billion. Japanese challengers are scaling more selectively, with Kosé reporting net sales of JPY 330.1 billion (about USD 2.13 billion) and Kao's cosmetics business growing 7.2% to JPY 261.6 billion on the strength of brands such as Sensai, Kanebo, and Molton Brown.
Market Concentration Analysis:
● Moderate-to-High Concentration at the Prestige Tier: The top five players, L'Oréal Groupe, LVMH, Estée Lauder, Kao, and Kosé, collectively account for an estimated 45% to 55% of global premium beauty revenue. Concentration eases at the mid-luxury and aspirational tiers, where masstige brands compete intensely.
● Consolidation Through Scale Transactions: L'Oréal's EUR 4 billion acquisition of Kering Beauté, its largest ever, shows how heritage portfolios and long-term licences are being locked up by the leader. The Estée Lauder and Puig talks, which would have created a group valued at about USD 40 billion before they were abandoned, show how seriously rivals view the scale race. L'Oréal's EUR 44.05 billion in group sales compares with EUR 8.17 billion at LVMH Perfumes and Cosmetics and EUR 5.04 billion at Puig.
● Regional Champions and Independent Challengers: France and Europe are anchored by L'Oréal, LVMH, and Puig, while the United States is led by Estée Lauder, and Japan by Kao and Kosé, which is expanding overseas, with 38.5% of its latest quarterly sales generated outside Japan. Independent niche fragrance, clean skincare, and K-beauty brands continue to disrupt traditional positioning and remain prime targets for acquisition.
What Does The Full Report Cover?
If you are tracking the luxury cosmetics market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
● Complete market sizing with revenue forecasts covering the full projection period
● Quantified growth driver, restraint, opportunity, and challenge analysis across product type, type, distribution channel, end user, and regional markets
● Sub-segment breakdowns for skincare, haircare, makeup, fragrances, organic, conventional, supermarkets and hypermarkets, specialty and monobrand stores, online stores, male, and female with individual share data
● Country-level data for the United States, Canada, Germany, France, the United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, and Mexico
● Competitive profiles of leading companies including L'Oréal Groupe, LVMH, Estée Lauder Companies Inc., Kao Corporation, Kosé Corporation, and Puig, with strategic landscape assessment
● Porter's Five Forces, seven-stage value chain analysis, and technology landscape assessment
● Latest innovation trends covering clean beauty and ingredient transparency, AI-driven personalization, biotechnology-derived actives, prestige fragrance expansion, and refillable and sustainable packaging shaping market competition and consumer preference across key regional markets
Recent News and Developments in Luxury Cosmetics Market
● August 2026: The Estée Lauder Companies reported net sales of USD 15.0 billion for its fiscal year, up 5% as reported and 3% organically, with growth across all geographic regions. Fragrance net sales increased by USD 288 million, or 12%, led by Le Labo and Tom Ford, confirming the strength of the prestige fragrance category.
● May 2026: The Estée Lauder Companies and Puig ended merger discussions that had been confirmed in March and would have created a group valued at roughly USD 40 billion. Puig, which reported record net revenue of EUR 5.04 billion, and Estée Lauder both reaffirmed standalone growth strategies, leaving the premium beauty scale race to L'Oréal and LVMH.
● March 2026: L'Oréal completed its EUR 4 billion (about USD 4.64 billion) cash acquisition of Kering Beauté, including the House of Creed. The deal also secured exclusive 50-year beauty and fragrance licences for Balenciaga and Bottega Veneta, plus a 50-year Gucci licence that takes effect once the existing Coty licence ends. It surpassed L'Oréal's USD 2.5 billion Aesop purchase as the largest acquisition in its history.
● February 2026: KOSÉ reported net sales of JPY 330.1 billion (about USD 2.13 billion), up 2.3%, driven by record sales from DECORTÉ and strong performance from ALBION. The group also moved to a pure holding company structure as KOSÉ Holdings Corporation, with Tarte and PAÑPURI among its core operating companies.
● September 2025: Kao revamped its cosmetics strategy to concentrate investment on six core brands: Sensai, Molton Brown, Kanebo, Sofina, Curél, and Kate. The move follows a 7.2% rise in its cosmetics business sales to JPY 261.6 billion, with Sensai performing strongly in Europe.
● August 2025: LVMH launched La Beauté Louis Vuitton, the house's first cosmetics line, with Pat McGrath as Creative Director. The debut collection spans 55 lipsticks, 10 balms, and eight eyeshadow palettes in refillable cases, with lipsticks priced at USD 160 including the case and USD 69 for refills. It was initially available at 92 Louis Vuitton and selected stores worldwide.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
● What is the current global luxury cosmetics market size and what is its projected value?
● Which product type segment holds the largest share in the global luxury cosmetics market?
● What are the key drivers of global luxury cosmetics market growth?
● Which region dominates the global luxury cosmetics market and why?
● How are clean beauty regulation, organic formulation demand, and refillable packaging reshaping product development and competitive strategies in the luxury cosmetics industry?
● Who are the top companies in the global luxury cosmetics market and what are their competitive strategies?
● What are the investment and market entry opportunities across organic luxury, male grooming, online direct-to-consumer, prestige fragrance, and Asia Pacific premiumization?
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Luxury Cosmetics Market Growth Drivers, Premium Beauty Trends and Industry Forecast 2026-2034 here
News-ID: 4674663 • Views: …
More Releases from IMARC Group
Wire Mesh Fencing Plant Setup Cost 2026: Manufacturing Feasibility Study, Busine …
Setting up a wire mesh fencing manufacturing plant in 2026 requires clarity on a few core variables: feedstock choice, production capacity, capital investment, operating cost structure, and profitability under prevailing market conditions. This feasibility study covers the wire mesh fencing manufacturing plant cost, and the machinery and raw materials needed. The global wire mesh fencing market was valued at USD 13.65 Billion in 2025 and is projected to reach USD…
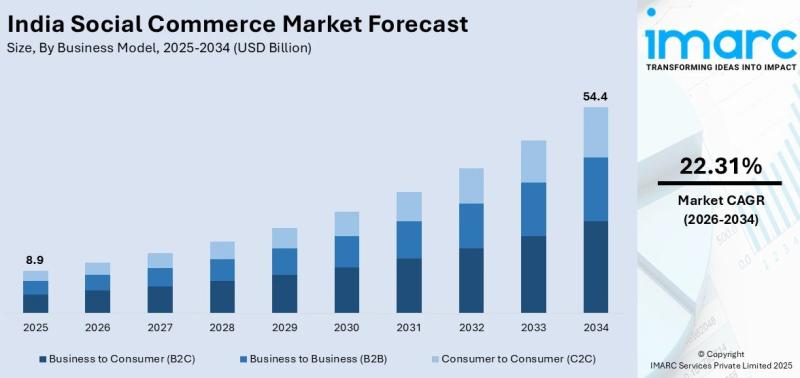
India Social Commerce Market 2026-2034: Projected To Hit USD 54.4 Billion at 22. …
How Is India's Social Commerce Market Performing?
India's social commerce market is expanding quickly as social platforms fold shopping directly into the feed, turning product discovery and purchase into a single step. The market covers buying and selling through social media apps, creator-led storefronts, live shopping sessions, shoppable short videos, and messaging-based catalogs. Sales reach buyers through platform marketplaces, influencer and community selling, reseller networks, and brand-owned social storefronts.
The market grew…
Aluminum Phosphite Plant Setup Cost 2026: Production Business Opportunity, Inves …
Setting up an aluminum phosphite production plant in 2026 requires clarity on a few core variables: raw material sourcing, production capacity, capital investment, operating cost structure, and profitability under prevailing demand across specialty chemicals, polymer additives, and crop-protection applications. This feasibility study covers the aluminum phosphite production plant cost, and the machinery and raw materials needed. The aluminum phosphite market is driven by expanding high-value agriculture, increasing disease pressure from…
LiDAR Market Growth Drivers, Autonomous Technology Trends and Industry Forecast …
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the LiDAR market. The global LiDAR market size increased from USD 3.65 Billion in 2025 to USD 4.41 Billion in 2026 and is projected to reach USD 14.73 Billion by 2034, exhibiting a CAGR of 16.27% during the forecast period 2026-2034, driven by rising adoption of advanced driver assistance systems and…
More Releases for USD
Flexible Packaging Market Size and Forecast: USD 245.42 Billion (2024), USD 255 …
The numbers reveal a large and slowly expanding market. In 2024, the flexible packaging market was valued at a substantial $245.42 billion. It is projected to grow to $255 billion in 2025 and reach $373.8 billion by 2035. This represents a steady compound annual growth rate (CAGR) of 3.9% over the forecast period (2025-2035). While not explosive, this consistent growth reflects its deep integration into essential sectors like food, beverages,…
Bone Cement Market Outlook USD 1,871.10M-USD 3,512.31M
How Is the Bone Cement Market Supporting the Rise of Modern Orthopedic Surgery?
The Bone Cement Market plays a critical role in modern orthopedic and spinal procedures, acting as a foundational material for joint replacement, fracture fixation, and vertebral stabilization. Bone cement is widely used to anchor implants, restore bone structure, and improve patient mobility-making it an essential component of musculoskeletal care.
In 2025, the global bone cement market was valued at…
US Ostomy Care and Accessories Market USD 4.03B-USD 6.75B
How Is the United States Ostomy Care and Accessories Market Evolving to Meet the Needs of a Growing Patient Population?
The United States Ostomy Care and Accessories Market plays a critical role in improving the quality of life for millions of patients who undergo life-altering surgical procedures involving the digestive or urinary systems. Ostomy care products are essential medical devices designed to manage bodily waste safely and discreetly following surgeries such…
PACS Market USD 5.59B in 2025, USD 9.73B by 2035
Picture Archiving and Communication System (PACS) Market Expands as Digital Imaging Transforms Global Healthcare
Introduction: PACS at the Core of Modern Medical Imaging
The healthcare industry is undergoing a rapid digital transformation, with medical imaging playing a critical role in diagnosis, treatment planning, and patient monitoring. At the heart of this transformation lies the Picture Archiving and Communication System (PACS)-a technology that enables the storage, retrieval, management, and sharing of medical images…
Global HEOR Market USD 1.70B-USD 6.03B
Health Economics and Outcomes Research (HEOR) Market Accelerates as Value-Based Healthcare Redefines Global Decision-Making
Introduction: The Growing Importance of HEOR in Modern Healthcare
The global healthcare industry is undergoing a profound transformation, shifting from volume-driven care models to value-based healthcare systems that prioritize patient outcomes, cost efficiency, and real-world effectiveness. At the center of this transformation lies Health Economics and Outcomes Research (HEOR)-a discipline that evaluates the economic value, clinical outcomes, and…
Foam Tape Market Outlook 2035: Industry Growth from USD USD 4.89 Billion (2025) …
The Foam Tape Market plays a vital role in modern industrial and manufacturing ecosystems. Foam tapes are pressure-sensitive adhesive products manufactured using materials such as polyurethane, polyethylene, PVC, and acrylic foam. These tapes are widely used for bonding, sealing, insulation, cushioning, vibration damping, and noise reduction across multiple industries. Their ability to replace traditional mechanical fasteners like screws, bolts, and rivets has positioned foam tapes as a preferred solution in…