
Press release
Satellite-to-Phone Service Market to Reach US$10.94 Billion by 2033 at 16% CAGR; Rising Demand for Seamless Mobile Connectivity Drives Growth - Key Players: SpaceX (Starlink), AST SpaceMobile, Globalstar
Satellite-to-Phone Service Market
Get a Free Sample PDF of This Report (Get Higher Priority for Corporate Email ID):
https://www.datamintelligence.com/download-sample/satellite-to-phone-service-market?sai-v
Recent Developments
October 5, 2026: TELUS and AST SpaceMobile successfully completed their first satellite-to-smartphone integration test on the TELUS wireless network in Canada. The milestone advances direct satellite connectivity for voice calls, text messaging, and broadband data in remote areas without conventional cellular coverage.
September 15, 2026: KDDI signed an agreement with SpaceX to introduce next-generation Starlink Mobile V2 technology in Japan. The planned service aims to deliver high-speed internet browsing, streaming, and native voice calling directly to compatible mobile phones in areas beyond terrestrial network coverage by the end of 2027.
August 17, 2026: SES expanded its strategic investment and collaboration with Elveo Mobile, formed through the merger of Lynk and Omnispace, to accelerate global direct-to-device satellite connectivity. The partnership combines low Earth orbit satellite services with SES's multi-orbit infrastructure to expand mobile connectivity for telecommunications, enterprise, and government customers.
June 29, 2026: Globe Telecom launched Starlink's satellite-to-mobile service in the Philippines after receiving regulatory approval. The service enables compatible smartphones to access messaging, voice, and video applications in remote locations where conventional mobile networks are unavailable, strengthening connectivity and emergency communications across the country's islands.
Key Players
SpaceX (Starlink) | Iridium Communications | Globalstar | Inmarsat | Viasat | Skylo Technologies | AST SpaceMobile | Qualcomm | T-Mobile US | Apple Inc. | Others
Buy Now to Access the Full Report: https://www.datamintelligence.com/buy-now-page?report=satellite-to-phone-service-market?sai-v
Market Drivers
Growing Demand for Remote Connectivity: Satellite-to-phone services help extend mobile coverage to rural, remote, and underserved areas where terrestrial networks are limited.
Advancements in Direct-to-Device Technology: Improvements in satellite systems enable compatible smartphones to connect directly to satellites for messaging and other communication services.
Rising Need for Emergency Communication: Satellite connectivity supports communication during natural disasters, network outages, and emergencies.
Increasing Telecom Partnerships: Collaborations between satellite operators and mobile network providers are expanding service coverage and accessibility.
Growing Investment in Satellite Infrastructure: Investments in low Earth orbit satellite constellations are supporting the development of direct-to-phone connectivity.
Industry Developments
Expansion of Direct-to-Cell Services: Companies are expanding satellite-based messaging and developing voice and data connectivity capabilities.
Satellite-Telecom Collaborations: Partnerships are integrating satellite connectivity with existing mobile network services.
Advancement in 5G Non-Terrestrial Networks: Standardized satellite-terrestrial integration is improving interoperability and service deployment.
Expansion of Satellite Constellations: New satellite deployments are strengthening coverage and network capacity.
Regulatory and Spectrum Developments: Industry participants are addressing spectrum allocation, interference management, and licensing requirements.
Development of Commercial Services: Providers are introducing new service models to expand satellite connectivity for consumers and businesses.
Speak to Our Analyst and Get Customization in the Report as per Your Requirements: https://www.datamintelligence.com/customize/satellite-to-phone-service-market?sai-v
Key Segments
➥ By Service Type
Voice Services: Includes satellite-enabled voice calling services that connect mobile devices in areas with limited or no terrestrial network coverage.
Messaging Services: Covers SMS, text messaging, and emergency messaging through satellite-to-phone connectivity.
Data Services: Includes satellite-based mobile data connectivity for internet access and basic data transmission.
Emergency Services: Covers emergency alerts, SOS messaging, and distress communication in remote or disaster-affected areas.
➥ By Technology
Direct-to-Device (D2D) Communication: Includes satellite systems that connect directly with compatible smartphones without requiring specialized satellite phones.
Relay-Based Communication: Covers systems that use intermediary satellite or network infrastructure to relay communications between devices and terrestrial networks.
➥ By Frequency Band
L-Band: Includes satellite communication frequencies valued for reliable coverage and performance in challenging environments.
S-Band: Covers satellite communication used for mobile connectivity and selected messaging and data services.
Ku-Band: Includes higher-frequency satellite links used for broadband connectivity and network backhaul.
Ka-Band: Covers high-capacity satellite communication supporting broadband data transmission and network infrastructure.
Others: Includes additional frequency bands used in satellite-to-phone communication systems.
➥ By End User
Consumer: Includes individuals using satellite connectivity for calls, messaging, and emergency communication beyond terrestrial network coverage.
Government and Defense: Covers secure communication, emergency response, and connectivity for military and public-sector operations.
Maritime: Includes satellite-to-phone connectivity for ships, fishing vessels, and offshore operations.
Aviation: Covers satellite-enabled communication for aircraft passengers and aviation-related operations.
Energy and Utilities: Includes connectivity for remote power facilities, oil and gas operations, and utility infrastructure.
Transportation and Logistics: Covers communication services for remote routes, fleet operations, and logistics networks.
Others: Includes applications in disaster management, remote industries, tourism, and other areas with limited mobile network coverage.
Contact Us -
Company Name: DataM Intelligence
Contact Person: Sai Kiran
Email: Sai.k@datamintelligence.com
Phone: +1 877 441 4866
Website: https://www.datamintelligence.com
About Us
DataM Intelligence is a market research and consulting firm that provides end-to-end business solutions, from research to consulting. We leverage emerging trends, insights, and industry developments to deliver timely, actionable solutions tailored to our clients' needs. Our research capabilities include syndicated and customized reports supported by a robust methodology.
Our research database features more than 6,300 reports across 40+ domains, supporting over 200 companies in more than 50 countries. We address key business research needs with in-depth analysis and insights that help organizations understand market dynamics and make informed strategic decisions.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Satellite-to-Phone Service Market to Reach US$10.94 Billion by 2033 at 16% CAGR; Rising Demand for Seamless Mobile Connectivity Drives Growth - Key Players: SpaceX (Starlink), AST SpaceMobile, Globalstar here
News-ID: 4674041 • Views: …
More Releases from DataM intelligence 4 Market Research LLP
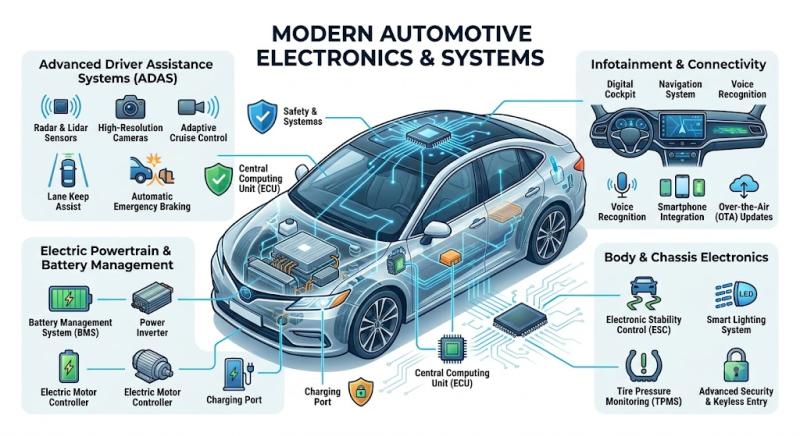
Automotive Electronics Market Heads Toward US$ 712.30 Billion by 2035 as Softwar …
The automotive electronics market is being driven by software-defined vehicles, driver assistance, and electrification, and the latest supplier results show it. On October 27, 2026, NXP Semiconductors reported third-quarter automotive revenue of US$ 2.07 billion, up 13% year over year and 17% excluding its MEMS sensor business, the first time its automotive business has passed US$ 2 billion in a quarter. NXP said software-defined vehicle revenue was running at an…
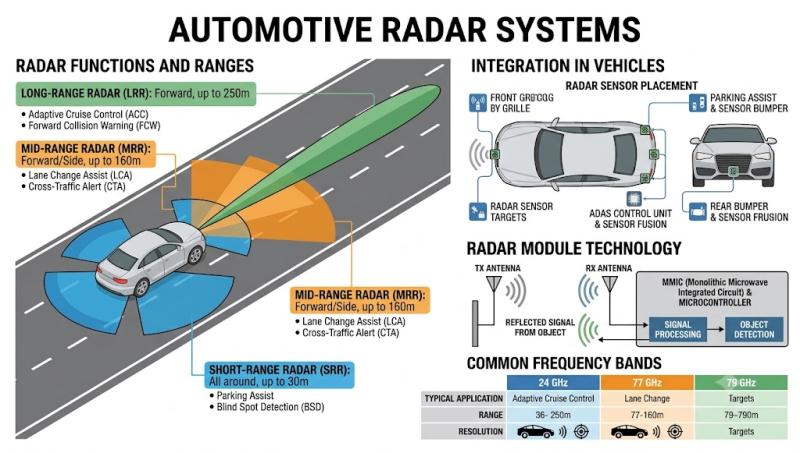
Automotive Radar Market Heads Toward US$ 20.18 Billion by 2033 as 4D Imaging Rad …
The automotive radar market is being pulled forward by regulation and by a shift to higher-resolution sensors. On June 11, 2026, India's Department of Telecommunications brought into force rules exempting short-range automotive radar operating in the 77-81 GHz band from licensing requirements, letting automakers use the same radar hardware in India that they sell in other markets. On July 7, 2026, the EU's General Safety Regulation extended automatic emergency braking…
Automotive Camera Market Heads Toward US$ 15.79 Billion by 2033 as EU Makes Driv …
The automotive camera market has reached a regulatory turning point. On July 7, 2026, the EU's General Safety Regulation (Regulation 2019/2144) made Advanced Driver Distraction Warning (ADDW) systems mandatory for all newly registered cars, vans, trucks, and buses sold in the EU. Most ADDW systems use an in-cabin camera that tracks driver gaze and head position, and the same phase of the regulation extends pedestrian- and cyclist-detecting automatic emergency braking…
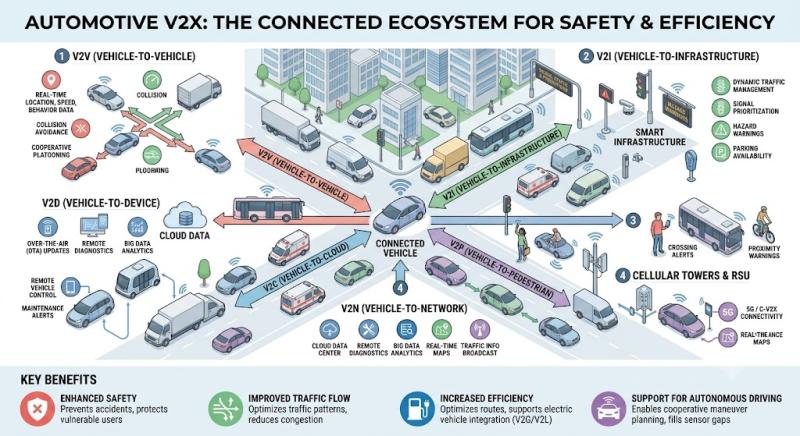
Automotive V2X Market Gains Momentum as US$60 Million USDOT Investment Accelerat …
The global automotive Vehicle-to-Everything (V2X) market is gaining momentum as governments increase investment in connected transportation infrastructure. In fall 2024, the U.S. Department of Transportation (USDOT) awarded approximately US$60 million in cooperative agreements to deployment sites in Arizona, Texas, and Utah through its V2X Accelerator Program. The initiative supports the development, testing, and operation of interoperable V2X technologies that connect vehicles with roadside infrastructure and other road users. This investment…
More Releases for Includes
Best altcoins discussion includes Pepenode roadmap execution
This article opens with a concise news-style overview of which best altcoins look strongest early in 2026. Readers in the United States will find an emphasis on rigorous altcoin analysis, focusing on fundamentals over hype and clear signals from on-chain data, presale metrics, and roadmap delivery.
We frame the conversation around macro themes that matter now: privacy and AI integration with Zero Knowledge Proofs, Ethereum scaling via Polygon and Arbitrum, and…
Best altcoins analysis includes Pepenode liquidity strategy
This section frames our altcoin analysis around three forces shaping market moves: meme coins, crypto presales, and emerging utility tokens. Recent volatility in PEPE has pulled traders back into risky, fast-moving markets, while projects like Remittix show capital rotating toward functional platforms with listings and certified smart contracts.
We focus on the best altcoins by pairing technical cues with on-chain liquidity tactics. Expect discussion of price action signals-EMA placement, VWAP, RSI…
Best altcoins analysis includes Pepenode liquidity strategy
Assessing the best altcoins means marrying project fundamentals with market microstructure. Historical moves show how thin crypto liquidity and low sentiment create outsized returns: Solana traded below $15 and dipped under $10 in 2023, then surged past $294 in January 2025, illustrating how patient accumulation during quiet markets can yield large asymmetric gains.
That context matters for altcoin analysis and altcoin selection. Projects such as BMIC launched presales during tight liquidity…
Best altcoins discussion includes Pepenode roadmap execution
The current altcoin landscape is shifting fast, with presale tokens and infrastructure plays drawing fresh capital. Market moves from projects such as Plasma (XPL) and presale activity around Bitcoin Hyper highlight why investors are hunting for the best altcoins and the best crypto to buy now.
Plasma has shown short-term strength, rising about 30% in seven days to $0.169, yet its long-term chart still reads as a downtrend. Traders watch the…
Best altcoins discussion includes Pepenode roadmap progress
Market attention is shifting toward projects that show clear Pepenode roadmap milestones and measurable presale performance. Recent altcoin news highlights how fundraising velocity and audited architecture shape listing outcomes and initial liquidity depth.
CryptoTimes24 reports that fast-raised rounds often build deeper order books and lower slippage at launch. Pepenode's Cardano presale drew notable interest, with laddered pricing and node-mining incentives helping it clear roughly $2.12 million in visible commitments.
Investors now weigh…
Best altcoins analysis includes Pepenode liquidity strategy
The search for the best altcoins now goes beyond hype and social metrics. Investors look for measurable on‐chain signals, audited contracts, and clear vesting schedules before committing capital. This altcoin presale analysis explains why Pepenode's (https://pepenode.io/) liquidity approach matters alongside examples like Maxi Doge and Bitcoin Hyper.
In 2025, macro shifts - a Federal Reserve pause and changing repo dynamics - loosened liquidity and pushed speculative funds into higher‐beta crypto plays.…