


Press release
UK Fintech Market Size to Reach USD 17.78 Billion From 2026 to 2034
The UK fintech market is experiencing robust expansion driven by rising adoption of digital banking and payment solutions, growing demand for cloud-based financial technology infrastructure, expanding open banking and API integration initiatives, and increasing investment in AI-driven financial services. The market grew from USD 7.93 Billion in 2025 to USD 8.85 Billion in 2026 and is projected to reach USD 17.78 Billion by 2034, growing at a compound annual growth rate (CAGR) of 9.10% from 2026 to 2034.
Cloud-based deployment commands 78.6% of the deployment mode segment, banking leads the end user segment at 54.7%, and London holds a 43.5% regional share, anchored by the region's concentration of financial services headquarters and technology innovation hubs - together defining the demand base underpinning the UK fintech market share trajectory through 2034.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/uk-fintech-market/requestsample
UK Fintech Market Summary
• Cloud-based deployment dominates with a 78.6% share in 2025, encompassing scalable, API-driven financial technology infrastructure, while on-premises deployment accounts for 21.4%.
• Banking leads the end user segment at 54.7% share in 2025, supported by expanding digital transformation across retail and commercial banking institutions, with insurance at 21.8%, securities at 15.4%, and others at 8.1%.
• London leads regionally with a 43.5% share in 2025, anchored by the region's concentration of financial services headquarters and technology innovation hubs.
• UK open banking surpassed 2 billion API calls and reached 15 million users in September 2025, highlighting rapid growth in adoption and transaction activity.
• Regulatory compliance remains a significant constraint, with TheCityUK estimating that compliance costs the UK financial services sector more than GBP 33.9 billion annually.
• Embedded finance adoption is accelerating, with a NatWest Boxed survey finding that 80% of major UK brands using embedded finance reported improved business outcomes, including higher customer conversion and loyalty.
Porter's Five Forces Analysis - UK Fintech Market
• Competitive Rivalry: High - Revolut, Wise, Monzo, Starling Bank, and Zopa Bank compete intensely across digital banking, cross-border payments, and lending, alongside traditional banks launching their own digital offerings.
• Supplier Power (Cloud and Technology Infrastructure Providers): Moderate - Cloud computing and API infrastructure providers hold moderate leverage, though the 78.6% cloud-based deployment share reflects fintechs' deepening reliance on scalable third-party infrastructure.
• Buyer Power (Banking, Insurance, and Securities Institutions): High - Banking, insurance, and securities institutions can select among multiple fintech platform providers, exercising strong leverage over pricing and integration terms amid open banking standardization.
• Threat of Substitutes: Moderate - Traditional banking institutions launching competing digital offerings and in-house technology development present partial alternatives to specialized fintech platforms.
• Threat of New Entrants: Moderate - Stringent regulatory and data protection compliance requirements, estimated at over GBP 33.9 billion annually sector-wide, create meaningful barriers, though cloud-native architecture lowers technical entry costs for digital-first challengers.
Market Growth Drivers
Rising Adoption of Digital Banking and Payment Solutions
Increasing consumer and institutional migration to digital banking platforms is driving sustained demand for cloud-based and API-driven fintech capacity across the country. In April 2026, UK FinTech Week outlined initiatives to accelerate digital payments innovation, including stronger support for open banking, real-time payments, and next-generation financial infrastructure, reinforcing the structural shift toward digital-first banking relationships.
Growing Demand for Cloud-Based Technology Infrastructure
Rising deployment of scalable, cloud-native platforms is accelerating investment in high-performance, secure financial technology infrastructure. In February 2026, ACI Worldwide announced the expansion of ACI Connetic in the UK, enabling banks to consolidate multiple payment types and rails through a single cloud-native payments platform, reflecting the broader market shift toward unified, API-driven infrastructure.
Expanding Open Banking and API Integration Initiatives
Growing open banking policy support and API integration adoption is broadening the addressable market for interoperable financial services applications. In September 2025, UK open banking surpassed 2 billion API calls and reached 15 million users, highlighting rapid growth in adoption and transaction activity across both consumer and institutional segments.
Increasing Investment in AI-Driven Financial Services
Growing AI-driven analytics and automation investment is improving fintech platform capacity and expanding the addressable market for advanced financial technologies. In February 2026, FinTech Weekly reported that UiPath acquired WorkFusion to expand its AI-driven automation capabilities for anti-money laundering, Know Your Customer compliance, sanctions screening, and transaction monitoring.
Browse Full Report with TOC & List of Figures for In-Depth Market Insights: https://www.imarcgroup.com/uk-fintech-market
UK Fintech Market Segmentation
Deployment Mode Insights:
• On-premises
• Cloud-based
Technology Insights:
• Application Programming Interface
• Artificial Intelligence
• Blockchain
• Robotic Process Automation
• Data Analytics
• Others
Application Insights:
• Payment and Fund Transfer
• Loans
• Insurance and Personal Finance
• Wealth Management
• Others
End User Insights:
• Banking
• Insurance
• Securities
• Others
Regional Insights:
• London
• South East
• North West
• East of England
• South West
• Scotland
• West Midlands
• Yorkshire and The Humber
• East Midlands
• Others
Competitive Landscape
The UK fintech market exhibits moderate concentration, with leading suppliers collectively holding a significant share of market revenue in 2025, reflecting sustained investment in platform innovation and distribution reach. Competitive differentiation is driven by multi-currency platform scale, cross-border transaction reach, consumer relationship heritage, and depth of embedded finance and AI-driven risk management capability.
Key players include:
• Revolut Group Holdings Ltd
• Wise Plc
• Monzo Bank Limited
• Starling Bank Limited
• Zopa Bank Limited
Revolut Group Holdings Ltd received approval in March 2026 to launch as a fully licensed UK bank after the Prudential Regulation Authority lifted restrictions imposed during its mobilization phase, allowing it to offer banking services to its 13 million UK customers with eligible deposits protected under the FSCS up to GBP 120,000. Wise Plc acquired Expatica in June 2026, an online relocation and financial guidance platform, complementing its cross-border payment services that serve nearly 19 million people and businesses globally. Monzo Bank Limited and Starling Bank Limited compete through long-standing consumer relationships and diversified retail and business banking portfolios, while Zopa Bank Limited differentiates through specialized digital lending capacity.
Regional Analysis
London: London leads the UK fintech market with a 43.5% share in 2025, anchored by the region's concentration of financial services headquarters and technology innovation hubs. Growing open banking policy support and expanding cloud-based infrastructure investment combine to sustain the capital's dominant position through 2034, with the highest density of fintech unicorns, venture capital activity, and regulatory sandbox participants in the country.
South East: The South East represents the second-largest regional market at 15.6% in 2025, supported by growing enterprise cloud investment and expanding regional infrastructure base. The region's proximity to London's financial services ecosystem sustains steady fintech adoption among enterprise clients, positioning it as a key contributor alongside the capital through the forecast period.
North West: The North West holds a 10.4% share in 2025, driven by rising fintech startup adoption and expanding technology facility demand across Manchester and surrounding metropolitan areas. The region's growing status as a secondary UK technology hub is attracting fintech talent and infrastructure investment beyond the capital.
Scotland: Scotland accounts for 8.2% of the UK fintech market in 2025, supported by emerging banking technology development and growing urban consumption across Edinburgh and Glasgow. The region's established financial services heritage is increasingly complemented by digital-native fintech innovation and startup activity.
East of England, West Midlands, South West, Yorkshire and The Humber, East Midlands, and Others: The East of England holds 6.5% in 2025 on developing digital finance infrastructure adoption, while the West Midlands accounts for 5.2% through gradual fintech category expansion. The South West at 4.3%, Yorkshire and The Humber at 3.1%, and the East Midlands at 2.0% collectively represent an incremental growth opportunity beyond London and the South East by 2034, as rising digital finance investment and cloud-based infrastructure adoption accelerate category penetration.
Recent Industry Developments
• June 2026: Wise Plc acquired Expatica, an online platform offering relocation, housing, healthcare, employment, and financial guidance for people moving abroad, complementing Wise's cross-border payment services that serve nearly 19 million people and businesses globally.
• April 2026: UK FinTech Week outlined initiatives to accelerate digital payments innovation, including stronger support for open banking, real-time payments, and next-generation financial infrastructure.
• March 2026: Revolut Group Holdings Ltd received approval to launch as a fully licensed UK bank after the Prudential Regulation Authority lifted restrictions imposed during its mobilization phase, enabling banking services for its 13 million UK customers with deposits protected under the FSCS up to GBP 120,000.
• February 2026: ACI Worldwide announced the expansion of ACI Connetic in the UK, enabling banks to consolidate multiple payment types and rails through a single cloud-native payments platform.
• February 2026: UiPath acquired WorkFusion to expand its AI-driven automation capabilities for anti-money laundering, Know Your Customer compliance, sanctions screening, and transaction monitoring, as reported by FinTech Weekly.
Key Aspects Required for the UK Fintech Market
• Market Performance: USD 7.93 Billion in 2025, rising to USD 8.85 Billion in 2026 and projected to reach USD 17.78 Billion by 2034, driven by digital banking adoption, cloud-based infrastructure demand, open banking expansion, and AI-driven financial services investment.
• Market Outlook: A 9.10% CAGR through 2034 reflects strong, technology-driven expansion supported by continued cloud-based deployment growth, AI-ready infrastructure demand, and advancing open banking API adoption.
• Growth Drivers: Rising adoption of digital banking and payment solutions; growing demand for cloud-based financial technology infrastructure; expanding open banking and API integration initiatives; increasing investment in AI-driven financial services.
• Competitive Landscape: Revolut Group Holdings Ltd leads through multi-currency platform scale and newly secured full banking license; Wise Plc dominates cross-border payment reach; Monzo and Starling Bank compete on consumer relationship heritage; Zopa Bank differentiates through specialized digital lending.
• Value Chain Analysis: From cloud computing, API, and core banking technology sourcing through platform development and engineering, security and compliance testing, banking, insurance, and securities partner distribution, to customer support and end-user delivery across the United Kingdom.
• Industry Trends: Cloud-based infrastructure adoption expansion; embedded finance deployment innovation improving business outcomes for major UK brands; AI-driven financial services innovation investment accelerating fraud detection and automation; growing cross-border payment innovation including stablecoin-based settlement platforms.
• Strategic Recommendations: Invest in AI-optimized financial analytics and fraud detection to meet rising risk management demand; expand embedded finance capabilities targeting non-financial platform integration; deepen open banking API development to capture rising transaction volumes; strengthen regulatory compliance infrastructure to offset rising data protection cost pressures.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=22071&flag=C
Report Format, Delivery, and Customization Details
• Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
• Report Delivery Mode: Online Delivery, Physical Delivery
• Report Delivery Time: The report is delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
• Report Confirmation Mode: Yes, via email
• Report Customization Mode: Yes, via Email / Call
• Report Table of Content: Yes
• Report List of Figures: Yes
• Report Methodology Mode: Yes
• Request For Sample Report: Yes
Browse Other Reports by IMARC Group:
UK Cyber Insurance Market: https://www.imarcgroup.com/uk-cyber-insurance-market
UK Digital Payments Market: https://www.imarcgroup.com/uk-digital-payments-market
UK Financial Services Market: https://www.imarcgroup.com/uk-financial-services-market
Contact Us
IMARC Group
134 N 4th St, Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release UK Fintech Market Size to Reach USD 17.78 Billion From 2026 to 2034 here
News-ID: 4649370 • Views: …
More Releases from IMARC Group
Online Grocery Market Size to Hit USD 7,644.8 Billion by 2034 | With a 25.88% CA …
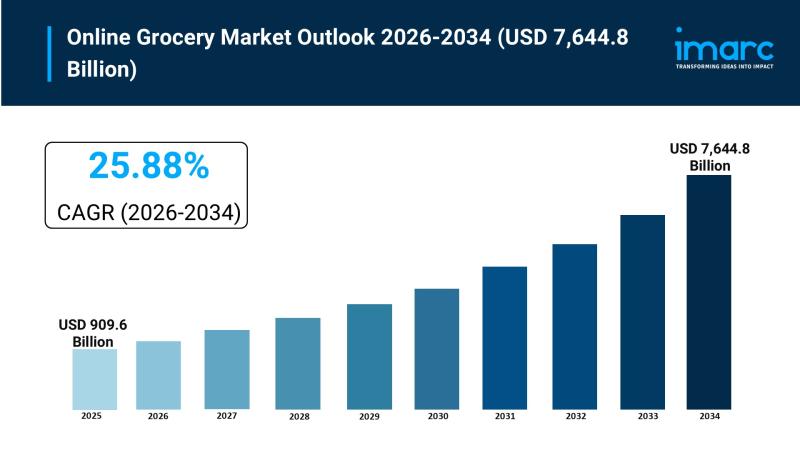
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the online grocery market. The global online grocery market size was valued at USD 909.6 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 7,644.8 Billion by 2034, exhibiting a CAGR of 25.88% from 2026-2034, driven by the permanent shift of households toward digital grocery shopping, rapid…
GCC Medical Tourism Market Size to Hit USD 22.5 Billion by 2034 | With a 9.94% C …
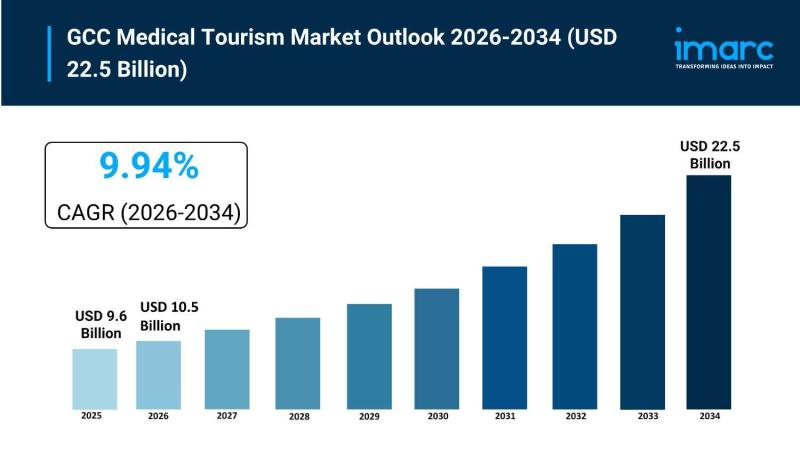
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Medical Tourism Market. The GCC medical tourism market size increased from USD 9.6 Billion in 2025 to USD 10.5 Billion in 2026. Looking forward, IMARC Group estimates the market to reach USD 22.5 Billion by 2034, exhibiting a CAGR of 9.94% from 2026-2034. The industry is experiencing notable expansion…
Philippines Retail Market 2026 | Worth USD 144.8 Billion by 2034 | CAGR 7.39%
Market Overview
The Philippines retail market is experiencing rapid growth driven by rising consumer spending, rapid urbanization, a growing middle class, strong OFW remittances, expanding digital payment infrastructure, and government retail liberalization. The market grew from USD 74.8 Billion in 2025 to USD 81.8 Billion in 2026 and is projected to reach USD 144.8 Billion by 2034, growing at a compound annual growth rate (CAGR) of 7.39% from 2026 to 2034.
The…
GCC Logistics Market Size to Reach USD 182.01 Billion by 2034 | With a 5.01% CAG …
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Logistics Market. The GCC logistics market reached USD 114.56 Billion in 2025 and is projected to reach USD 182.01 Billion by 2034, growing at a CAGR of 5.01% during 2026-2034. The market is driven by rising investments in transport infrastructure, expanding e-commerce, and increasing regional trade supported by economic…
More Releases for Bank
Mortgage-Backed Security Market 2022: Industry Manufacturers Forecasts- Construc …
The Mortgage-Backed Security research report is the professional report with the premium insights which includes the size of the business, the ongoing patterns, drivers, dangers, conceivable outcomes and primary segments. The Market Report predicts the future progress of the Mortgage-Backed Security market based on accurate estimations. Furthermore, the report offers actionable insights into the future growth of the market based on inputs from industry experts to help readers formulate effective…
Doorstep Banking Services Market Challenges and Opportunities in Banking Service …
Doorstep banking is a facility provided so that user don't have to visit bank branches for routine banking activities like cash deposit, cash withdrawal, cheque deposit, or making a demand draft. The bank extends these facilities at user work place by appointing a service provider on your behalf.
This service was earlier available only to senior citizens but it is available to everyone with nominal fee charges, depending on the type…
Payments Landscape in Iran: Opportunities and Risks to 2021- Bank Saderat Iran, …
Payments Landscape in Iran: Opportunities and Risks to 2021
Publisher's "Payments Landscape in Iran: Opportunities and Risks to 2021", report provides detailed analysis of market trends in the Iranian cards and payments industry. It provides values and volumes for a number of key performance indicators in the industry, including payment cards and cheques during the review-period (2013-17e).
The report also analyzes various payment card markets operating in the industry, and provides detailed…
India Retail Banking Market Dynamics 2018 by SBI ICICI, HDFC, Axis Bank, Bank of …
Margins among Indian banks remained high at 6.3% in 2017 in comparison to its peers China (2.8%) and Malaysia (2.6%). The average cost-to-income ratio remained at around 53% during 2013-17, marginally higher than China (50%) and Malaysia (51%). However, there remain large disparities in operating efficiencies within the market. The same is also true for profitability, with large disparities in return on assets figures. This is due to rising compliance,…

