


Press release
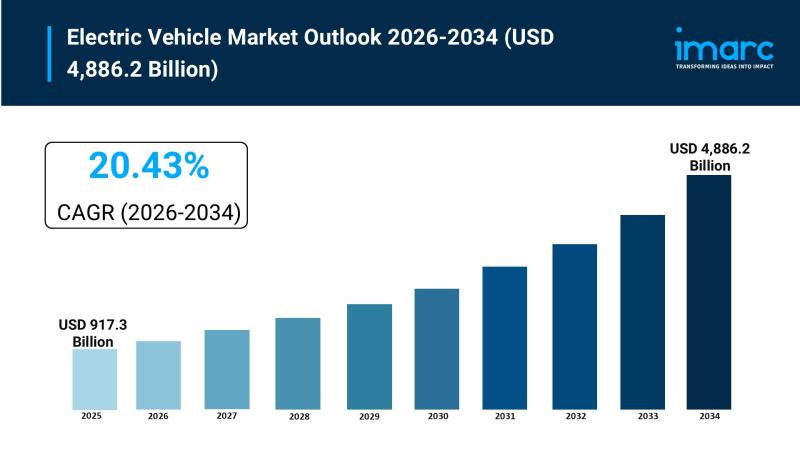
Electric Vehicle Market Size is Expected to Reach USD 4,886.2 Billion By 2034 | CAGR: 20.43%
Electric Vehicle Market
The market is experiencing strong growth momentum as electric mobility moves from an early-adopter proposition to a mainstream transportation choice across passenger, commercial, and shared mobility applications. Rising urbanization and growing concern over air quality are pushing governments to tighten emission regulations and set ambitious electrification targets, which in turn compels automakers to redirect capital toward electric platforms, battery manufacturing, and software-defined vehicle architectures. Simultaneously, improvements in lithium-ion chemistry, battery management systems, and ultra-fast charging technology are easing range anxiety and narrowing the ownership cost gap with conventional vehicles, while the integration of charging networks with renewable energy sources is reinforcing the sustainability credentials that attract environmentally aware buyers. Hybrid electric vehicles continue to bridge the transition for consumers who are not yet ready for a fully electric drivetrain, and strategic partnerships between automakers, battery suppliers, technology firms, and governments are accelerating the build-out of the ecosystem that sustains long-term demand.
Electric Vehicle Market at a Glance:
● Market Size (2025): USD 917.3 Billion
● Market Forecast (2034): USD 4,886.2 Billion
● Growth Rate (CAGR 2026-2034): 20.43%
● Leading Segments (2025): Hybrid electric vehicle (HEV) leads by propulsion type with around 61.3% share, slow charging leads by charging type with around 71.2% share, and passenger vehicles lead by vehicle type with around 73.5% share
● Dominant Region (2025): Asia Pacific, holding a market share of over 46.5%
● Study Period: Base year 2025, historical period 2020-2025, and forecast period 2026-2034
How AI is Reshaping the Future of the Electric Vehicle Market
● AI-Defined Intelligent Driving Systems Scaling Across Mass-Market Electric Vehicles: BYD announced on 28 May 2026 that more than 3.15 million vehicles on the road are fitted with its God's Eye intelligent driving assistance system, unveiled its first in-house 4nm automotive driving chip, the XUANJI A3, and made the LiDAR-equipped version optionally available across its entire lineup. Because a fleet of this size generates a continuous stream of real-world driving data for model iteration, AI-driven driver assistance is shifting from a premium differentiator to a standard expectation in entry-level electric vehicles, making software capability a decisive source of competitive advantage for volume manufacturers.
● Reinforcement Learning for Battery Management and Fast Charging Optimization: Researchers at Chalmers University of Technology in Sweden reported in a 2026 study published in IEEE Transactions on Transportation Electrification that a reinforcement learning charging strategy, which adapts fast-charging current to each battery's state of charge and state of health, extended simulated lithium-ion battery life by nearly 23% while charging time changed by only a few seconds. The method is designed to run within existing battery management software and could be delivered through over-the-air updates, although results are so far simulation-based and await physical validation, a pathway that could ease degradation concerns, support resale values, and reduce warranty exposure for automakers and fleet operators.
● AI-Native Vehicle Platforms and Autonomous Mobility: Tesla stated in its first quarter 2026 filing that it began pilot production of Cybercab while positioning FSD (Supervised) and Robotaxi among the AI-related products and services it delivers to customers. As manufacturers pair electric drivetrains with in-house AI compute and autonomy software, the electric vehicle is evolving into a software platform capable of generating recurring revenue and supporting shared and driverless mobility models, which will in turn influence battery sizing, charging demand, and fleet utilization patterns across urban markets.
Grab a sample PDF of this report: https://www.imarcgroup.com/electric-vehicles-market/requestsample
Electric Vehicle Market Trends and Drivers:
The global electric vehicle market is witnessing rapid expansion, fueled by the convergence of falling barriers to adoption, expanding charging infrastructure, and continuous improvement in battery performance that is repositioning electric mobility as a practical choice for everyday driving. Charging infrastructure has become the foundational enabler of this transition, with public charging points projected to rise from nearly 4 million in 2023 to almost 25 million by 2035 as governments, automakers, and private operators invest in highway fast-charging corridors, workplace and residential charging, and urban charging hubs. Ultra-fast charging technology is shortening charge times materially, while the integration of charging networks with renewable energy sources reinforces the sustainability credentials that attract environmentally conscious consumers. Battery advances are equally decisive, with global battery demand exceeding 750 GWh in 2023, a 40% increase from 2022 according to the International Energy Agency (IEA), including 415 GWh from China, as modern lithium-ion chemistries and advanced battery management systems extend driving range, build consumer confidence, and make electric vehicles viable as primary household vehicles.
Environmental sustainability and emission reduction remain the structural force that differentiates this technology cycle from earlier ones, as governments and citizens increasingly view cleaner transportation as essential to climate and air quality goals. According to the World Meteorological Organization (WMO), the atmospheric concentration of carbon dioxide has risen by 11.4% over the past 20 years, while electric vehicles produce zero tailpipe emissions and reduce harmful pollutants in dense urban environments. The adoption curve is now visible at global scale, as the IEA reports that electric car sales, covering battery electric and plug-in hybrid models, grew by 20% to exceed 20 million units in 2025, equal to about one quarter of all new cars sold worldwide, with China selling more than 13 million units and Europe recording growth of more than 30%. Adoption is also broadening beyond the three largest markets, with sales elsewhere reaching 2 million units in 2025 compared with 1.3 million in 2024, and with Southeast Asia more than doubling its annual sales to reach a sales share of nearly 20%, confirming that electric mobility is becoming a genuinely global category rather than a regional policy story.
Supportive government policies and incentives continue to underpin adoption while also shaping where and how fast the market grows. Tax credits, subsidies, reduced registration fees, and access to carpool lanes have been introduced across many economies, alongside strict emission regulations and ambitious electrification targets that compel automakers to invest heavily in electric production. In India, supportive policies and incentives contributed to a 16% rise in EV registrations in H1 2024 compared with H1 2023, supported by 16,344 public charging stations and 10,756 fast charging points according to PIB, while electric vehicles accounted for 22.7% of new car registrations across Europe in 2023 according to the European Environment Agency, and electric cars reached almost 55% of new car sales in China in 2025 according to the IEA. At the same time, policy frameworks are evolving, with incentives being phased down in some mature markets and trade and technical standards becoming more influential, a shift that makes the global regulatory, trade, and policy landscape a critical determinant of regional demand trajectories.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=1786&flag=E
Global Regulatory, Trade, and Sustainability Landscape Shaping Demand:
● International Energy Agency (IEA), Global EV Outlook 2026: The IEA's May 2026 outlook expects global electric car sales to reach around 23 million in 2026, equal to about 28% of total car sales, after sales topped 20 million in 2025, and reports that electric cars accounted for at least 10% of new car sales in around 40 countries. Even without new policy announcements, the global electric vehicle fleet is projected to grow more than sixfold by 2035 from 2025 levels, to as many as 510 million vehicles, excluding electric two- and three-wheelers, underscoring the long-term scale of charging, grid, and battery supply chain investment required.
● United Nations Economic Commission for Europe (UNECE), UN Global Technical Regulation No. 22: Published in the UN Global Registry in March 2022, GTR No. 22 sets harmonized minimum performance requirements for in-vehicle battery durability in electrified light-duty vehicles, requiring a minimum state of certified energy of 80% over 5 years or 100,000 km and 70% over 8 years or 160,000 km. By giving regulators and consumers a common benchmark for battery longevity, the regulation supports warranty design, resale value confidence, and cross-border vehicle certification, and UNECE has noted that the European Union and the United States made legislative proposals to transpose it into their own frameworks.
● World Trade Organization (WTO) and EU Trade Defence Measures: Trade has become a defining feature of electric vehicle supply chains, with approximately one quarter of electric cars produced in 2025 traded between countries according to the IEA. The European Union confirmed definitive countervailing duties of 8% to 35.3% on battery electric vehicles imported from China for five years from October 2024, on top of its standard 10% car tariff, prompting a WTO dispute initiated by China. In January 2026 the European Commission issued guidance on minimum price undertakings as an alternative to duties, and on 10 February 2026 it accepted its first undertaking, for the CUPRA Tavascan built by Volkswagen (Anhui), signaling a more managed pathway for cross-border trade.
● International Energy Agency (IEA), Regional Policy Divergence in Early 2026: Global electric car sales fell about 8% year on year in the first quarter of 2026 following policy changes in China and the United States, yet the IEA reports that sales rose by close to 30% in Europe, 80% in Asia Pacific excluding China, and 75% in Latin America, while global electric truck sales more than doubled in 2025. The pattern shows how incentive design, rather than underlying consumer interest alone, is increasingly steering the geographic mix of electric vehicle demand.
Key Government Schemes and Policy Programs Supporting the Industry:
● India, PM E-DRIVE Scheme: The Ministry of Heavy Industries' PM Electric Drive Revolution in Innovative Vehicle Enhancement scheme carries a fund-limited outlay of 10,900 crore, including Rs. 4,391 crore for 14,028 electric buses, Rs. 2,000 crore for public charging stations, Rs. 500 crore for e-ambulances, and Rs. 780 crore for upgrading testing agencies. Originally notified for two years from October 2024, the scheme was extended in August 2025 to 31 March 2028 within the same outlay, supporting India's push to build domestic electric vehicle manufacturing.
● United States, NEVI Program and Federal Credit Changes: The Bipartisan Infrastructure Law allocated USD 5 Billion to the National Electric Vehicle Infrastructure (NEVI) Formula Program over fiscal years 2022 to 2026, complemented by USD 2.5 Billion in competitive Charging and Fueling Infrastructure grants. The program was suspended in February 2025 and resumed following court action and new FHWA guidance, with USD 885 million apportioned for fiscal year 2026, although Congress rescinded just over USD 503 million across 30 states and territories in January 2026. On the demand side, the federal USD 7,500 new electric vehicle credit and USD 4,000 used electric vehicle credit ended for vehicles acquired after 30 September 2025 under the One Big Beautiful Bill Act, shifting support toward state-level incentives.
● European Union, Automotive Package and CO2 Standards for Cars and Vans: Current rules require a 55% reduction in new car CO2 emissions by 2030 and 100% by 2035 against a 2021 baseline, but on 16 December 2025 the European Commission proposed lowering the 2035 target to 90%, with the remaining 10% compensated through EU-made low-carbon steel or e-fuels and biofuels, which would allow plug-in hybrids and range extenders beyond 2035. The package also includes super credits for small, affordable electric cars made in the EU, and the International Council on Clean Transportation estimates the change could mean between 3 and 2.6 million fewer electric vehicles sold each year, with the proposal under review by the European Parliament and Council.
● China, New Energy Vehicle Purchase Tax Policy: China has moved from a full purchase tax exemption, capped at RMB 30,000 per passenger vehicle in 2024 and 2025, to a 50% reduction from 1 January 2026 to 31 December 2027, capped at RMB 15,000 per vehicle, equal to an effective tax rate of 5%. The Ministry of Finance estimated that exemptions and reductions across 2024-2027 would total RMB 520 billion, and China introduced a 2% consumption tax on lithium-ion batteries from September 2026, rising to 4% in September 2027, as the market transitions from subsidy-led to demand-led growth.
● United Arab Emirates, National Electric Vehicle Strategy: The strategy aims for electric vehicles to make up 50% of all vehicles on the road by 2050, while tax exemptions and reduced registration fees across the region, alongside Saudi Arabia's Vision 2030, are supporting investment in green mobility technologies and charging networks across the Middle East and Africa.
Electric Vehicle Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Component:
● Battery Cells and Packs
● On-Board Charger
● Fuel Stack
Battery cells and packs anchor the component landscape, propelled by continuous gains in energy density and driving range and by rising research and development investment, with supportive government policies and expanding electric vehicle demand sustaining the need for highly efficient battery solutions. On-board chargers are advancing alongside the build-out of public and private charging networks, with technologies that improve charging efficiency, reduce charging times, and enable seamless integration of charging systems into vehicles shaping segment growth, while fuel stacks benefit from the promise of hydrogen fuel cell technology as a clean energy source for future electric vehicles, supported by government research investment.
Breakup By Charging Type:
● Slow Charging
● Fast Charging
Slow charging accounts for the largest charging type segment with around 71.2% share in 2025, driven by lower cost and easier installation that appeal to home users and small-scale charging stations, lower power demand that eases pressure on the electrical grid without major infrastructure upgrades, and suitability for overnight and workplace charging that preserves battery lifespan and efficiency, while public policies encouraging energy conservation further support the segment.
Breakup By Propulsion Type:
● Battery Electric Vehicle (BEV)
● Fuel Cell Electric Vehicle (FCEV)
● Plug-In Hybrid Electric Vehicle (PHEV)
● Hybrid Electric Vehicle (HEV)
Hybrid electric vehicles lead the propulsion type segment with around 61.3% share in 2025, supported by strict emission regulations, lower emissions and higher fuel efficiency that bridge conventional internal combustion engines and fully electric vehicles, advances in hybrid powertrain systems that improve performance and driving experience, rising fuel prices that push consumers toward economical alternatives, and government incentives and subsidies for hybrid adoption.
Breakup By Vehicle Type:
● Passenger Vehicles
● Commercial Vehicles
● Others
Passenger vehicles hold the largest vehicle type share at around 73.5% in 2025, driven by evolving consumer preferences, rapid urbanization and rising disposable incomes in emerging economies that fuel demand for personal mobility, technological advances such as connected car features and autonomous driving capabilities, stringent emission regulations that encourage automakers to invest in electric and hybrid passenger cars, favorable financing options, and the growing popularity of ride-sharing and car-sharing services that is changing how consumers approach vehicle ownership.
Breakup By Region:
● Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
● Europe (Norway, Netherlands, Sweden, United Kingdom, France, Germany, Others)
● North America (United States, Canada)
● Middle East and Africa (Turkey, Saudi Arabia, Iran, United Arab Emirates, Others)
Latin America (Brazil, Mexico, Argentina, Colombia, Others)
Asia Pacific dominates the global electric vehicle market with the largest regional share of over 46.5% in 2025, driven by stringent emission regulations and ambitious electrification targets, rapid urbanization and congestion and air quality concerns, advances in battery technology and research investment that improve performance and affordability, supportive tax incentives, subsidies, and infrastructure development, a growing middle class with rising disposable income, and strategic partnerships among automakers, technology firms, and governments that are expanding charging infrastructure across China, Japan, India, South Korea, Australia, and Indonesia. China alone sold more than 13 million electric cars in 2025 according to the IEA, reinforcing the region's position as the center of global production and demand.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the electric vehicle market with detailed profiles of all major companies, including:
● BYD Company Limited
● BMW Group
● Chevrolet (General Motor Company)
● Ford Motor Company
● Hyundai Motor Group
● Mercedes-Benz Group AG
● Mitsubishi Motors Corporation
● Nissan Motor Corporation
● Tesla, Inc.
● Toyota Motor Corporation
● Volkswagen Group
Leading players are accelerating advances across manufacturing, infrastructure, and innovation, expanding production capacities, streamlining supply chains, launching SUVs, trucks, and luxury models, and collaborating with battery technology firms on solid-state and high-energy-density batteries. BYD sold 4,602,436 new energy vehicles in 2025, including 2,256,714 battery electric passenger vehicles that surpassed Tesla's 1,636,129 deliveries for the first time, while exporting 1,046,083 vehicles overseas, an increase of about 150% from 2024. Volkswagen Group delivered 438,500 battery electric vehicles in the first half of 2026 and holds a 21% share of the Western European battery electric market, while Ford is investing approximately USD 5 Billion across its Louisville Assembly Plant and BlueOval Battery Park Michigan to build a midsize electric pickup targeted at about USD 30,000 on its Universal EV Platform from 2027.
Market Concentration Analysis:
● Consolidation Pattern: Volume is concentrating around Chinese manufacturers, who supplied about 60% of global electric car sales in 2025 against roughly 15% each for European and North American automakers according to the IEA, and just five models accounted for about 20% of global battery electric car sales, led by the Tesla Model Y at nearly 8% and the Tesla Model 3 at 3.6%. S&P Global Ratings has assessed that intense price competition and excess capacity in China point toward meaningful consolidation between 2027 and 2030, with the top three to five EV makers increasingly leaving competitors behind.
● Dominant Leader Versus a Fragmented Field: BYD remains the clear scale leader, holding 5% of China's new energy vehicle retail market in July 2026 and 27.2% for full-year 2025, yet the next players are far smaller, with Geely at 11.1%, Leapmotor at 8.8%, and Changan at 6.3% in July 2026 according to CPCA data. BYD's lead is also being tested at home, as its January-July 2026 China NEV retail sales were down 35.6% year on year, even as it targets 1.3 million overseas sales in 2026.
● Regional Champions: Volkswagen Group commands a 21% share of the Western European battery electric market after 377,000 European deliveries in the first half of 2026, in a region where electric car sales rose more than 30% to 2 million units in 2025 according to the IEA, while BYD is expanding from its home market with Europe, North America, and ASEAN each accounting for about one third of its overseas sales.
What Does The Full Report Cover?
If you are tracking the electric vehicle market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
● Complete market sizing with revenue and unit volume forecasts, reported in Billion USD and Million Units, covering the historical period 2020-2025 and the full forecast period 2026-2034
● Industry catalysts, challenges, and opportunities analysis with segment-wise historical and predictive market assessment across component, charging type, propulsion type, vehicle type, and regional markets
● Sub-segment breakdowns for battery cells and packs, on-board charger, fuel stack, slow charging, fast charging, battery electric, fuel cell electric, plug-in hybrid, and hybrid electric vehicles, and passenger and commercial vehicles
● Country-level data for China, Japan, India, South Korea, Australia, Indonesia, Norway, the Netherlands, Sweden, the United Kingdom, France, Germany, the United States, Canada, Turkey, Saudi Arabia, Iran, the United Arab Emirates, Brazil, Mexico, Argentina, and Colombia
● Competitive profiles of leading companies, including the 11 manufacturers listed above, with strategic landscape assessment
● Porter's Five Forces analysis assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution on the electric vehicle industry
● Latest innovation trends covering ultra-fast charging, solid-state and high-energy-density batteries, hydrogen fuel cell technology, and renewable-integrated charging networks shaping market competition and consumer preference across key regional markets
Recent News and Developments in Electric Vehicle Market
● September 2026: BMW raised iX3 production at its Debrecen plant in Hungary from two to three shifts to meet demand, with orders reaching about 100,000 in Europe and the 50,000th unit built at the end of July 2026, nine months after series production began. The first Neue Klasse model supports 400 kW charging that can add around 231 miles of range in 10 minutes, with US deliveries beginning in September 2026.
● July 2026: Volkswagen Group reported 438,500 battery electric vehicle deliveries worldwide in the first half of 2026, down 5.8%, while European deliveries rose 8.4% to 377,000 units, lifting its Western European battery electric share from 20% to 21%. The group said its European battery electric order book rose by more than 50% and that its Electric Urban Car Family, including the ID. Polo, Skoda Epiq, and Cupra Raval, had drawn more than 54,000 orders.
● July 2026: Tesla delivered 480,126 vehicles in the second quarter of 2026, up about 25% from 384,122 a year earlier and 34% from 358,023 in the first quarter, its strongest second quarter on record. The company produced 451,758 vehicles in the quarter and deployed 13.5 GWh of energy storage products.
● January 2026: BYD reported 2025 sales of 4,602,436 new energy vehicles, including 2,256,714 battery electric passenger vehicles that surpassed Tesla's 1,636,129 deliveries for the first time, and overseas sales of 1,046,083 units, up about 150% from 2024. The company set a target of 1.3 million overseas sales for 2026, with Europe, North America, and ASEAN each accounting for roughly one third of its overseas volumes.
● November 2025: General Motors began production of the new Chevrolet Bolt EV at its Fairfax plant in Kansas on 10 November, featuring a 65 kWh lithium iron phosphate battery supplied by CATL, an estimated range of 255 miles, and 150 kW fast charging. The launch came alongside a USD 1.6 Billion EV-related charge disclosed with third-quarter results, including USD 1.2 Billion tied to EV capacity changes.
● August 2025: Ford announced an approximately USD 5 Billion investment, including nearly USD 2 Billion at its Louisville Assembly Plant and USD 3 Billion at BlueOval Battery Park Michigan, to launch its Universal EV Platform, starting with a midsize electric pickup targeted at about USD 30,000 for customers in 2027. The platform uses about 20% fewer parts and enables assembly up to 40% faster than the plant's current vehicles, creating or securing nearly 4,000 jobs across the two sites.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
● What is the current global electric vehicle market size and what is its projected value?
● Which charging type, propulsion type, and vehicle type segments hold the largest shares in the global electric vehicle market?
● What are the key drivers of global electric vehicle market growth?
● Which region dominates the global electric vehicle market and why?
● How are battery technology advances, charging infrastructure expansion, and shifting government incentives reshaping product development and competitive strategies in the electric vehicle industry?
● Who are the top companies in the global electric vehicle market and what are their competitive strategies?
● What are the investment and market entry opportunities across battery, charging, hybrid, fuel cell, and commercial electric vehicle segments?
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Electric Vehicle Market Size is Expected to Reach USD 4,886.2 Billion By 2034 | CAGR: 20.43% here
News-ID: 4649365 • Views: …
More Releases from IMARC Groeup
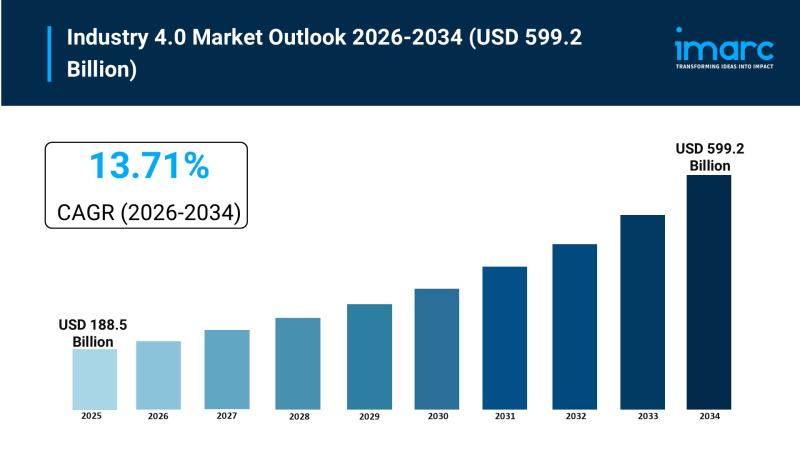
Industry 4.0 Market Size to Hit USD 599.2 Billion by 2034 | With a 13.71% CAGR
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Industry 4.0 market. The global Industry 4.0 market size was valued at USD 188.5 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 599.2 Billion by 2034, exhibiting a CAGR of 13.71% from 2026-2034, driven by rising demand for smart manufacturing and automation, rapid advancements in…
Binding Wire Manufacturing Plant Setup Cost 2025: CapEx/OpEx Analysis with Profi …
Binding wire is a thin, flexible, and durable steel wire used primarily in construction to tie reinforcement bars (rebar) together, ensuring structural stability during concrete placement. Manufactured from mild steel and sometimes galvanized for corrosion resistance, binding wire offers excellent ductility and ease of use. It is widely applied in construction, masonry, agriculture, and packaging industries due to its strength, pliability, and reliability.
A binding wire manufacturing plant requires raw material…
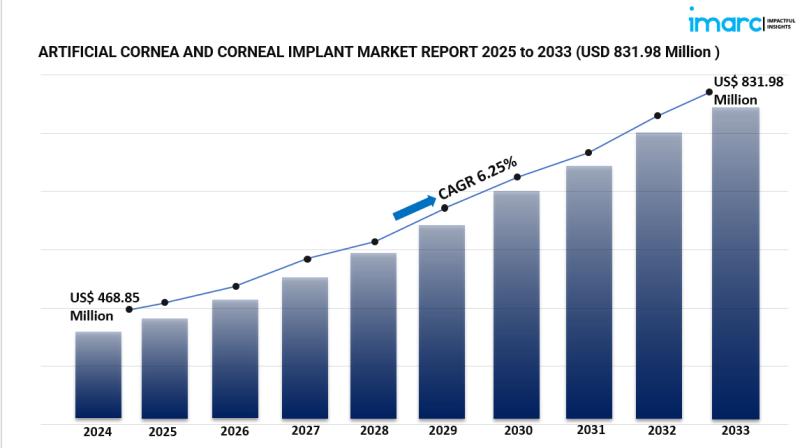
Emerging Innovations Transforming the Artificial Cornea and Corneal Implant Mark …
Market Overview
The global artificial cornea and corneal implant market is experiencing significant growth, primarily driven by the rising incidence of corneal disorders and continuous advancements in ophthalmic technologies. In 2024, the market was valued at USD 468.85 million and is anticipated to reach USD 831.98 million by 2033, registering a CAGR of 6.25% during 2025-2033.
This expansion is supported by the increasing prevalence of corneal blindness, limited availability of donor corneas,…
Polyacrylamide Production Plant: All-in-One Report Details Unit Setup, Costs, an …
Polyacrylamide is a white, water-soluble polymer with the chemical formula (C3H5NO)n, commonly used in water treatment, oil recovery, paper manufacturing, and mining operations. It functions primarily as a flocculant or coagulant, aiding in the aggregation of suspended particles in liquid solutions. Available in both anionic and cationic forms, polyacrylamide plays a critical role in improving process efficiency and environmental compliance across multiple industries.
Setting up a Polyacrylamide production plant requires the…
More Releases for Vehicle
Transformative Trends Impacting the Vehicle-to-Vehicle (V2V) Communication Marke …
Stay ahead with our updated market reports featuring the latest on tariffs, trade flows, and supply chain transformations.
How Large Will the Vehicle-to-Vehicle (V2V) Communication Market Size By 2025?
The size of the vehicle-to-vehicle (V2V) communication market has seen significant expansion in the most recent years. The market is projected to surge from $24.28 billion in 2024 to $27.1 billion in 2025, exhibiting a compound annual growth rate (CAGR) of 11.6%. The…
Electric Vehicle Motor Market : Battery Electric Vehicle, Plugin Hybrid Vehicle, …
According to the report published by Allied Market Research, the global electric vehicle motor market generated $5.5 billion in 2021, and is estimated to reach $34.4 billion by 2031, witnessing a CAGR of 20.3% from 2022 to 2031.
Asia-Pacific is expected to dominate the global electric vehicle motor market. An increase in vehicle population and a rise in vehicle standards fuel the growth of the Asia-Pacific market. Moreover, various technological…
Truck Platooning Market : Vehicle-to-infrastructure (V2I), Vehicle-to-vehicle (V …
According to a recent report published by Allied Market Research, titled,"Truck Platooning Market by Technology, Platooning Type, and Communication Technology: Global Opportunity Analysis and Industry Forecast, 2018 - 2025,"the global truck platooning market size was valued at $500.9 million in 2017, and is projected to reach $4,590.3 million by 2025, registering a CAGR of 32.4% from 2018 to 2025.
To Explore More, Download Sample Report: https://www.alliedmarketresearch.com/request-sample/5245
Global truck platooning market is segmented…
Electric Vehicle Motor Market : Battery Electric Vehicle, Plugin Hybrid Vehicle, …
According to a new report published by Allied Market Research, titled, "Electric Vehicle Motor Market," The global electric vehicle motor market was valued at $5.5 billion in 2021, and is projected to reach $34.4 billion by 2031, growing at a CAGR of 20.3% from 2022 to 2031.
Asia-Pacific is expected to dominate the global electric vehicle motor market. An increase in vehicle population and a rise in vehicle standards fuel the…
Electric Vehicle Power Inverter Market : Hybrid Vehicle, Plug in Hybrid Vehicle, …
The electric vehicle power inverter market was valued at $8.67 billion in 2021, and is estimated to reach $22.25 billion by 2031, growing at a CAGR of 10.4% from 2022 to 2031.
Download Sample Report at https://www.alliedmarketresearch.com/request-sample/9122
Factors that drive the growth of the electric vehicle power inverter market are increase in demand for electric vehicles, proactive government initiatives for the development of electric vehicle, and surge in demand for low-emission and…
Truck Platooning Market : Vehicle-to-infrastructure (V2I), Vehicle-to-vehicle (V …
The global truck platooning market size was valued at $500.9 million in 2017 and is projected to reach $4590.3 million by 2025, registering a CAGR of 32.4% from 2018 to 2025 by Technology (Adaptive Cruise Control (ACC), Blind Spot Warning (BSW), Global Positioning System (GPS), Forward Collision Warning (FCW), Lane Keep Assist (LKA), and Others), Platooning type (Driver-Assistive Tuck Platooning (DATP) and Autonomous Truck Platooning), and Communication Technology (Vehicle-to-infrastructure (V2I),…

