


Press release
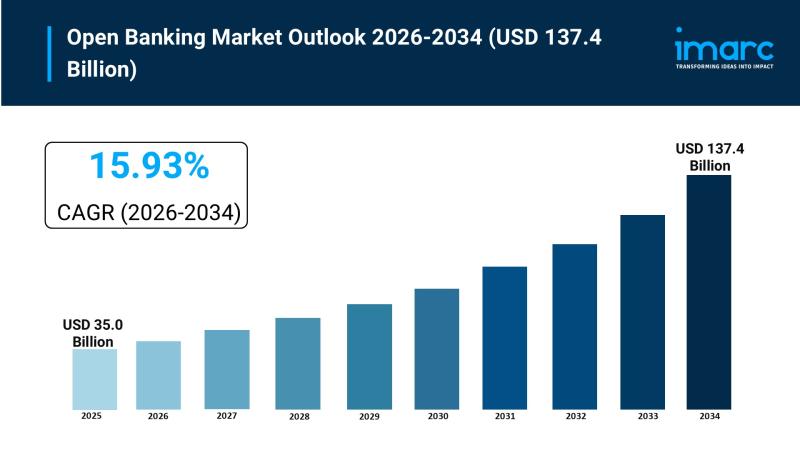
Open Banking Market Size Worth USD 137.4 Billion Globally by 2034 at a CAGR of 15.93%
Open Banking Market Graph 2026-2034
The market is on a sustained growth path because open banking has moved from a regulatory experiment to core financial infrastructure. Regulation such as PSD2 in Europe created the first wave of demand by requiring banks to open APIs to authorized third parties. Advances in API technology now allow banks and fintech firms to exchange customer data securely, which has led to new payment, lending, and personal finance services. Banking and capital markets remain the largest services segment, on-premises deployment leads because financial institutions prioritize security and control over sensitive data, and app markets are the leading distribution channel as consumers seek convenience and personalization. Europe holds the largest regional position, while India and Brazil are building national-scale open finance networks that broaden the addressable market well beyond its regulatory origins.
Grab a sample PDF of this report: https://www.imarcgroup.com/open-banking-market/requestsample
Open Banking Market at a Glance:
• Market Size 2025: USD 35.0 Billion
• Forecast Size 2034: USD 137.4 Billion
• Growth Rate 2026-2034: CAGR of 15.93%
• Leading Service: Banking and Capital Markets
• Leading Deployment: On-Premises
• Leading Distribution Channel: App Markets
• Dominant Region: Europe
How AI is Reshaping the Future of the Open Banking Market
Conversational AI Connected to Live Bank Data: Plaid and OpenAI announced a partnership on May 15, 2026 that lets ChatGPT users link their bank accounts to ChatGPT via Plaid. Plaid connects consumers' accounts from over 12,000 providers to more than 7,000 fintech providers, so the consent layer built for open banking is becoming the trusted data pipe for AI assistants. It also gives AI agents a regulated route to consented account data instead of screen scraping.
Personalized Advice from Open Banking Analytics: Personalization is a major demand driver, and the European Central Bank notes that more than 60% of consumers want personalized financial services. Fintonic's OpenInsights platform applies analytics to open banking data so institutions can improve decisions, tailor the customer experience, and find new revenue opportunities. AI and machine learning are increasingly the engines behind money management tools, better borrowing terms, and investment recommendations.
Cash-Flow Underwriting on Consented Data: India's Account Aggregator ecosystem shows how consented data feeds credit models at scale. It has enabled loans worth ₹1.6 lakh crore across 1.8+ crore loan accounts, and industry body Sahamati claims lender transaction costs can fall by 20 to 25 per cent on the framework. Verified bank data replaces paperwork in lending decisions, and machine-learning risk models can then learn from a far richer dataset.
Open Banking Market Trends and Drivers:
Regulatory support is the foundational driver, and the UK shows how quickly adoption compounds once the rails exist. Open Banking now supports more than 19 million active user connections and over 40 million payments every month in the UK. In June alone the ecosystem recorded 2.81 billion API calls, the highest monthly volume to date, and it has passed one billion payments and 100 billion API calls since launch. The mix of use is also shifting from viewing data to moving money: payment initiation users now account for 55% of users, against 75% for account information users at the outset.
The structural differentiator is that open banking is being built as public infrastructure in several economies at once. The European Banking Authority reports almost 2,500 third-party providers registered under PSD2, and the European Commission notes over 9,000 fintech startups in the European Union. Brazil's Open Finance has more than 154 million active consents and 100 million connected clients. India's Account Aggregator framework has more than 2.88 billion financial accounts enabled to share data. This breadth of public-sector adoption is what lifts the market beyond a single regulation-driven region.
The next driver is the move from data sharing to payments, and it sets up a more complex policy landscape covering Europe, the United Kingdom, the United States, India, and Brazil, detailed further below. Variable recurring payments already account for 7.73 million of the UK's monthly payments, and pay-by-bank is competing directly with card rails at checkout. With that shift come stronger fraud liability rules, permission dashboards, and API performance obligations, all of which raise the technology bar for banks and third-party providers.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=6327&flag=E
Global Regulatory, Trade, and Sustainability Landscape Shaping Demand:
Standard-Setting Bodies and Data Portability: The CFPB recognized the Financial Data Exchange (FDX) as the first standard-setting body under the 1033 framework, with a five-year recognition. Industry-led technical standards are becoming the common language that lets banks and fintech firms connect without bilateral integrations.
Fraud Liability and Payment Safety: Under the EU's PSR text, payment service providers must check that the payee name matches the IBAN and warn of discrepancies, and APP fraud is treated as an unauthorised transfer with full reimbursement to the payer. In the UK, the Open Banking Payments Fraud Monitor draws on account providers representing more than 60% of Open Banking payment volumes. Fraud performance is becoming a competitive and compliance metric for open banking payments.
Consent Design and Data Protection: Consent rules differ sharply by market. In Brazil the maximum duration of data sharing consent is 365 days, compared with 90 days in the UK. Institutions in strict data protection jurisdictions such as those covered by GDPR often prefer on-premises deployment, which explains that deployment model's lead in the report.
Data Access Pricing and Commercial Terms: The economics of bank data access are being renegotiated. After JPMorgan moved to a fee model, Plaid's added costs could be as high as USD 300 Million, per Forbes, yet the company absorbed them rather than passing them to consumers. How access is priced will shape which fintech business models scale.
Key Government Schemes and Policy Programs Supporting the Industry:
India, RBI Account Aggregator Framework: The framework has delivered over 45 crore cumulative consents and more than 500 crore data fetches, and processes over 7 lakh consents daily. Some 284.6 million accounts have been linked by users. In June, the RBI recognised Sahamati as the Self-Regulatory Organisation for the ecosystem, the first Indian SRO covering a cross-sectoral framework, which signals a mature governance phase.
United States, CFPB Personal Financial Data Rights Rule (Section 1033): April 1, 2026 was the first scheduled compliance deadline for the largest data providers, but a federal court enjoined the CFPB from enforcing the rule while it reconsiders it. The Bureau is reviewing whether the rule should be modified or withdrawn. Meanwhile, many large banks have continued building compliant APIs voluntarily, so US market-led open banking keeps moving without a mandate.
European Union, PSD3 and Payment Services Regulation: The European Parliament and the Council reached provisional political agreement in November 2025, and the Council published the final compromise texts on 23-24 April 2026. Account servicing providers must maintain a dedicated secure API and give users dashboards to monitor, withdraw, or re-establish data access. PSD3 will require national transposition within 18 months of entry into force, so the shift from PSD2 lands soon.
United Kingdom, Open Banking Limited and UK Payments Initiative: Monthly activity is over 19 million active user connections and 40 million payments. Commercial Variable Recurring Payments Wave 1 launched via the UK Payments Initiative across utilities, regulated finance, government and rail. EY analysis found that a fully unlocked open banking regime could add £43bn a year to the British economy.
Brazil, Banco Central Open Finance and Pix Integration: The ecosystem supports 154 million active consents and 100 million connected clients, and generates more than 5 billion weekly communications between institutions. The Jornada Sem Redirecionamento, which lets users authorize Pix payments without leaving the initiating app, became mandatory for all account-holding institutions in the Pix arrangement, pushing payment initiation into everyday use.
Open Banking Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Services:
• Banking and Capital Markets
• Payments
• Digital Currencies
• Value Added Services
Banking and capital markets represent the largest segment, driven by customer preference, technology development, and government regulation such as PSD2. Closer cooperation between established banks and fintech start-ups is producing better services and wider financial inclusion. The UK Competition and Markets Authority has estimated that open banking could be worth customers up to £7.2 billion.
Breakup By Deployment:
• Cloud-based
• On-premises
On-premises holds the largest share, reflecting financial institutions' preference for security, control, and compliance when handling sensitive data, especially under strict frameworks such as GDPR. The European Banking Authority notes that security-focused providers often choose in-house processing for maximum data safety and customization.
Breakup By Distribution Channel:
• Bank Channels
• App Markets
• Distributors
• Aggregators
App markets lead the distribution channel segment. The UK Competition and Markets Authority reported about 2 million log-ins per day, twice the previous year's figure. Regulations such as PSD2 and UK standards require secure data sharing and interoperable systems, which lets developers build everything from simple budgeting tools to full financial management apps.
Breakup By Region:
• North America (United States, Canada)
• Asia-Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
• Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
• Latin America (Brazil, Mexico, Others)
• Middle East and Africa
Europe leads the global market, powered by PSD2, which requires banks to open data to third parties with customer consent. The European Banking Authority recorded almost 2,500 registered third-party providers, and GDPR reinforces the trusted data sharing that consumer confidence depends on. Asia-Pacific and Latin America are scaling through national frameworks such as India's Account Aggregator system and Brazil's Open Finance, while North America relies largely on market-led adoption.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the open banking market with detailed profiles of key companies, including:
• Banco Bilbao Vizcaya Argentaria, S.A
• Crédit Agricole CIB
• Finastra
• GoCardless Ltd
• Mambu
• Plaid Inc.
• Qwist GmbH
• Revolut Ltd
• Societe Generale
• Tink AB
• Token.io Ltd
• TrueLayer Ltd
Key players are using technology and partnerships to build API ecosystems that support secure data sharing and new financial products. Plaid reached a USD 8 billion valuation in its latest funding round, up from USD 6.1 billion the year before. GoCardless processes more than USD 35 billion of payments each year across 30+ countries. Tink connects to over 3,400 banks across Europe through a single open banking API.
Market Concentration Analysis:
Fragmented Aggregation Layer with Network-Owned Anchors: One estimate holds that the top five providers account for about one-quarter of total revenue, which points to a fragmented market. Payment networks have set anchors: Visa bought Tink for about USD 2.2 billion, and Mastercard owns Finicity, while pure-play aggregators such as Plaid and MX hold a large share of US open banking technology.
Vertical Expansion into Credit and Recurring Payments: Providers are widening their scope through acquisitions. TrueLayer acquired Dutch fintech In3 following its purchase of Swedish paytech Zimpler, and its first credit product will be buy now pay later on its Pay by Bank network. Consolidation is moving from data connectivity toward payments, credit, and billing.
Public Infrastructure Creating Regional Champions: In India and Brazil, state-backed frameworks and central-bank rules shape competition more than private aggregators do. That contrasts with the US, where a court-stayed federal rule leaves market-led players such as Plaid to set the pace, and with the UK and EU, where regulation is turning bank APIs into a competitive baseline.
What Does The Full Report Cover?
If you are tracking the open banking market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
• Complete market sizing with revenue forecasts covering the full 2020-2034 projection period
• Analysis of drivers, challenges, and opportunities, including regulatory support, API advances, system integration complexity, and regulatory variances
• Sub-segment breakdowns across services, deployment, and distribution channel with detailed analysis of each
• Country-level data for the United States, Canada, Germany, France, the United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, and Mexico
• Competitive and key company profiles with a strategic landscape assessment
• Porter's Five Forces analysis and mapping of the leading and fastest-growing regional markets
• Investment and growth opportunity mapping across advanced security solutions, Banking-as-a-Service platforms, and global interoperability standards
Recent News and Developments in Open Banking Market
July 2026: UK open banking surpassed one billion payments and 100 billion API calls. June recorded 2.81 billion API calls, 40.16 million payments, and 7.73 million sweeping variable recurring payments, up 6.7% month on month.
June 2026: The Reserve Bank of India recognised Sahamati as the Self-Regulatory Organisation for India's Account Aggregator ecosystem. The ecosystem has delivered over 45 crore consents and nearly 3.8 crore financial products and services in the latest fiscal year.
May 2026: TrueLayer acquired Dutch fintech In3 to bring credit onto its Pay by Bank network, ahead of the first wave of FCA regulation for UK deferred payment credit taking effect on 15 July 2026.
May 2026: Plaid and OpenAI announced a partnership allowing ChatGPT users to link their bank accounts via Plaid, extending open banking connectivity into consumer AI assistants.
March 2026: GoCardless announced that more than one in three customers have taken open banking payments through its platform, with 37,323 open banking customers since the launch of Instant Bank Pay.
February 2026: Plaid closed a funding round valuing it at USD 8 billion, up from USD 6.1 billion in April 2025, which was reported as a liquidity round for employees and shows renewed investor confidence in open finance infrastructure.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
• What is the current global open banking market size and what is its projected value?
• Which services, deployment, and distribution channel segments hold the largest share in the global open banking market?
• What are the key drivers of global open banking market growth?
• Which region dominates the global open banking market and why?
• How are PSD3, national data-sharing frameworks, and fraud liability rules reshaping open banking investment worldwide?
• Who are the top companies in the global open banking market and what are their competitive strategies?
• What are the investment and market entry opportunities across advanced security solutions, Banking-as-a-Service platforms, and global interoperability standards?
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Open Banking Market Size Worth USD 137.4 Billion Globally by 2034 at a CAGR of 15.93% here
News-ID: 4648371 • Views: …
More Releases from IMARC Group
Succinic Acid Manufacturing Plant Setup Cost, Feasibility Study 2026: Business P …
Setting up a succinic acid production plant in 2026 requires clarity on a few core variables: feedstock choice, production capacity, capital investment, operating cost structure, and profitability under prevailing market conditions. This feasibility study covers the succinic acid production plant cost, and the machinery and raw materials needed, driven by rising demand for bio-based platform chemicals, increasing use in biodegradable polymers, and growing adoption in personal care, food, and industrial…
Steel Wheel Rim Plant Setup Cost 2026: Market Feasibility Study, Manufacturing I …
Setting up a steel wheel rim manufacturing plant in 2026 requires clarity on a few core variables: raw material choice, production capacity, capital investment, operating cost structure, and profitability under prevailing policy conditions. This feasibility study covers the steel wheel rim manufacturing plant cost, and the machinery and raw materials needed, driven by increasing demand in the automotive sector, growth in commercial and passenger vehicles, and rising applications in heavy…
Sodium Silicate Plant Setup Cost 2026: Production Process, Machinery, Investment …
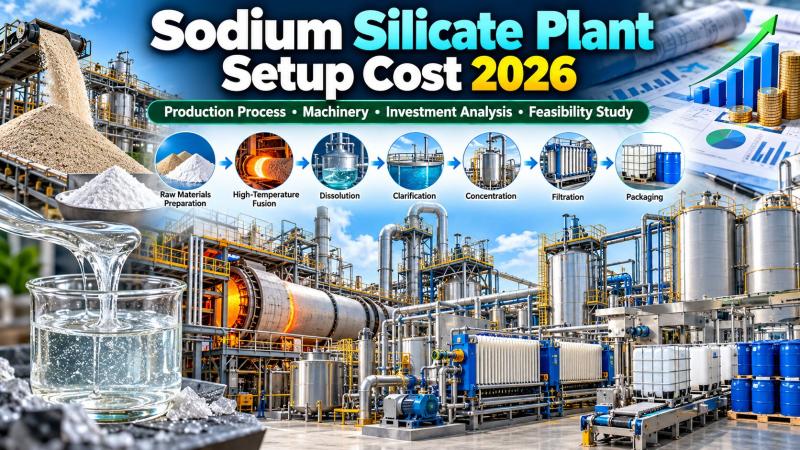
Setting up a sodium silicate production plant in 2026 involves assessing raw material availability, production capacity, manufacturing technology, machinery requirements, capital investment, operating expenses, and overall project feasibility. This feasibility study covers the sodium silicate production plant cost, along with the machinery and raw materials required for production. Sodium silicate is widely utilized in detergents, construction chemicals, pulp and paper processing, water treatment, textiles, and specialty chemical formulations. Its broad…
Aluminum Profiles Manufacturing Plant Setup Cost 2026: Feasibility Study Report, …
Setting up an aluminum profiles manufacturing plant in 2026 requires clarity on a few core variables: feedstock choice, production capacity, capital investment, operating cost structure, and profitability under prevailing demand conditions. This feasibility study covers the aluminum profiles manufacturing plant cost, and the machinery and raw materials needed. The global aluminum profiles market is experiencing significant growth, driven by increasing demand from the construction, automotive, packaging, and electrical industries, with…
More Releases for Bank
Mortgage-Backed Security Market 2022: Industry Manufacturers Forecasts- Construc …
The Mortgage-Backed Security research report is the professional report with the premium insights which includes the size of the business, the ongoing patterns, drivers, dangers, conceivable outcomes and primary segments. The Market Report predicts the future progress of the Mortgage-Backed Security market based on accurate estimations. Furthermore, the report offers actionable insights into the future growth of the market based on inputs from industry experts to help readers formulate effective…
Doorstep Banking Services Market Challenges and Opportunities in Banking Service …
Doorstep banking is a facility provided so that user don't have to visit bank branches for routine banking activities like cash deposit, cash withdrawal, cheque deposit, or making a demand draft. The bank extends these facilities at user work place by appointing a service provider on your behalf.
This service was earlier available only to senior citizens but it is available to everyone with nominal fee charges, depending on the type…
Payments Landscape in Iran: Opportunities and Risks to 2021- Bank Saderat Iran, …
Payments Landscape in Iran: Opportunities and Risks to 2021
Publisher's "Payments Landscape in Iran: Opportunities and Risks to 2021", report provides detailed analysis of market trends in the Iranian cards and payments industry. It provides values and volumes for a number of key performance indicators in the industry, including payment cards and cheques during the review-period (2013-17e).
The report also analyzes various payment card markets operating in the industry, and provides detailed…
India Retail Banking Market Dynamics 2018 by SBI ICICI, HDFC, Axis Bank, Bank of …
Margins among Indian banks remained high at 6.3% in 2017 in comparison to its peers China (2.8%) and Malaysia (2.6%). The average cost-to-income ratio remained at around 53% during 2013-17, marginally higher than China (50%) and Malaysia (51%). However, there remain large disparities in operating efficiencies within the market. The same is also true for profitability, with large disparities in return on assets figures. This is due to rising compliance,…

