


Press release
Brake Lining Compliance and Fleet Uptime Priorities Reshape Heavy-Duty Truck Brake Lining Materials Market
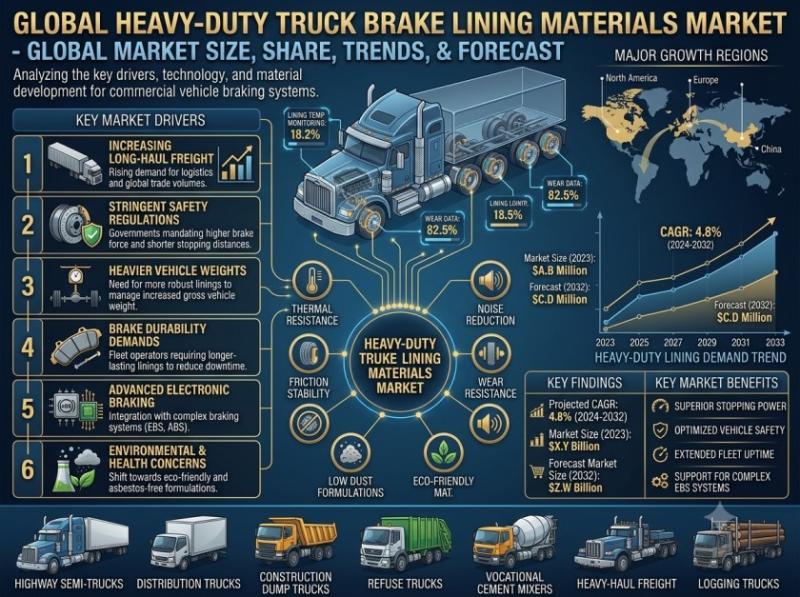
Heavy-Duty Truck Brake Lining Materials Market
The development comes as recurring fleet maintenance and stricter friction-material requirements support the Heavy-Duty Truck Brake Lining Materials Market. Future Market Insights (FMI) estimates that the market will exceed USD 1.6 billion in 2026 and expand at a 4.6% CAGR between 2026 and 2036 to reach USD 2.5 billion by 2036.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-gb-33292
Why are compliant brake lining materials gaining commercial importance?
For heavy-duty truck operators, brake lining selection is increasingly connected to both maintenance planning and compliance control. Friction materials operate under substantial heat and axle loads, particularly across long-haul freight, construction haulage, mining and other demanding duty cycles. As a result, fleets need replacement linings that combine correct fitment with predictable friction behavior during repeated braking.
The aftermarket is expected to account for 66.0% of sales channel demand in 2026. This leading share reflects the recurring replacement requirement created by friction wear across heavy commercial vehicles. Unlike components replaced primarily during major vehicle overhauls, brake linings move through service channels as operating mileage and braking intensity gradually consume friction material.
Regulatory changes are adding another layer to purchasing decisions. The EPA's March 2024 chrysotile asbestos rule bans aftermarket automotive brakes and linings after a six-month transition period. Federal Register analysis estimated that approximately 1,800 asbestos-containing automotive brake or lining sets could enter the United States annually. Although this represents a limited portion of the broader market, the shift reinforces the commercial importance of compliant formulations and reliable product documentation.
For distributors, this means catalog accuracy is becoming as important as product availability. A lining that is technically compatible but does not satisfy current material requirements can create procurement, service and compliance problems. Suppliers with clear formulation specifications and cross-reference data can therefore support faster replacement decisions across distributed truck service networks.
Which brake types and materials are shaping demand?
Drum linings are expected to remain the leading brake type, accounting for 57.0% of demand in 2026. Their position reflects continued use across heavy-duty tractor and trailer applications where braking systems must manage high vehicle weights and repeated service cycles.
Semi-metallic materials are projected to hold a 42.0% share of material type demand in 2026. Their use is supported by the need for friction materials capable of maintaining braking performance under elevated temperatures and severe-duty conditions. Material formulation therefore remains a central differentiator as fleets balance durability, heat management and regulatory requirements.
Class 8 trucks are expected to account for 46.0% of vehicle class demand in 2026. These vehicles operate extensively in freight applications, increasing exposure to mileage-related friction wear. Linehaul freight is forecast to represent 44.0% of end-use value, further connecting brake lining demand with long-distance vehicle utilization and scheduled maintenance.
The market also covers non-asbestos organic, ceramic, sintered and aramid friction materials, allowing suppliers to serve different performance, operating-temperature and application requirements.
What does the analyst see as the key commercial issue?
"Heavy-duty truck brake lining material demand is shifting toward uptime planning and compliance control. Fleets need correct fitment with stable fade behavior. Aftermarket channels gain from long-haul wear cycles. Copper-free formulations raise cost while OE validation reduces workshop service errors."
- Nikhil Kaitwade, Principal Consultant for Automotive domain, Future Market Insights
The commercial challenge is therefore not simply replacing worn friction material. Fleet operators and distributors increasingly need to identify the correct lining specification, verify compliance and minimize installation errors without extending vehicle downtime.
Market Snapshot
• Market value, 2025: More than USD 1.5 billion
• Forecast market value, 2026: More than USD 1.6 billion
• Forecast market value, 2036: USD 2.5 billion
• Global CAGR, 2026-2036: 4.6%
• Incremental opportunity, 2026-2036: USD 0.9 billion
• Leading sales channel: Aftermarket, with a 66.0% share in 2026
• Leading brake type: Drum linings, with a 57.0% share in 2026
• Leading material type: Semi-metallic materials, with a 42.0% share in 2026
• Leading vehicle class: Class 8 trucks, with a 46.0% share in 2026
• Leading end use: Linehaul freight, with a 44.0% share in 2026
• Fastest-growing profiled country: India, at a 6.2% CAGR through 2036
• Second-fastest-growing profiled country: China, at a 5.8% CAGR through 2036
What is driving near-term demand?
Heavy-duty truck brake lining demand is closely tied to vehicle utilization and maintenance frequency. FMCSA's July 2025 pocket guide recorded 331.3 billion large-truck miles traveled in the United States in 2022. Such mileage exposure creates recurring friction wear and reinforces the importance of brake inspection and replacement programs across commercial fleets.
Roadside inspection activity can further increase replacement discipline. Worn or damaged friction material can affect a truck's ability to remain in freight service, making preventive maintenance an operational priority rather than simply a workshop expense. Fleet operators therefore have an incentive to schedule brake component replacement before worn linings create service interruptions.
Material compliance is also changing supplier requirements. Bendix's November 2024 update on N-Level copper compliance demonstrates how manufacturers are adjusting friction portfolios to meet evolving material expectations. The planned discontinuation of ES600 at the end of 2024 also signals the importance of maintaining current product catalogs across distributor networks.
Testing infrastructure is expanding alongside these requirements. TMD Friction invested €1.5 million in a Euro 7 brake emissions test bench in November 2024. The facility is designed to accelerate brake-pad testing for emerging emissions requirements and product approvals. For friction-material suppliers, such investment supports faster validation as environmental requirements become more integrated into brake-product development.
Severe-duty performance remains another commercial differentiator. Haldex states that its GZ 2035 semi-metallic lining is equivalent to FMVSS 121 performance levels for a 23,000 lb axle load and a 1000°F temperature range. Such performance positioning illustrates why heat resistance and stable friction behavior remain important when suppliers target heavy-duty applications.
How are India and China shaping market development?
India is expected to expand at a 6.2% CAGR through 2036, making it the fastest-growing country market among the profiled countries. Rising freight activity and expanding heavy-truck service requirements support replacement demand, while a broad aftermarket creates opportunities for distributors and workshops offering correctly specified friction materials.
China is projected to grow at a 5.8% CAGR during the same period. The country's heavy-vehicle manufacturing base and developing service networks provide a foundation for recurring brake lining demand. Suppliers that can combine product availability with technical documentation and application-specific fitment information can strengthen their position across these growing markets.
The geographic opportunity is particularly relevant for aftermarket suppliers because brake lining replacement is distributed across large service ecosystems rather than concentrated entirely within vehicle assembly plants.
What challenges could limit heavy-duty truck brake lining material adoption?
Cost pressure remains an important constraint as manufacturers invest in copper-free formulations, emissions testing and product validation. Advanced formulation and testing requirements can increase development expenses, while fleet operators continue to prioritize cost-effective maintenance.
Catalog complexity is another challenge. Heavy-duty trucks operate across multiple axle configurations, braking systems, vehicle classes and duty cycles. Incorrect product selection can result in repeat workshop work or vehicle downtime. Distributors therefore need accurate application data and current cross-reference systems.
Regulatory fragmentation can also complicate international commercialization. Material restrictions, emissions requirements and testing expectations can differ by market. Suppliers serving multiple regions must maintain documentation and product portfolios that align with local requirements while preserving consistent performance.
Market Definition
The Heavy-Duty Truck Brake Lining Materials Market covers friction compounds used in brake shoes, drum linings, disc pads and brake blocks for heavy commercial vehicles. These materials convert vehicle motion into stopping force through friction within drum and disc brake assemblies.
The market includes semi-metallic, non-asbestos organic, ceramic, sintered and aramid friction materials. It covers drum linings, disc pads, brake blocks and combination linings across Class 8 trucks, Class 7 trucks, heavy buses and vocational trucks.
Sales channels include aftermarket, OEM supply, distributor sales and fleet contracts. End-use applications include linehaul freight, construction haulage, municipal fleets and mining trucks.
Complete brake assemblies, rotors, drums, calipers, brake fluids, electronic braking systems and passenger-vehicle brake friction products are excluded from the market scope.
Market Segmentation Analysis
The Heavy-Duty Truck Brake Lining Materials Market is segmented by material type, brake type, vehicle class, sales channel, end use and region.
By material type, the market includes semi-metallic, non-asbestos organic, ceramic, sintered and aramid friction materials. Semi-metallic materials are expected to lead with a 42.0% share in 2026, supported by their relevance to severe-duty braking and elevated-temperature applications.
By brake type, the market covers drum linings, disc pads, brake blocks and combination linings. Drum linings are expected to account for 57.0% of demand in 2026.
By vehicle class, the market includes Class 8 trucks, Class 7 trucks, heavy buses and vocational trucks, with Class 8 trucks forecast to hold a 46.0% share.
By sales channel, aftermarket, OEM supply, distributor sales and fleet contracts are covered. Aftermarket sales are expected to lead with a 66.0% share in 2026 as worn friction materials generate recurring replacement demand.
By end use, the market includes linehaul freight, construction haulage, municipal fleets and mining trucks. Linehaul freight is projected to represent 44.0% of end-use value in 2026.
Demand also intersects with adjacent brake-component categories, including automotive brake friction products, automotive brake pad industry analysis, copper-free brake pad materials, automotive brake booster and master cylinder industry analysis, and the automotive vacuum brake booster market.
About the Report
Future Market Insights' latest study analyzes the global Heavy-Duty Truck Brake Lining Materials Market across material type, brake type, vehicle class, sales channel, end use and region. The study covers semi-metallic, non-asbestos organic, ceramic, sintered and aramid friction materials, alongside drum linings, disc pads, brake blocks and combination linings.
The vehicle-class analysis includes Class 8 trucks, Class 7 trucks, heavy buses and vocational trucks. Sales channels comprise aftermarket, OEM supply, distributor sales and fleet contracts, while end-use applications include linehaul freight, construction haulage, municipal fleets and mining trucks.
The report evaluates market development across major regions and country markets, with particular attention to India and China, which are projected to record CAGRs of 6.2% and 5.8%, respectively, through 2036.
FMI's research methodology combines primary and secondary research. Primary research incorporates input from fleet service managers, brake-part distributors, friction-material suppliers and commercial vehicle workshops. Secondary research draws on safety inspection records, brake-material regulations, official vehicle sales data and company product portfolios. Market sizing is developed across brake type, vehicle class, sales channel and duty cycle, with data validation against fleet mileage, inspection outcomes, regulatory changes and supplier catalog coverage.
Exhaustive Market Report: A Complete Study
https://www.futuremarketinsights.com/reports/heavy-duty-truck-brake-lining-materials-market
Access the Complete Report Methodology Now!
https://www.futuremarketinsights.com/methodology
Browse More Industry Reports :
SPF Moisturizers Market
https://www.futuremarketinsights.com/reports/spf-moisturizers-market
Anti-Aging Devices Market
https://www.futuremarketinsights.com/reports/anti-aging-devices-market
Glycolic Acid Toners Market
https://www.futuremarketinsights.com/reports/glycolic-acid-toners-market
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware - 19713, USA
T: +1-845-579-5705
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Brake Lining Compliance and Fleet Uptime Priorities Reshape Heavy-Duty Truck Brake Lining Materials Market here
News-ID: 4629497 • Views: …
More Releases from Future Market Insights
Object Detection Cameras Market to Reach USD 3.4 Billion by 2036 as Maritime Per …
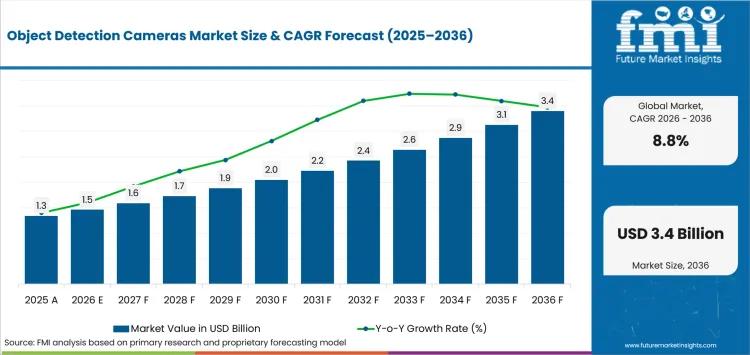
According to Future Market Insights (FMI), the global object detection cameras market is projected to reach USD 3.4 billion by 2036, rising from USD 1.5 billion in 2026 and expanding at an 8.8% CAGR during the forecast period. Increasing adoption of camera-based perception systems for hazard identification, supervised collision avoidance, and autonomous maritime operations is supporting market growth.
Object detection cameras are increasingly being considered as part of vessel perception systems…
Industrial Bus Couplers Market to Reach USD 2.0 Billion by 2036 as Industrial Ne …
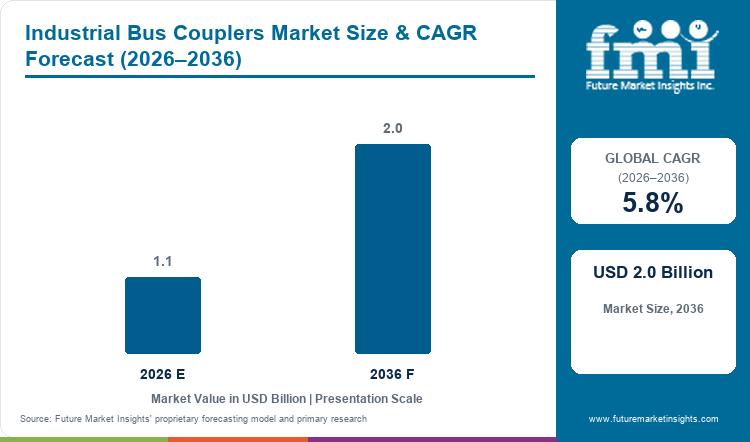
According to Future Market Insights (FMI), the global industrial bus couplers market is projected to reach USD 2.0 billion by 2036, rising from USD 1.1 billion in 2026 and expanding at a 5.8% CAGR during the forecast period. Growing requirements for controller-network compatibility, modular industrial I/O architectures, and flexible machine communication are supporting demand for industrial bus couplers across automation environments.
Industrial bus couplers enable downstream I/O designs to communicate with…
Decorative Car Accessories Market to Reach USD 530.2 Billion by 2036; China Lead …
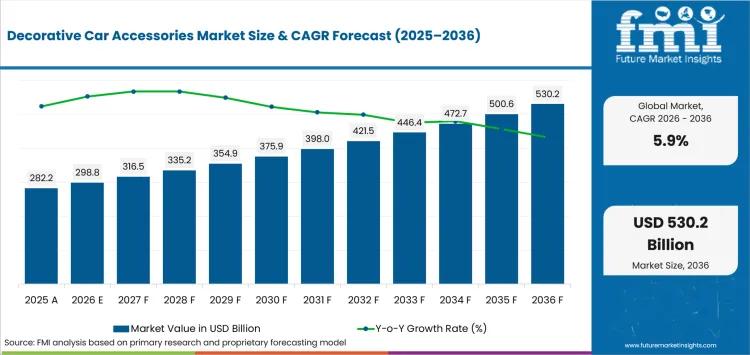
The global decorative car accessories market is projected to increase from USD 298.8 billion in 2026 to USD 530.2 billion by 2036, expanding at a 5.9% CAGR between 2026 and 2036. The market was valued at USD 282.2 billion in 2025. Demand is being supported by consumers seeking personalized vehicle interiors, exterior styling enhancements, comfort upgrades, and protection accessories across passenger and commercial vehicle segments.
Vehicle personalization is increasingly influencing aftermarket…
Paver Block Moulds Market to Reach USD 1,584.2 Million by 2036 at 4.8% CAGR; Rom …
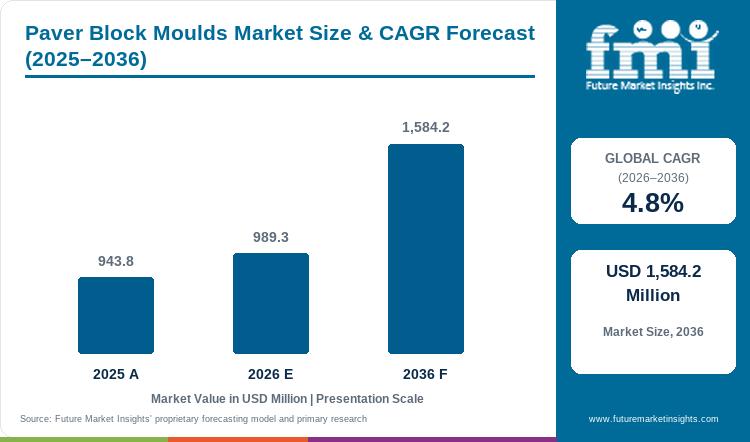
The global Paver Block Moulds Market is projected to grow from USD 989.3 million in 2026 to USD 1,584.2 million by 2036, expanding at a 4.8% CAGR during the 2026-2036 forecast period, according to Future Market Insights. The market was valued at USD 943.8 million in 2025.
Demand for paver block moulds is supported by the need for consistent cavity geometry, repeatable production, and tooling that fits specific concrete block machines.…
More Releases for Material
Firestop Material Market
LOS ANGELES, United States: The global Firestop Material market is carefully researched in the report while largely concentrating on top players and their business tactics, geographical expansion, market segments, competitive landscape, manufacturing, and pricing and cost structures. Each section of the research study is specially prepared to explore key aspects of the global Firestop Material market. For instance, the market dynamics section digs deep into the drivers, restraints, trends, and…
New Material Direction for Electric Toothbrushes - Si-TPV Soft Over Molded Mater …
When it comes to factors such as consumer experience or ergonomics, Si-TPV Soft Over Molded Material has had a huge impact on the improvement of various products such as electric toothbrushes, etc. Si-TPV is a Silicone Combine TPU developed and produced by SILIKE, a Thermoplastic Elastomer Manufacturer (Thermoplastic Elastomer Suppliers). Si-TPV material adopts Innovative Soft Slip Technology and Sustainable Overmolding Techniques, which can be used to make Stain Resistance Soft…
A new light on a misjudged material - Plastic waste: material for art
Used plastic bottles are not waste, but a valuable resource. They can be reprocessed in a variety of ways and transformed into new products or fresh energy. And into art. This is exactly what Ve-ronika Richterová does. The Czech artist creates fascinating sculp-tures made out of old PET bottles.
Plastic has inspired artists from the very beginning. The reason: plas-tic meets almost all technical and aesthetic requirements. It is a uni-versal…
Global Thermal Transfer Material Market, Global Thermal Transfer Material Indust …
Thermal conductivity refers as an important characteristic for several manufacturing operations. Thermal transfer properties of a variety of materials are effective in certain applications owing to natural molecular structure that allows for direct heat-transfer. Thermal transfer materials are extensively used to manufacture the heat conductive adhesive tapes, printable products and polymer sheets. These polymer sheets are utilized for barcodes, labeling, and QR code labels for retailing, logistics, and consumer goods.…
The Future of Smart Material Market Runs Through the Material Industry
Smart Materials Market is expected to garner $72.63 billion by 2022, registering a CAGR of 14.9% during the forecast period 2016-2022. Smart materials are adaptive or intelligent materials which pose intrinsic and extrinsic capabilities. These can be altered by external stimuli, such as moisture, temperature, electromagnetic field, and pressure to obtain the desired functional effects. In addition, these materials are dynamic in nature and respond to their immediate interaction environments…
Global Regenerative Artificial Skin Sales Market Research Report 2017 (Temporary …
The report "Global Regenerative Artificial Skin Sales Market Report 2017", has been prepared based on an in-depth market analysis with inputs from industry experts.
This report studies sales (consumption) of Regenerative Artificial Skin in Global market, especially in United States, China, Europe and Japan, focuses on top players in these regions/countries, with sales, price, revenue and market share for each player in these regions, covering
Integra Life Sciences Corporation
Mylan N.V
Johnson & Johnson…

