
Press release
How to Use a CD Rate Calculator Before You Lock In
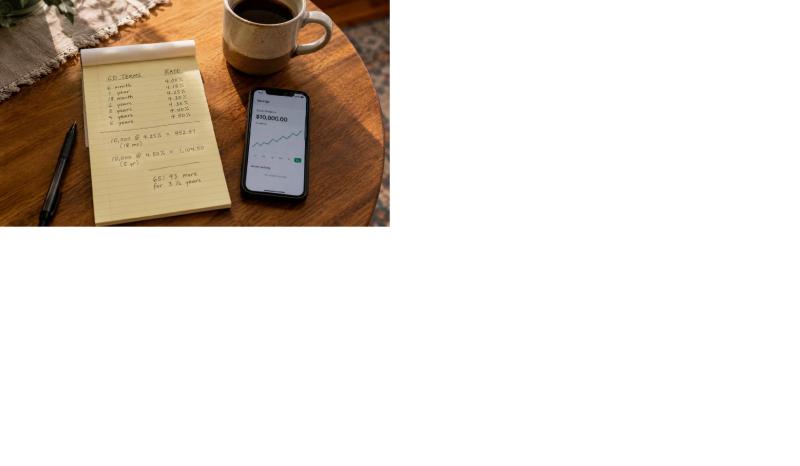
This is the gap a CD rate calculator closes. It converts an advertised percentage into the only figure that actually matters: how many dollars land in your account, and when. If you are comparing offers right now, deciding between a one-year and a five-year term, or trying to work out whether breaking a CD early would still leave you ahead, this article walks through the math and the judgment calls behind it.
You'll learn which four inputs drive the result, why APY and interest rate are not the same number, how penalties change the calculation, and where a calculator's answer stops being reliable.
What a CD Rate Calculator Actually Tells You
A CD rate calculator answers one question precisely: given a deposit amount, a term, a yield, and a compounding schedule, what will the account be worth at maturity?
That sounds narrow, and it is. But the narrowness is the point. Bank marketing leads with a percentage because percentages are easy to compare and hard to feel. Nobody has an instinct for what 4.15% over 18 months means. Everyone understands $623.
The calculator also makes the comparison honest. Different terms, different compounding schedules, and different minimum deposits make advertised rates nearly impossible to rank in your head. Reduced to ending balances, the ranking becomes obvious in seconds.
The Four Numbers Every CD Rate Calculator Needs
Every calculator worth using asks for the same four inputs.
Deposit amount - your principal. Most CDs don't allow additions after opening.
Term length - typically three months to five years, sometimes ten.
APY or interest rate - read the label carefully; they behave differently.
Compounding frequency - daily, monthly, quarterly, or at maturity.
Get any one of these wrong and the output is wrong. The most common error is entering a nominal interest rate into a field expecting APY, which quietly overstates your return.
APY vs. Interest Rate: Why the Gap Matters
The interest rate is the base rate the bank pays. Annual percentage yield folds compounding into that figure, showing what you actually earn over a full year.
A CD paying 4.00% compounded daily produces an APY of roughly 4.08%. Compounded annually, 4.00% is simply 4.00%. Same headline rate, different outcome.
Because APY already accounts for compounding, it's the fair basis for comparison, and U.S. banks are required to disclose it. When a listing shows only "rate," treat it as incomplete and ask for the APY before you calculate anything.
How Compounding Frequency Changes Your Total
Compounding is interest earning interest. The more often it happens, the more you end up with.
On modest balances over short terms, the difference is small - often a few dollars between daily and quarterly compounding on a one-year CD. The gap widens with larger deposits and longer terms, and it becomes material on five-year CDs holding five or six figures.
Some CDs pay simple interest at maturity with no compounding at all. Those are not directly comparable to compounding accounts at the same headline rate, and a calculator will show you exactly how much you're giving up.
Where CD Rates Stand in Mid-2026
Context matters, because a good rate is only good relative to what else is available.
The Federal Reserve held its target range at 3.50%-3.75% at the July 29, 2026 meeting, with three officials dissenting in favor of a quarter-point increase - an unusually visible split. Deposit rates broadly follow that policy path.
As of early August 2026, the strongest nationally available one-year CDs cluster around 4.15% to 4.40% APY, mostly at online banks and credit unions. National averages, by contrast, sit near 2% for one-year terms. That spread is the single most actionable fact in this article: the difference between an average offer and a competitive one is often larger than the difference between a one-year and a five-year term.
Running the Math Before You Commit
Once you've gathered two or three real offers, stop comparing percentages and start comparing ending balances. Enter each offer with its actual term, its disclosed APY, and its stated compounding schedule, then line the totals up side by side. A dedicated CD rate calculator https://cdrate-calculator.com/ handles this quickly and removes the arithmetic errors that creep in when people try to annualize returns by hand - particularly on terms that aren't a round number of years, like 13-month or 18-month promotional CDs.
Treat the output as a clean comparison, not a guarantee. It reflects the inputs you gave it and assumes you hold to maturity, take no withdrawals, and decline automatic renewal at a lower rate. Every one of those assumptions is a decision you still have to make.
A Worked Example: $10,000 Across Three Terms
Assume $10,000 and annual compounding, using rates roughly in line with what's available now.
One year at 4.25% APY: $10,425 - about $425 in interest.
Three years at 4.00% APY: roughly $11,249 - about $1,249.
Five years at 3.90% APY: roughly $12,108 - about $2,108.
The five-year CD pays the most in total dollars, but the lowest annual rate, and it holds your money for four additional years. Whether that trade is worth it depends entirely on whether you'll need the cash and where rates go next.
Why the Longest Term Isn't Always the Best Return
Longer terms usually pay more because you're compensated for accepting less flexibility. That relationship breaks down more often than people expect.
When the Rate Curve Flattens or Inverts
When markets anticipate rate cuts, banks stop paying a premium for long commitments - and sometimes pay less. That's roughly the situation now: short and mid-length CDs frequently out-yield five-year offers.
If a one-year CD pays more than a five-year CD, locking up money for five years buys you protection against future rate declines, not a higher current yield. That protection can be worth having. It's simply a different product than most savers think they're buying.
Early Withdrawal Penalties Can Erase Months of Interest
This is where CD math gets punishing. Typical penalties run from 90 days' interest on short terms to six or twelve months' interest on multi-year CDs.
Take the five-year CD at 3.90%. Cash out at 18 months and you've earned roughly $591 - but a twelve-month interest penalty of about $390 leaves you near $200. Your effective return drops to well under half the advertised yield.
Some banks can deduct penalties from principal if earned interest is insufficient, meaning you withdraw less than you deposited. Read the disclosure. Before committing, run the withdrawal scenario, not just the maturity scenario.
Building a CD Ladder With a Rate Calculator
A ladder splits one deposit across staggered maturities. For example, you could divide $25,000 into five $5,000 rungs with terms ranging from one to five years. Each year, one rung matures and can either be spent or reinvested.
The result is annual access to a portion of your money while most of the deposit continues earning longer-term rates. Once the ladder is fully established, each maturing rung can be rolled into a new five-year CD, helping maintain both liquidity and potentially stronger long-term returns.
Because every rung has a different term, rate, and maturity date, calculating a ladder manually can become time-consuming. Using a CD ladder calculator https://cdrate-calculator.com/cd-ladder-calculator/ makes it easier to model each rung, compare projected earnings, and understand when your money will become available. This gives you a clearer picture of both your expected yield and your overall liquidity schedule.
Taxes: The Number the Calculator Doesn't Show
CD interest is taxable as ordinary income at your federal rate, and usually at the state level too. Your bank reports it on Form 1099-INT.
Critically, interest on multi-year CDs is generally taxed in the year it's credited, even though you can't access it. A five-year CD can generate a tax bill each year while paying you nothing until maturity.
That $2,108 in our example might be closer to $1,550 after federal tax in the 24% bracket. No standard calculator subtracts this for you.
CDs vs. High-Yield Savings and Treasury Bills
High-yield savings accounts currently pay rates competitive with many CDs while staying fully liquid - but that rate can drop at any time without notice. A CD's rate is fixed for the full term. That certainty is what you're paying for.
Treasury bills, meanwhile, are exempt from state and local income tax, which matters meaningfully in high-tax states. Compare after-tax returns rather than headline yields.
Both CDs and savings accounts carry federal insurance up to $250,000 per depositor, per institution, per ownership category - FDIC for banks, NCUA for credit unions.
Where the Deposit Money Usually Comes From
Most people don't open a CD with a windfall. The deposit comes from cash that accumulated after a deliberate decision to spend less somewhere else - a refinanced loan, a canceled subscription stack, a business that trimmed its overhead.
Small business owners in particular often find their first meaningful reserve this way. Reviewing energy use, maintenance schedules, packaging, and unused software subscriptions frees up recurring cash without cutting into revenue, and there are well-documented practical ways to reduce operating costs https://techbullion.com/sustainable-business-practices-that-can-reduce-operating-costs/ that require little upfront investment. Once those savings become a stable monthly surplus, the question shifts from how do we cut to where does the surplus sit. A short-term CD is one reasonable answer for reserve cash that has no assigned job for six or twelve months - provided the business won't need it sooner, since operating capital and locked deposits are a poor combination.
Mistakes a CD Rate Calculator Helps You Avoid
Three errors show up repeatedly.
Assuming auto-renewal is neutral. Most CDs renew automatically at whatever rate the bank is offering that day, often well below what you originally earned. Grace periods are typically seven to ten days.
Comparing a promotional rate to a standard one. A 13-month special at 4.40% and a standard 12-month at 3.95% aren't the same product on the same terms.
Ignoring minimum deposits. The best advertised rate frequently requires $10,000 or more. If you have $2,500, that offer isn't available to you.
Questions to Ask the Bank Before You Sign
Confirm the disclosed APY, the compounding frequency, the exact early withdrawal penalty, whether the penalty can reduce principal, the renewal policy, the grace period length, and whether interest can be paid out monthly instead of at maturity. Get answers in writing. Every one of these changes the number your calculation produces.
What Savers Should Watch Next
With the Fed holding and a divided committee, the near-term direction is genuinely uncertain - some officials favor tightening, others don't. Nobody can tell you where CD rates land in twelve months.
What you can control is the spread you capture today. Chasing the gap between a 2% average offer and a 4%+ competitive one is a more reliable strategy than trying to time policy.
The Bottom Line on Using a CD Rate Calculator
A CD rate calculator won't tell you whether a certificate of deposit belongs in your plan. That depends on when you need the money and what else you'd do with it.
What it will do is stop you from mistaking a longer term for a better return, or a higher headline rate for a higher payout. Enter your real numbers, run the maturity scenario and the early-withdrawal scenario, and compare after-tax totals rather than advertised percentages.
Gather two or three current offers, run them side by side, and check whether the winner is still the winner when you assume you might need the cash early.
webxfixer
Press Release Distribution by https://webxfixer.com
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release How to Use a CD Rate Calculator Before You Lock In here
News-ID: 4599087 • Views: …
More Releases from webxfixer
Financial License Market Expands Marketplace for Licensed Financial Businesses A …
Limassol, Cyprus, October 2026. Financial License Market, the M&A marketplace operated by Zitadelle Advisory Group, now lists regulated financial companies for sale across 20 jurisdictions at https://www.financiallicensemarket.com/listings. Listings include investment firms, payment and e-money institutions, money service businesses and fund managers.
The platform also publishes active buyer mandates from acquirers looking for specific licences at https://www.financiallicensemarket.com/wanted. Recent mandates include UK and EU e-money institutions, EU payment institutions, a multi-jurisdiction payment licence…
Judicial Independence under Scrutiny: What Were the Assurances UK Judge had rece …
UK judge's recorded reference to assurances, two refusals of permission to appeal and questions about who was asked to examine the evidence have brought a property dispute into a wider debate about judicial independence.
Public Confidence in the Judiciary Depends Fundamentally on Institutional and Operational Independence
Public confidence in the justice system depends on more than whether a party wins or loses. It depends on whether judges appear independent, whether possible conflicts…
Scottsdale's Fantasy Co Highlights Private Bachelor Party Entertainment and Spec …
SCOTTSDALE, AZ - Scottsdale's Fantasy Co LLC, an Arizona-based private entertainment company, is highlighting its bachelor party entertainment services for groups celebrating in Scottsdale, Phoenix, and surrounding communities.
The company specializes in bringing adult entertainment directly to private residences and vacation accommodations, offering an alternative to traditional strip clubs and crowded nightlife venues.
As travelers plan bachelor party weekends around Scottsdale's golf courses, restaurants, pool parties, and entertainment districts, private group experiences…
LawyerGov Surpasses $50 Million in Digital Asset Recovery, Expands Multi-Jurisdi …
LawyerGov, a legal services platform focused on cryptocurrency fraud and online investment s c a m s, today announced that it has surpassed $50 million in digital assets recovered for clients. The company also announced an expansion of its blockchain forensics operations to support cases across multiple jurisdictions.
Crypto investment fraud has become one of the most damaging categories of financial crime. The typical scheme begins with an unsolicited message on…
More Releases for APY
6 Crypto Presales With Staking Rewards: How Apeing's 85% APY Compares
Six presales with staking features enter comparison as Apeing's advertised 85% APY brings a high-yield angle to the field.
Headline APY can make a staking sale look simple, but a valid comparison must include lockup, reward source, inflation, sustainability and stage terms. This Top crypto presale framework uses Apeing ( https://www.apeing.com/ ) as the only named case study. Its rate is advertised as up to 85% APY, not assured income. The…
XRP vs BTC Price Prediction: SpaceX Rumours Meet 11,111% GRUNTLE APY
Speculation surrounding a potential SpaceX initial public offering (https://www.bbc.com/news/articles/cg4pe2953q1o) injected fresh volatility into the crypto market today, as Bitcoin (BTC) dropped 0.55% to trade at $77,077. Ethereum (ETH) followed with a 0.39% slide to $2,127, according to the latest Ethereum price on Coinbase (https://www.coinbase.com/price/ethereum), signaling broader market consolidation as traders weigh macro catalysts against technical resistance levels. With major caps grinding sideways, capital is rotating toward early-stage setups like Gruntle…
Is Crypto Making a Comeback, $GRUNTLE Offers 25% APY Refuge
The crypto presale landscape is currently dominated by massive, high-velocity capital raises. This reflects a market hungry for early-stage allocations, driven by a stabilizing macroeconomic backdrop. Rather than trying to out-shout these massive entities with fabricated urgency, Gruntle positions itself as the deadpan, low-friction alternative for exhausted market participants.
________________________________________
Presale Landscape: High-Velocity Raises Set the Pace
The broader financial ecosystem is currently watching Bitcoin (BTC) test new support levels, holding strong above…
APEMARS: Earn Free Crypto with 63% APY - ADA and DOT Rise
Earn Free Crypto Now: APEMARS Offers 63% APY Staking - A Top Crypto to Invest In With 1000x Potential, Outpacing ADA & DOT Momentum
Crypto markets move in cycles, but opportunity rarely announces itself loudly. Sometimes it hides in plain sight between a presale clock counting down and blue-chip networks recalibrating their momentum. Right now, conversations around the top crypto to invest in https://www.apemars.com are split between established ecosystems like Cardano…
Pepeto vs. Yield First Presales: Meme Utility Versus Fixed APY Narratives
Crypto market news today indicates an abundance of initial presales that promote fixed APY, farming pools, and simple reward schedules. These launches are often enticing because they offer guaranteed returns, but many of them are fueled primarily by emissions and short-term incentives. When rewards become thinner, liquidity tends to become thinner, there is increased sell pressure, and it's time to move the narrative to the next pool.
Pepeto (https://pepeto.io) enters into…