


Press release
Ken Research Stated Saudi Arabia Warehouse Automation Market to Reach USD 493.4 Million
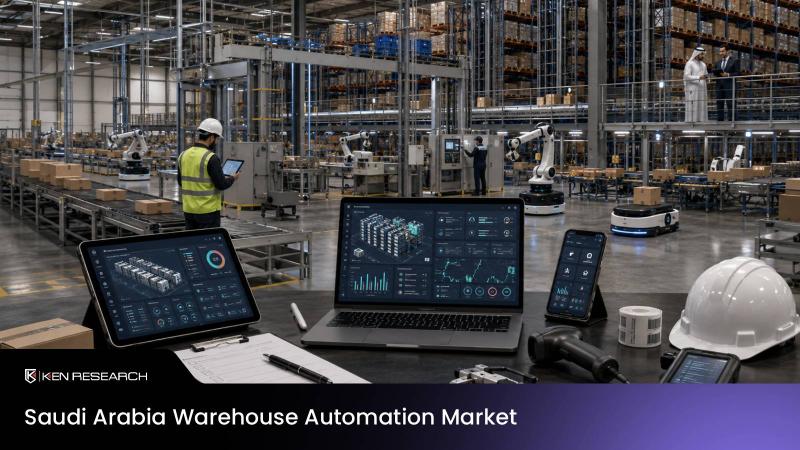
Saudi Arabia Warehouse Automation Market to reach USD 493.4 million by 2031, driven by e-commerce fulfilment, national logistics z
Delhi, India - July, 2026 - Ken Research released its strategic market analysis titled "Saudi Arabia Warehouse Automation Market," revealing that the market reached approximately USD 211.0 million in 2025. The market is projected to expand at a CAGR of 15.2%, reaching approximately USD 493.4 million by 2031, supported by e-commerce fulfilment growth, logistics-zone development, higher warehouse throughput requirements, pharmaceutical traceability, and the adoption of integrated robotic and software-led systems.
The report page lists 86 pages in its primary metadata and 98 pages in the expanded table-of-contents section. The detailed report structure contains 34 chapters, profiles 10 companies, evaluates seven segmentation categories, and includes more than 201 assessment and strategy sections. Its findings were validated through 302 respondents, including warehouse operations directors, automation solutions architects, supply-chain technology heads, and system-integration managers.
"The Saudi Arabia Warehouse Automation Market is moving beyond standalone equipment purchases toward integrated fulfilment infrastructure connecting automated storage, mobile robotics, conveyors, machine vision, warehouse-control software, cybersecurity, and lifecycle support," said Namit Goel, Research Director at Ken Research. "Equivalent automation deployments are projected to increase from approximately 96 in 2025 to 173 by 2031, while average contract value rises from USD 2.20 million to USD 2.85 million."
Download the free sample report:
https://www.kenresearch.com/sample-report/saudi-arabia-warehouse-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
Key Market Dynamics Reshaping the Saudi Arabia Warehouse Automation Landscape
The report identifies four key growth drivers that will define market development:
E-Commerce and Omnichannel Fulfilment Expansion
Digital commerce is increasing the number of orders, stock-keeping units, returns, delivery commitments, and peak-period fulfilment requirements managed by Saudi warehouses.
Saudi Arabia was projected to have approximately 34.5 million e-commerce users in 2025, while e-commerce revenue was forecast to reach USD 69 billion. These indicators strengthen the business case for automated storage, goods-to-person picking, high-speed sorting, inventory orchestration, and real-time order visibility.
Licensed delivery applications completed more than 290 million orders during 2024, representing year-on-year growth of approximately 27.2%. This level of activity places greater pressure on distribution centres to increase order throughput without proportionately increasing warehouse space and manual labour.
The country also recorded approximately 40,953 active e-commerce commercial registrations during the fourth quarter of 2024. This expanding merchant base supports demand for shared fulfilment centres, third-party logistics services, cloud-based warehouse-management systems, and modular automation.
Online retailers increasingly compete through inventory availability, order accuracy, delivery speed, returns management, and customer communication. Warehouse operations can therefore become either a competitive advantage or a service bottleneck.
Average parcel-delivery time declined to approximately two days during 2024, while on-time delivery compliance reached around 96%. These service expectations leave limited tolerance for slow picking, inventory mismatches, manual consolidation errors, or system outages.
Automated storage and retrieval systems can improve storage density and reduce the distance travelled by workers. Goods-to-person systems can bring inventory directly to picking stations, while conveyors and sorters can coordinate movement between receiving, storage, picking, packing, and dispatch.
Autonomous mobile robots provide a more flexible alternative for facilities that cannot immediately justify major structural modifications. Robots can be introduced in phases, reassigned between operating zones, and scaled during seasonal peaks.
Warehouse-management and control software will become increasingly important as operators coordinate manual workers, conveyors, storage systems, mobile robots, scanners, sensors, and enterprise-resource-planning platforms.
The largest commercial opportunity will not necessarily be the sale of individual machines. Higher-value contracts will combine hardware, software, integration, commissioning, maintenance, performance monitoring, and future capacity expansion.
National Logistics and Warehouse Infrastructure Development
Saudi Arabia had approximately 12,234 licensed commercial warehouses covering around 22 million square metres during 2024. This creates a substantial addressable market for both greenfield automation and brownfield retrofitting.
The Kingdom is targeting 59 logistics zones by 2030, supporting new demand for high-bay storage, automated pallet handling, dock automation, warehouse software, cold-chain systems, and integrated material-flow infrastructure.
MODON's investor base reached approximately 7,946 industrial and logistics investors in 2023. These businesses create demand across raw-material storage, production logistics, spare-parts management, finished-goods distribution, and industrial fulfilment.
Greenfield logistics projects provide vendors with the opportunity to participate during facility design. Early involvement allows automation requirements to be incorporated into ceiling height, floor loading, power systems, network infrastructure, fire safety, equipment layout, dock capacity, and expansion planning.
Automation installed after a warehouse becomes operational may involve greater complexity. Brownfield projects must preserve daily throughput while new systems are integrated with existing storage, software, labour processes, and customer commitments.
The automation penetration rate across addressable medium and large warehouses was estimated at approximately 27% in 2025. It is projected to reach around 51% by 2031, creating a significant retrofit and upgrade opportunity.
This expansion will generate revenue beyond initial installations. Automated warehouses require preventive maintenance, spare parts, software support, controls upgrades, cybersecurity, system optimization, operator training, and equipment modernization.
Saudi Arabia's freight network handled approximately 331.3 million tonnes of sea cargo during 2024. Port-linked distribution and industrial logistics will strengthen automation demand in Jeddah, the Eastern Province, and other freight corridors.
Facilities handling imported consumer goods, food, pharmaceuticals, industrial equipment, chemicals, automotive parts, and manufacturing inputs require reliable inventory control and faster movement between ports, warehouses, factories, and customers.
Large warehouse projects must be evaluated using total operating economics rather than equipment prices alone. Investment cases should consider labour productivity, land utilization, storage density, order accuracy, inventory losses, throughput, service levels, and lifecycle costs.
Higher Service Levels and Sector-Specific Traceability
Pharmaceutical, healthcare, food, luxury, beauty, and industrial distribution require more rigorous inventory accuracy and operating control than conventional storage environments.
Nahdi's automated pharmaceutical distribution centre can process approximately 200 million stock-keeping units annually, demonstrating the scale that can be achieved through integrated storage, temperature control, picking, traceability, and warehouse software.
Pharmaceutical warehouses require documented product movement, batch visibility, expiry-date control, environmental monitoring, and reliable order fulfilment.
Automation can reduce picking errors and create digital records covering receiving, storage location, movement, picking, packing, and dispatch.
Food and beverage operators can use automation to manage high inventory rotation, temperature-controlled products, expiry dates, and seasonal demand.
Luxury and beauty distributors require high-density storage and accurate handling across large numbers of relatively small product lines.
Chalhoub Group's Riyadh automation project includes approximately 67,000 AutoStore bins and 42 robots, illustrating the suitability of high-density robotic fulfilment for fashion, beauty, luxury, and e-commerce distribution.
Manufacturers and industrial distributors require different solutions, including pallet automation, automated guided vehicles, spare-parts storage, line-side delivery, raw-material movement, and finished-goods handling.
Public and healthcare supply networks may prioritize product availability, traceability, reliability, and emergency preparedness over the lowest equipment price.
The strongest automation providers will develop sector-specific solutions rather than offering identical system designs to every warehouse.
Pharmaceutical projects require validated software and environmental controls. Grocery fulfilment requires high throughput and temperature zoning. Industrial facilities may require heavy-load equipment and integration with production systems.
Sector specialization can improve vendor differentiation because customers require more than equipment availability. They also require compliance knowledge, application engineering, implementation experience, and dependable support after commissioning.
Flexible Robotics and Software-Led Automation Adoption
Automated storage and retrieval systems represent the market's largest solution pool because they support high-density storage, land optimization, controlled inventory movement, and reduced manual travel.
However, autonomous mobile robots and machine-vision systems are expected to record faster adoption as warehouse operators seek flexible solutions that can be introduced without rebuilding entire facilities.
Fixed automation can deliver high throughput when demand patterns and product flows are predictable. Conveyors, sorters, shuttles, and cranes are suitable for large facilities with stable operating requirements.
Flexible robotics may be more appropriate for businesses facing seasonal peaks, changing product ranges, uncertain volumes, or multiple customer contracts.
Autonomous mobile robots can transport shelves, cartons, totes, and pallets between storage, picking, packing, and dispatch zones.
Machine vision can support barcode reading, dimensioning, quality checks, damage identification, inventory counting, and robotic guidance.
Warehouse-management systems provide inventory and workflow control, while warehouse-control and execution systems coordinate equipment and prioritize tasks in real time.
The market is therefore shifting from equipment-centred projects toward integrated software-led environments.
Average automation contract value is projected to increase from approximately USD 2.20 million in 2025 to USD 2.85 million by 2031. The increase reflects greater software, robotics, machine-vision, cybersecurity, and lifecycle-service content rather than equipment inflation alone.
Cloud-based software and subscription models can lower the initial cost of warehouse digitization for operators that are not ready for a complete turnkey system.
Robotics-as-a-service can similarly convert part of the investment from upfront capital expenditure into recurring operating expenditure.
Under this model, customers can pay through robot subscriptions, software licences, uptime agreements, or transaction-based pricing.
The approach may be particularly relevant to third-party logistics companies, digital retailers, and fulfilment providers with variable customer demand.
Commercial adoption will depend on standardized interfaces, dependable wireless coverage, system uptime, financing structures, cybersecurity, and clear responsibility for maintenance.
Critical Strategic Questions Addressed
For executives navigating this market transformation, the report addresses four pivotal questions:
Get the complete report here:
https://www.kenresearch.com/saudi-arabia-warehouse-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
Market Entry Timing
With the Saudi Arabia Warehouse Automation Market projected to increase from approximately USD 211.0 million in 2025 to USD 493.4 million by 2031, the analysis identifies entry opportunities across automated storage, conveyors, sortation, robotic picking, autonomous mobile robots, warehouse software, machine vision, systems integration, and lifecycle services.
The market is projected to reach approximately USD 243.1 million in 2026, USD 280.0 million in 2027, USD 322.6 million in 2028, USD 371.7 million in 2029, USD 428.2 million in 2030, and USD 493.4 million by 2031.
Equivalent automation deployments are projected to increase from approximately 96 projects in 2025 to 106 in 2026, 118 in 2027, 130 in 2028, 142 in 2029, 156 in 2030, and 173 by 2031.
Deployment volume is projected to expand at approximately 10.3% annually, while market value grows at 15.2%.
The difference between value and deployment growth demonstrates that future contracts will contain more sophisticated combinations of storage equipment, mobile robotics, software, machine vision, integration, and support.
International automation companies can enter through direct enterprise sales, local system-integrator partnerships, engineering and procurement contracts, or joint ventures.
Direct entry provides greater control over customers, pricing, technical execution, and intellectual property but requires local engineering, project management, working capital, and after-sales support.
A system-integrator partnership can provide faster access to customer relationships, labour, installation capability, and local procurement.
However, suppliers must carefully define technical responsibility, software ownership, warranty obligations, spare-parts availability, and customer escalation.
New entrants can reduce risk by initially targeting modular systems such as vertical lifts, pallet shuttles, autonomous mobile robots, warehouse-management modules, vision systems, or retrofit controls.
Successful reference projects can subsequently support entry into larger turnkey contracts.
Riyadh offers the highest immediate concentration of addressable customers, while Jeddah and the Eastern Province offer opportunities connected to ports, manufacturing, distribution, and industrial logistics.
Regulatory Navigation
The mandate evaluates warehouse licensing, municipal requirements, safety, pharmaceutical storage, cybersecurity, system integration, workforce transition, and operating continuity.
Warehouse automation projects must comply with facility-location, operating-condition, fire-safety, access, and storage requirements.
Physical equipment must be integrated without compromising emergency access, fire protection, loading limits, evacuation routes, or equipment-maintenance space.
Pharmaceutical and healthcare facilities require documented good-storage and distribution practices.
Automation software must preserve batch, expiry, location, movement, and environmental information while supporting auditability.
Connected robots and warehouse-control systems create additional cybersecurity exposure.
A system outage can interrupt receiving, picking, packing, inventory movement, and dispatch across the complete facility.
Operators should therefore define backup procedures, network segregation, access controls, software-update policies, incident response, and manual-continuity processes.
Integration with existing enterprise-resource-planning and warehouse-management systems represents another major risk.
Incorrect interfaces can produce inventory mismatches, duplicate orders, lost tasks, or inconsistent stock records.
Vendors should complete detailed data mapping, interface testing, failure simulation, and staged commissioning before systems assume complete operational control.
Customer contracts should clearly allocate responsibility for site readiness, data quality, third-party software, network availability, operational disruption, and acceptance testing.
Service-level agreements should cover response times, critical spare parts, software support, preventive maintenance, system availability, and performance reporting.
Localization is also commercially important. Customers require technicians, spare parts, remote support, and escalation capability within Saudi Arabia rather than depending entirely on international teams.
Competitive Positioning
The report profiles SSI SCHAEFER, Swisslog, Dematic, Honeywell Intelligrated, Vanderlande, Daifuku, KNAPP, Mecalux, Kardex, and Geekplus.
These companies operate across automated storage, conveyors, sortation, robotic fulfilment, mobile robots, warehouse-control software, pallet automation, vertical storage, machine vision, and lifecycle services.
SSI SCHAEFER competes through automated storage and retrieval systems, conveyors, picking technologies, WAMAS software, and turnkey automation.
Swisslog provides AutoStore integration, robotic fulfilment, pallet automation, and SynQ software.
Dematic serves customers through conveyors, sortation, automated storage, picking technologies, and warehouse-execution systems.
Honeywell Intelligrated provides material handling, robotics, controls, sortation, and warehouse-execution software.
Vanderlande participates across goods-to-person systems, warehouse sorting, robotics, and parcel automation.
Daifuku provides automated storage, automated guided vehicles, conveyors, and factory-logistics systems.
KNAPP specializes in shuttle technology, robotics, artificial-intelligence-based orchestration, warehouse software, and pharmaceutical automation.
Mecalux provides automated storage, pallet shuttles, racking, conveyors, and warehouse-management software.
Kardex competes through vertical storage, mini-load systems, high-bay automation, and lifecycle support.
Geekplus focuses on autonomous mobile robots, goods-to-person fulfilment, and robot orchestration.
Local participants represent approximately 70% of the wider market base, while regional and international participants represent around 30%.
The report identifies approximately 136 active vendors, system integrators, and specialist partners, with eight new entrants identified during the preceding five-year period.
Competition is influenced by installed automated-storage capacity, system throughput, uptime, Saudi project-revenue growth, lifecycle-service margins, project delivery, software depth, local support, and sector references.
Market participants should not evaluate suppliers only through equipment specifications.
The ability to design, integrate, commission, maintain, and expand complete systems is equally important.
Customers also require evidence that a supplier can support operations after installation, maintain critical components, respond to failures, and upgrade software over the system's operating life.
Investment Prioritization
White-space analysis across brownfield retrofits, robotics-as-a-service, cloud warehouse software, pharmaceutical automation, cold-chain systems, fulfilment centres, machine vision, and lifecycle maintenance supports informed capital allocation.
Brownfield retrofits provide a substantial opportunity because approximately 73% of the addressable warehouse base remained non-automated in 2025.
Operators can begin with selected processes rather than automating the complete facility.
Potential entry projects include vertical storage, automated pallet movement, robotic transport, inventory software, dock scheduling, vision-based counting, or selected picking zones.
Phased implementation can reduce capital exposure and allow customers to validate productivity improvements before wider deployment.
Robotics-as-a-service offers recurring-revenue potential and may expand the addressable customer base to businesses unable to fund complete systems upfront.
Providers must nevertheless finance equipment, manage utilization, maintain robots, and define minimum contract periods.
Cloud warehouse software provides another scalable opportunity through subscription licences, implementation, integration, analytics, and support.
Pharmaceutical and cold-chain automation can support stronger margins because compliance, traceability, and temperature requirements create greater differentiation.
Lifecycle services provide recurring revenue after commissioning.
Maintenance contracts, software support, system monitoring, spare parts, training, and upgrades can improve revenue predictability and customer retention.
Investors should evaluate whether providers control both initial integration and long-term support.
Companies dependent only on one-time equipment sales may experience irregular revenue and limited customer ownership.
Businesses combining hardware, software, integration, and recurring services are likely to develop stronger lifetime economics.
Critical Infrastructure and Policy Developments
The report highlights several significant infrastructure and operating developments that will shape market growth:
Riyadh Warehouse and Fulfilment-Corridor Deployment
Riyadh is Saudi Arabia's dominant warehouse-automation hub because it combines retail headquarters, national distribution operations, industrial estates, fulfilment centres, and a large licensed warehouse base.
The region contained approximately 6,763 licensed commercial warehouses covering around 10.7 million square metres during 2024.
This represented approximately 55.3% of the country's licensed warehouses, creating the highest concentration of potential automation customers.
Customer concentration can reduce sales, engineering, travel, and field-service costs for automation providers.
Vendors can establish regional spare-parts warehouses, technical-support teams, training facilities, and demonstration centres within the Riyadh corridor.
System integrators can also develop reusable engineering templates for common warehouse types, including retail distribution, e-commerce fulfilment, pharmaceuticals, food, and industrial storage.
The economics of automation improve when vendors can support several projects through common technical teams and inventory.
However, Riyadh's large project pipeline also increases competition for engineering talent, warehouse customers, and system-integration partners.
Vendors should differentiate through sector experience, commissioning speed, open software interfaces, lifecycle support, and measurable operating outcomes.
Customers should evaluate whether proposed systems are designed for future order growth, product-range changes, and building expansion.
A system optimized only for current throughput may require costly modification when demand increases.
National Logistics-Zone and Port-Linked Automation Expansion
Saudi Arabia's target of 59 logistics zones by 2030 provides a long-term development pipeline for automated logistics infrastructure.
New zones can support distribution near ports, airports, industrial cities, free zones, and major consumption centres.
Automation specified during facility planning can improve ceiling height, storage density, dock flow, power availability, network coverage, fire-safety integration, and future expansion.
Jeddah provides opportunities linked to port activity, imported consumer goods, retail distribution, food, and western-region fulfilment.
The Eastern Province provides opportunities across industrial manufacturing, energy supply chains, chemicals, automotive components, and port-linked logistics.
New logistics zones may also enable shared automation models in which third-party logistics providers serve several customers through common infrastructure.
Shared fulfilment allows smaller retailers and manufacturers to access automated storage and software without financing dedicated facilities.
The commercial model may combine warehouse space, storage, picking, packing, transport, and technology under transaction-based or monthly pricing.
Automation suppliers can participate as equipment providers, software partners, operators, or long-term service contractors.
Software Integration, Cybersecurity and Operational-Continuity Frameworks
Warehouse automation is increasingly dependent on digital coordination between enterprise-resource-planning software, warehouse-management systems, warehouse-control systems, robots, conveyors, sensors, and external delivery platforms.
This integration creates productivity benefits but also increases the operational impact of software failures and cybersecurity incidents.
Customers with high delivery-service requirements cannot tolerate extended outages.
Automation contracts should therefore include system availability targets, backup procedures, data-recovery plans, and clearly defined escalation processes.
Warehouse software should record inventory, tasks, equipment status, user activity, and exceptions in a format that supports operating decisions and audits.
Vendors must also ensure that software interfaces can accommodate future equipment and system changes.
Closed architectures may create dependence on a single supplier and increase the cost of later expansion.
Open interfaces can improve flexibility, but they require stronger integration governance and cybersecurity.
Customers should establish responsibility matrices covering software changes, access permissions, cybersecurity updates, third-party interfaces, and equipment modifications.
Book a discovery call with our experts:
https://www.kenresearch.com/custom-form/saudi-arabia-warehouse-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
Workforce Reskilling and Local Lifecycle-Service Capacity
Saudi delivery operations involved more than 442,000 active drivers during 2024, illustrating the scale of labour-intensive logistics activity connected to the warehouse ecosystem.
Warehouse automation is likely to change the nature of logistics work rather than eliminate every role.
Manual movement and repetitive picking may decline, while demand increases for technicians, controls engineers, software specialists, maintenance planners, data analysts, and automation supervisors.
Warehouse employees must learn how to operate alongside robots, respond to system exceptions, manage digital work queues, and follow new safety procedures.
System suppliers require local installation, commissioning, maintenance, and customer-support capability.
International companies depending entirely on foreign personnel may experience slower response times, higher costs, and limited customer confidence.
Local training partnerships can help develop technicians across mechanical, electrical, controls, software, networking, and robotic systems.
Vendors should also maintain local inventories of high-failure and long-lead components.
A warehouse can lose substantial throughput when a critical sensor, motor, controller, or network component is unavailable.
Lifecycle-service capability will therefore become a central competitive differentiator as the installed automation base expands.
Strategic Value for Decision-Makers
"What distinguishes this analysis is its focus on actionable intelligence," noted Mr. Harsh Saxena, Principal at Ken Research. "Beyond market sizing, we have mapped deployment growth, contract economics, automation penetration, logistics infrastructure, warehouse software, robotics, sector-specific requirements, competitive positioning, and investment white spaces to provide executives with a complete strategic toolkit."
The report delivers essential market intelligence for executives and investors, including:
Detailed segmentation analysis by solution type, including automated storage and retrieval systems, conveyor and sortation systems, automated picking systems, and warehouse-management and control software.
Technology analysis covering fixed automation, autonomous mobile robots, automated guided vehicles, and machine vision and artificial intelligence.
Application analysis covering storage and retrieval, picking and packing, sorting and consolidation, and inventory control and dispatch.
End-use analysis covering e-commerce and retail, food and beverage, pharmaceuticals and healthcare, and manufacturing and contract logistics.
Customer analysis covering large omnichannel retailers, third-party logistics and fulfilment operators, manufacturers and distributors, and public and healthcare supply networks.
Sales-channel analysis covering direct enterprise sales, system-integrator partnerships, engineering and turnkey contracts, and software-subscription channels.
Geographic analysis covering Riyadh, the Makkah Region, the Eastern Province, and other regions. Riyadh remains the dominant market because it contains approximately 55.3% of Saudi Arabia's licensed commercial warehouses.
Historical and forecast models covering 2020-2031, including market value, annual growth, equivalent automation deployments, average contract value, automation penetration, historical CAGR, and forecast CAGR.
The market increased from approximately USD 79.0 million in 2020 to USD 211.0 million in 2025, representing historical annual growth of approximately 21.7%.
It is projected to reach approximately USD 493.4 million by 2031 at a forecast CAGR of 15.2%.
Equivalent deployments increased from approximately 49 projects in 2020 to 96 in 2025 and are projected to reach 173 by 2031.
Average automation contract value increased from approximately USD 1.61 million in 2020 to USD 2.20 million in 2025 and is projected to reach USD 2.85 million by 2031.
Addressable warehouse-automation penetration was estimated at approximately 27% in 2025 and is projected to reach 51% by 2031.
Competitive benchmarking of 10 companies across installed capacity, system throughput, uptime, project-revenue growth, lifecycle-service margins, software depth, sector capability, customer access, localization, and pricing models.
White-space analysis covering brownfield retrofits, robotics-as-a-service, autonomous mobile robots, cloud warehouse-management systems, pharmaceutical automation, cold-chain facilities, machine vision, and lifecycle services.
Regulatory and risk mapping addressing upfront capital requirements, imported equipment, integration complexity, operating disruption, cybersecurity, technical skills, warehouse compliance, spare-parts availability, and system uptime.
"As Saudi Arabia develops logistics zones, expands e-commerce, strengthens pharmaceutical distribution, and increases the sophistication of national supply chains, warehouse automation will become an increasingly important component of the Kingdom's logistics competitiveness," added Harsh Saxena, Principal at Ken Research. "The report provides the data-backed intelligence required to align investment, technology, partnerships, system integration, service capacity, and market-entry strategies with emerging opportunities."
Industry executives seeking access to the complete analysis can contact Ken Research directly or visit:
https://www.kenresearch.com/saudi-arabia-warehouse-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
Related Reports
https://www.kenresearch.com/industry-reports/global-warehouse-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
https://www.kenresearch.com/industry-reports/uae-warehousing-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
https://www.kenresearch.com/uae-warehouse-automation-amrs-as-rs-wes-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
https://www.kenresearch.com/gcc-ai-powered-warehouse-robotics-and-automation-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
https://www.kenresearch.com/gcc-warehouse-pallet-automation-and-amr-integration-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
https://www.kenresearch.com/industry-reports/global-wms-market?utm_source=OpenPR&utm_medium=Referral&utm_campaign=PR
Contact:
Ankur Gupta
ankur.gupta@kenresearch.com
+91 9015378249
Unit 14, Tower B3, Spaze I Tech Business Park, Sohna Road, sector 49 Gurgaon, Haryana - 122001, India
Ken Research delivers strategic market intelligence that drives confident decision-making for industry leaders. With specialized expertise in high-growth markets across emerging economies, the firm provides data-driven insights that translate into competitive advantage for global organizations and investors.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Ken Research Stated Saudi Arabia Warehouse Automation Market to Reach USD 493.4 Million here
News-ID: 4592083 • Views: …
More Releases from Ken Research Pvt Ltd
Ken Research Stated the Philippines Digital Agriculture Platforms Market Will Re …
Comprehensive market analysis highlights the expansion of digital marketplaces, embedded agricultural finance, farm-management solutions, traceability platforms, and data-driven procurement across the Philippines.
Delhi, India - July 2026 - Ken Research released its strategic market analysis titled "Philippines Digital Agriculture Platforms Market," revealing that the market was valued at USD 1,132 million in 2025 and is projected to reach USD 2,100 million by 2031, expanding at a forecast CAGR of 10.85% during…
Ken Research Stated Philippines Dialysis Centre Market to Reach USD 2.84 Billion …
Comprehensive market analysis highlights an 8.50% CAGR, expanding dialysis-patient volumes, stronger PhilHealth coverage, provincial capacity requirements and strategic opportunities across the Philippines' renal-care ecosystem.
Delhi, India - July 2026 - Ken Research released its strategic market analysis titled "Philippines Dialysis Centre Market Size, Share & Forecast, By Service Type, Care Setting & Technology, 2026-2031," revealing that the market was valued at approximately USD 1.74 billion in 2025 and is projected to…
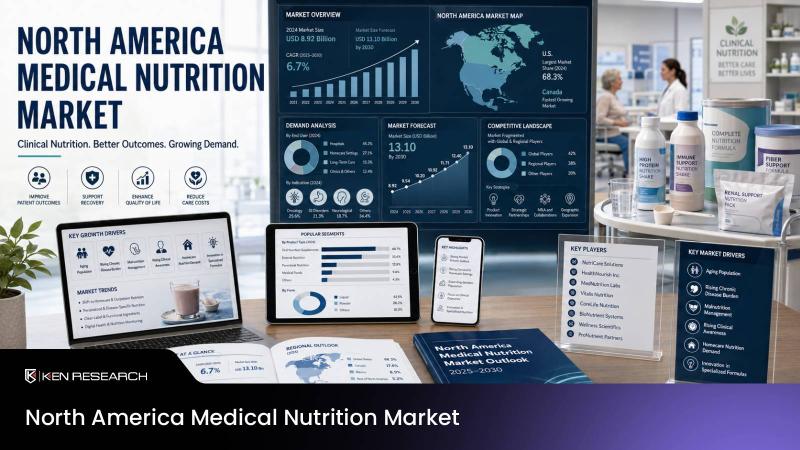
Ken Research Stated North America Medical Nutrition Market to Reached USD 23.37 …
Comprehensive market analysis maps the growth trajectory, investment opportunities, and strategic imperatives for industry leaders operating across North America's rapidly evolving medical-nutrition ecosystem.
Delhi, India - July 29, 2026 - Ken Research released its strategic market analysis titled "North America Medical Nutrition Market Outlook to 2030: Size, Share, Growth and Trends," revealing that the market was valued at USD 16.50 billion in 2024. The market is projected to expand at a…
Ken Research Stated APAC A2P SMS and CPaaS Market to Reach USD 52.68 Billion by …
Comprehensive market analysis maps a 9.3% growth trajectory, expanding authentication demand, CPaaS revenue opportunities, regulatory challenges, and strategic priorities across the Asia-Pacific communications ecosystem.
Delhi, India - July 2026 - Ken Research released its strategic market analysis titled "APAC A2P SMS and CPaaS Market Outlook to 2030: Size, Share, Growth and Trends," revealing that the market was valued at USD 30,850 million in 2024. The industry is projected to reach USD…
More Releases for USD
Flexible Packaging Market Size and Forecast: USD 245.42 Billion (2024), USD 255 …
The numbers reveal a large and slowly expanding market. In 2024, the flexible packaging market was valued at a substantial $245.42 billion. It is projected to grow to $255 billion in 2025 and reach $373.8 billion by 2035. This represents a steady compound annual growth rate (CAGR) of 3.9% over the forecast period (2025-2035). While not explosive, this consistent growth reflects its deep integration into essential sectors like food, beverages,…
Bone Cement Market Outlook USD 1,871.10M-USD 3,512.31M
How Is the Bone Cement Market Supporting the Rise of Modern Orthopedic Surgery?
The Bone Cement Market plays a critical role in modern orthopedic and spinal procedures, acting as a foundational material for joint replacement, fracture fixation, and vertebral stabilization. Bone cement is widely used to anchor implants, restore bone structure, and improve patient mobility-making it an essential component of musculoskeletal care.
In 2025, the global bone cement market was valued at…
US Ostomy Care and Accessories Market USD 4.03B-USD 6.75B
How Is the United States Ostomy Care and Accessories Market Evolving to Meet the Needs of a Growing Patient Population?
The United States Ostomy Care and Accessories Market plays a critical role in improving the quality of life for millions of patients who undergo life-altering surgical procedures involving the digestive or urinary systems. Ostomy care products are essential medical devices designed to manage bodily waste safely and discreetly following surgeries such…
PACS Market USD 5.59B in 2025, USD 9.73B by 2035
Picture Archiving and Communication System (PACS) Market Expands as Digital Imaging Transforms Global Healthcare
Introduction: PACS at the Core of Modern Medical Imaging
The healthcare industry is undergoing a rapid digital transformation, with medical imaging playing a critical role in diagnosis, treatment planning, and patient monitoring. At the heart of this transformation lies the Picture Archiving and Communication System (PACS)-a technology that enables the storage, retrieval, management, and sharing of medical images…
Global HEOR Market USD 1.70B-USD 6.03B
Health Economics and Outcomes Research (HEOR) Market Accelerates as Value-Based Healthcare Redefines Global Decision-Making
Introduction: The Growing Importance of HEOR in Modern Healthcare
The global healthcare industry is undergoing a profound transformation, shifting from volume-driven care models to value-based healthcare systems that prioritize patient outcomes, cost efficiency, and real-world effectiveness. At the center of this transformation lies Health Economics and Outcomes Research (HEOR)-a discipline that evaluates the economic value, clinical outcomes, and…
Foam Tape Market Outlook 2035: Industry Growth from USD USD 4.89 Billion (2025) …
The Foam Tape Market plays a vital role in modern industrial and manufacturing ecosystems. Foam tapes are pressure-sensitive adhesive products manufactured using materials such as polyurethane, polyethylene, PVC, and acrylic foam. These tapes are widely used for bonding, sealing, insulation, cushioning, vibration damping, and noise reduction across multiple industries. Their ability to replace traditional mechanical fasteners like screws, bolts, and rivets has positioned foam tapes as a preferred solution in…

