


Press release
AI Accelerator Chip Market to Reach US$ 377.00 Billion by 2033 as Generative AI and Hyperscale Data Centers Drive Demand; North America Leads with 39% Share NVIDIA, AMD & Intel
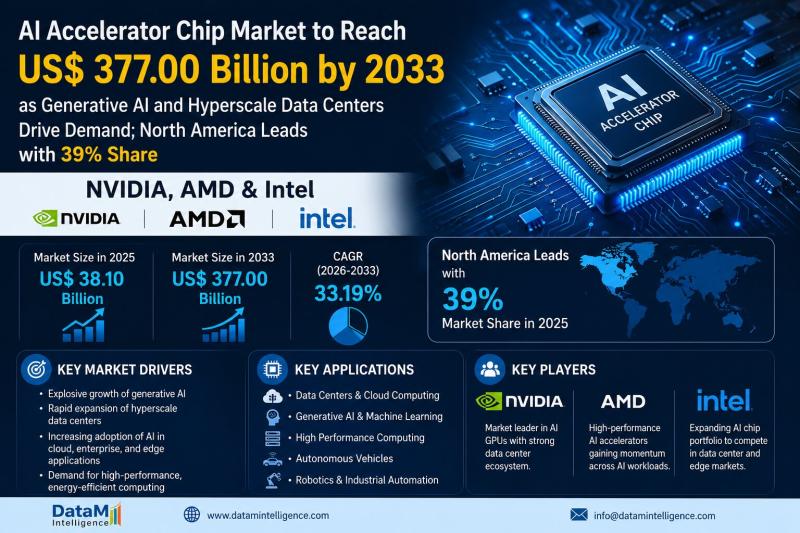
AI Accelerator Chip Market
Download your exclusive sample report today (corporate email gets priority access):
https://www.datamintelligence.com/download-sample/ai-accelerator-chip-market?sindhuri
Growth is strongly supported by rising demand across key application areas such as data center acceleration, cloud AI infrastructure, autonomous vehicles, robotics, healthcare diagnostics, industrial automation, consumer electronics, and intelligent edge computing, where AI accelerator chips deliver faster processing, lower latency, and improved power efficiency. The growing integration of graphics processing units (GPUs), tensor processing units (TPUs), neural processing units (NPUs), field-programmable gate arrays (FPGAs), application-specific integrated circuits (ASICs), and custom AI processors is significantly improving AI model training, real-time inference, and overall computational performance.
Additionally, the rapid expansion of hyperscale data centers, increasing investments in AI infrastructure, and growing enterprise adoption of generative AI and large language models are major growth drivers, as organizations increasingly deploy specialized AI hardware to optimize computing efficiency and reduce operational costs. Rising adoption of AI-enabled healthcare systems, intelligent manufacturing, smart cities, advanced driver-assistance systems (ADAS), and edge AI applications is further accelerating market demand across developed and emerging economies. Ongoing innovation in chip architecture, advanced semiconductor process technologies, chiplet-based designs, high-bandwidth memory integration, and energy-efficient AI computing platforms is also strengthening market expansion.
North America remains the dominant region, supported by the presence of leading semiconductor companies, hyperscale cloud providers, strong investments in AI research, and rapid deployment of AI infrastructure, while Europe is witnessing steady growth driven by increasing investments in industrial automation, automotive AI, and digital transformation initiatives. Asia-Pacific is expected to emerge as a high-growth region due to expanding semiconductor manufacturing capabilities, rapid AI adoption across enterprises, increasing government support for AI innovation, and growing investments in cloud infrastructure across countries such as China, Japan, South Korea, and India.
AI Accelerator Chip Market: Competitive Intelligence
NVIDIA Corporation, Advanced Micro Devices (AMD), Intel Corporation, Qualcomm Technologies, Inc., Broadcom Inc., Marvell Technology, MediaTek Inc., Samsung Electronics Co., Ltd., Google LLC, and Huawei Technologies Co., Ltd. are the major global players shaping the competitive landscape of the AI Accelerator Chip Market. These companies provide advanced AI accelerator processors, GPUs, NPUs, TPUs, ASICs, and high-performance AI computing solutions used across data centers, cloud platforms, enterprise infrastructure, edge devices, automotive systems, and consumer electronics.
The AI Accelerator Chip Market is primarily driven by the growing demand for high-performance AI computing, increasing deployment of generative AI applications, expanding cloud infrastructure, and rising adoption of machine learning across industries. Continuous investments in semiconductor innovation, AI model optimization, and energy-efficient computing architectures are further strengthening market adoption globally.
Competitive differentiation is driven by processing performance, power efficiency, scalability, software ecosystem support, memory bandwidth, and AI workload optimization. NVIDIA and AMD emphasize high-performance GPU computing for AI training and inference, while Intel and Qualcomm focus on AI acceleration across enterprise, edge, and mobile platforms. Google continues expanding its custom Tensor Processing Units (TPUs) for cloud AI workloads, while Broadcom, Marvell, MediaTek, Samsung Electronics, and Huawei strengthen their market presence through advanced AI semiconductor solutions for networking, edge computing, smartphones, and enterprise infrastructure. Strategic priorities include developing next-generation AI accelerator architectures, improving chip performance per watt, expanding AI software ecosystems, advancing heterogeneous computing technologies, and strengthening partnerships across the global AI infrastructure ecosystem.
Get Customization in the report as per your requirements:
https://www.datamintelligence.com/customize/ai-accelerator-chip-market?sindhuri
Recent Key Developments - United States & North America
✅ June 2026: Rapid expansion of hyperscale AI data centers and enterprise generative AI deployments significantly increased demand for high-performance AI accelerator chips across the United States, driving investments in next-generation GPU, ASIC, and AI processor technologies.
✅ May 2026: Major cloud service providers expanded AI infrastructure and custom silicon initiatives, accelerating adoption of AI accelerator chips optimized for large language models (LLMs), inference workloads, and high-performance computing (HPC).
✅ 2026: Growing government support for domestic semiconductor manufacturing and advanced AI infrastructure strengthened investments in AI accelerator chip design, packaging, and fabrication capabilities across North America.
Recent Key Developments - Japan & Asia-Pacific
✅ July 2026: Expansion of advanced semiconductor manufacturing and AI computing infrastructure boosted production and deployment of AI accelerator chips across Japan, Taiwan, South Korea, and China.
✅ Early 2026: Rising investments in edge AI, autonomous vehicles, robotics, and smart manufacturing accelerated demand for energy-efficient AI accelerator processors throughout the Asia-Pacific region.
✅ 2026: Government-backed semiconductor and artificial intelligence initiatives promoted R&D in next-generation AI chips, advanced packaging technologies, and high-bandwidth memory (HBM) integration across Asia-Pacific.
Recent Key Developments - Product & Technology Innovation
✅ 2026: Next-Generation AI Accelerators: Advances in GPU, TPU, ASIC, and neural processing unit (NPU) architectures significantly improved AI training and inference performance while reducing power consumption for generative AI and large-scale machine learning workloads.
✅ Advanced Chip Packaging & Memory Integration: Growing adoption of chiplet architectures, 2.5D/3D packaging, and high-bandwidth memory (HBM) enhanced computing efficiency, bandwidth, and scalability for AI accelerator platforms.
✅ Energy-Efficient AI Computing: Increasing innovation in low-power AI accelerator chips, edge AI processors, and optimized semiconductor designs enabled faster real-time AI processing while improving energy efficiency across cloud, enterprise, and edge applications.
M&A / Strategic Activity
Recent strategic acquisitions, partnerships, and ecosystem developments shaping the AI Accelerator Chip Market:
NVIDIA Corporation - AI infrastructure and ecosystem expansion
NVIDIA continues to strengthen its AI accelerator ecosystem through strategic partnerships with cloud service providers, OEMs, hyperscale data center operators, and software developers, expanding deployment of GPU-based AI platforms for generative AI, large language models (LLMs), and high-performance computing.
Advanced Micro Devices (AMD) - AI accelerator portfolio expansion
AMD has accelerated investments in AI computing through strategic acquisitions, software ecosystem development, and collaborations with hyperscalers to expand adoption of Instinct AI accelerators for enterprise AI training and inference workloads.
Intel Corporation - AI accelerator and edge AI partnerships
Intel is expanding its AI accelerator portfolio through collaborations across cloud computing, telecommunications, industrial automation, and edge AI, strengthening deployment of Gaudi AI accelerators and AI-enabled Xeon platforms.
Qualcomm Technologies - Edge AI ecosystem development
Qualcomm continues to expand strategic partnerships with smartphone manufacturers, automotive OEMs, and IoT solution providers to accelerate deployment of AI accelerator technologies for on-device inference and edge computing applications.
Google LLC - Custom AI accelerator ecosystem integration
Google is strengthening its AI infrastructure through continuous expansion of Tensor Processing Unit (TPU) deployments across Google Cloud, supporting enterprise AI, generative AI services, and large-scale machine learning workloads.
New Product/Chip Launches & Deployments
Recent innovations and deployments in the AI accelerator chip space:
NVIDIA Corporation - Blackwell AI accelerator platform
NVIDIA introduced its Blackwell AI platform featuring next-generation GPU architecture optimized for generative AI, trillion-parameter model training, inference acceleration, and high-performance AI data centers.
AMD - Instinct MI-series AI accelerators
AMD expanded its Instinct accelerator portfolio with advanced GPUs designed for large-scale AI training, scientific computing, cloud AI infrastructure, and enterprise generative AI deployments.
Intel Corporation - Gaudi AI accelerators
Intel enhanced its Gaudi AI accelerator family to deliver improved performance and cost-efficient AI model training while expanding software support for enterprise and cloud AI environments.
Google Cloud - Next-generation Tensor Processing Units (TPUs)
Google expanded deployment of next-generation TPU accelerators to improve AI model training efficiency, inference performance, and scalability across cloud-native AI applications.
Qualcomm Technologies - Snapdragon AI platforms
Qualcomm introduced advanced AI processing platforms featuring dedicated neural processing units (NPUs) for smartphones, automotive systems, extended reality (XR), and edge AI applications requiring low-latency inference.
R&D & Technological Advancements
Next-generation AI accelerator architectures
Continuous R&D focuses on improving AI accelerator architectures with higher computing throughput, enhanced memory bandwidth, and lower power consumption to support increasingly complex foundation models.
Chiplet-based AI processor design
Manufacturers are investing in chiplet architectures that improve scalability, manufacturing efficiency, and performance while enabling faster development of high-performance AI accelerators.
Energy-efficient AI computing
Research is accelerating toward low-power AI accelerator designs that reduce energy consumption in hyperscale data centers while maintaining high computational performance for AI training and inference.
High-bandwidth memory (HBM) integration
Advanced packaging technologies integrating HBM are enhancing memory capacity and data transfer speeds, significantly improving AI accelerator performance for large language models and generative AI workloads.
Edge AI accelerator innovation
Companies are developing compact AI accelerators optimized for edge devices, enabling real-time AI inference across autonomous vehicles, industrial automation, robotics, healthcare devices, and smart consumer electronics.
Market Drivers & Emerging Trends
» Rapid adoption of generative AI and large language models is significantly increasing demand for high-performance AI accelerator chips across cloud and enterprise infrastructure.
» Expansion of hyperscale data centers and AI cloud services is driving large-scale deployment of advanced AI accelerator hardware.
» Increasing enterprise investments in AI-driven automation, analytics, and intelligent applications are accelerating adoption of dedicated AI processors.
» Growing demand for edge AI computing is boosting deployment of low-power AI accelerators in smartphones, autonomous vehicles, robotics, industrial IoT, and smart devices.
» Advancements in chiplet architecture, high-bandwidth memory, and advanced semiconductor packaging are enhancing AI accelerator performance and scalability.
» Rising investments in sovereign AI infrastructure and regional semiconductor manufacturing are strengthening AI accelerator supply chains and fostering innovation across global AI ecosystems.
Buy Now & Unlock 360° Market Intelligence:
https://www.datamintelligence.com/buy-now-page?report=ai-accelerator-chip-market?sindhuri
Segments Covered in the Global AI Accelerator Chip Market:
By Processing Type
The market is segmented into training processors (40%), inference processors (60%). Inference processors dominate the market due to their widespread deployment across edge devices, cloud platforms, autonomous systems, and enterprise AI applications, where real-time decision-making and low-latency performance are critical. Training processors are witnessing strong growth driven by increasing investments in large language models (LLMs), generative AI, and hyperscale data center infrastructure requiring high computational power for AI model development.
By Chip Type
The market is segmented into graphics processing units (GPUs) (48%), application-specific integrated circuits (ASICs) (24%), field-programmable gate arrays (FPGAs) (16%), central processing units (CPUs) (8%), and others (4%). GPUs lead the market due to their superior parallel processing capabilities, making them the preferred choice for AI model training and high-performance computing workloads. ASICs are gaining rapid adoption for AI inference owing to their high efficiency and lower power consumption, while FPGAs are increasingly used in edge AI and customizable acceleration applications. CPUs and other specialized processors continue to support general-purpose computing and niche AI deployments.
By Technology
The market is divided into cloud AI acceleration (46%), edge AI acceleration (34%), and hybrid AI acceleration (20%). Cloud AI acceleration dominates the segment due to extensive deployment by hyperscale cloud service providers supporting AI model training, analytics, and generative AI workloads. Edge AI acceleration is expanding rapidly with growing adoption of autonomous vehicles, smart manufacturing, robotics, and IoT devices requiring real-time data processing. Hybrid AI acceleration is gaining traction as enterprises integrate cloud and edge computing for optimized AI performance and scalability.
By End-User
The market is segmented into IT & telecommunications (30%), healthcare (14%), automotive (18%), banking, financial services & insurance (BFSI) (12%), retail & e-commerce (10%), manufacturing (9%), and others (7%). IT & telecommunications dominates the market due to rising investments in cloud infrastructure, hyperscale data centers, and AI-powered network optimization. Automotive is witnessing significant growth driven by autonomous driving technologies and advanced driver assistance systems (ADAS). Healthcare, BFSI, retail, and manufacturing are increasingly adopting AI accelerator chips for medical imaging, fraud detection, personalized recommendations, predictive maintenance, and intelligent automation.
By Region
North America - 39% Share
North America leads the market owing to the presence of leading AI chip manufacturers, hyperscale cloud providers, advanced semiconductor ecosystem, and substantial investments in artificial intelligence, data centers, and high-performance computing across the United States and Canada.
Europe - 24% Share
Europe is driven by increasing AI adoption across automotive, industrial automation, healthcare, and financial services, supported by government initiatives promoting semiconductor innovation and digital transformation in countries including Germany, France, and the UK.
Asia Pacific - 28% Share
Asia Pacific is expanding rapidly due to strong semiconductor manufacturing capabilities, growing AI investments, rapid deployment of cloud infrastructure, and increasing adoption of AI technologies across China, Japan, South Korea, Taiwan, and India.
Request for 2 Days FREE Trial Access: https://www.datamintelligence.com/reports-subscription?sindhuri
✅ Competitive Landscape
✅ Technology Roadmap Analysis
✅ Sustainability Impact Analysis
✅ KOL / Stakeholder Insights
✅ Consumer Behavior & Demand Analysis
✅ Import-Export Data Monitoring
✅ Live Market & Pricing Trends
Contact Us:
Sai Kiran
Business Development Manager
DataM Intelligence 4market Research LLP
6th Floor, M2 Tech Hub, Lalitha Nagar, Habsiguda,
Secunderabad, Hyderabad, Telangana 500039
USA: +1 877-441-4866
Email: Sai.k@datamintelligence.com
About Us -
DataM Intelligence is a Market Research and Consulting firm that provides end-to-end business solutions to organizations from Research to Consulting. We, at DataM Intelligence, leverage our top trademark trends, insights and developments to emancipate swift and astute solutions to clients like you. We encompass a multitude of syndicate reports and customized reports with a robust methodology. Our research database features countless statistics and in-depth analyses across a wide range of 6300+ reports in 40+ domains creating business solutions for more than 200+ companies across 50+ countries; catering to the key business research needs that influence the growth trajectory of our vast clientele.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release AI Accelerator Chip Market to Reach US$ 377.00 Billion by 2033 as Generative AI and Hyperscale Data Centers Drive Demand; North America Leads with 39% Share NVIDIA, AMD & Intel here
News-ID: 4580678 • Views: …
More Releases from DataM Intelligence 4Market Research LLP
Japan Flying Cars Market (2035): eVTOL Aircraft, Passenger Drones & Electric Pro …
DataM Intelligence has released a new research report titled "Japan Flying Cars Market Size 2026". The report delivers in-depth insights into key market dynamics, including regional growth trends, market segmentation, CAGR projections, and the revenue performance of leading industry players. It also highlights major growth drivers shaping the market landscape. Designed to provide a clear and comprehensive perspective, the report offers a detailed view of the current market size in…
Why Is the Electric Vehicle (EV) Testing, Inspection & Certification Market Beco …
The Global Electric Vehicle Testing, Inspection and Certification Market reached US$ 2.99 billion in 2025 and is expected to reach US$ 8.73 billion by 2035, growing at a CAGR of 9.94% during the forecast period 2026-2035.
Growth is driven by the increasing adoption of electric vehicles (EVs) and the growing need to ensure vehicle safety, performance, reliability, and regulatory compliance. Testing, inspection, and certification services are essential for evaluating battery systems,…
Japan CRISPR-Cas9 Gene Editing Market (2033): CRISPR Reagents, Gene & Cell Thera …
DataM Intelligence has released a new research report titled "Japan CRISPR-Cas9 Gene Editing Market Size 2026". The report delivers in-depth insights into key market dynamics, including market segmentation, CAGR projections, end-user trends, technology adoption, and the competitive landscape. It also highlights major growth drivers shaping Japan's gene-editing ecosystem. Designed to provide a clear and comprehensive perspective, the report offers a detailed view of the current market size in terms of…
Why Is the Lithium-Ion Battery Testing Equipment Market Becoming a Key Investmen …
The Global Lithium-Ion Battery Testing Equipment Market was valued at US$ 875.44 million in 2026 and is expected to reach US$ 1,409.78 million by 2035, growing at a CAGR of 5.40% during the forecast period 2026-2035.
Growth is driven by increasing demand for safe, reliable, and high performance lithium-ion batteries across electric vehicles, consumer electronics, and energy storage systems. Battery testing equipment is essential for evaluating battery performance, safety, capacity, durability,…
More Releases for Chip
Chinese chip manufacturers have launched the PIN TO PIN replacement chip for the …
For a long time, ADI's AD9361 has been regarded as the "gold standard" in the field of software-defined radio and 4G/5G small base stations due to its high integration, wide frequency band coverage and reconfigurable features. However, supply chain risks and cost pressures have prompted the industry to urgently seek stable and reliable alternatives.
Image: https://ecdn6.globalso.com/upload/p/5298/image_other/2026-05/ad9361-1.png
The TRX9361 RF transceiver chip launched by China chips manufacturer precisely addresses this issue, achieving Pin-to-Pin…
Evolving Market Trends In The Artificial Intelligence Chip Industry: Atom Ai Chi …
The Artificial Intelligence Chip Market Report by The Business Research Company delivers a detailed market assessment, covering size projections from 2025 to 2034. This report explores crucial market trends, major drivers and market segmentation by [key segment categories].
What Is the Expected Artificial Intelligence Chip Market Size During the Forecast Period?
The market size of artificial intelligence chips has seen a significant surge over the past few years. It is anticipated to…
5G Radio Frequency Chip (RF Chip) Market Report 2024 - 5G RF Chip Market Size An …
"The Business Research Company recently released a comprehensive report on the Global 5G Radio Frequency Chip (RF Chip) Market Size and Trends Analysis with Forecast 2024-2033. This latest market research report offers a wealth of valuable insights and data, including global market size, regional shares, and competitor market share. Additionally, it covers current trends, future opportunities, and essential data for success in the industry.
According to The Business Research Company's, The…
5G Radio Frequency Chip (RF Chip) Market Report 2024 - RF Chip Market Size And T …
"The Business Research Company recently released a comprehensive report on the Global 5G Radio Frequency Chip (RF Chip) Market Size and Trends Analysis with Forecast 2024-2033. This latest market research report offers a wealth of valuable insights and data, including global market size, regional shares, and competitor market share. Additionally, it covers current trends, future opportunities, and essential data for success in the industry.
According to The Business Research Company's,…
Chip Resistor R CHIP Market Size 2024 to 2031.
Market Overview and Report Coverage
A chip resistor, also known as an R CHIP, is an electrical component widely used in electronic circuits to control the flow of electric current. These resistors are small in size and are surface mountable, making them ideal for high density circuit board applications.
The Chip Resistor R CHIP Market is expected to experience steady growth in the coming years, with a projected CAGR of…
5G Radio Frequency Chip RF Chip Market Size 2024 to 2031.
Market Overview and Report Coverage
A 5G Radio Frequency Chip, also known as an RF Chip, is a key component in enabling the high-speed data transmissions required for next-generation wireless networks. These chips are used in devices such as smartphones, tablets, IoT devices, and other connected devices to facilitate the transmission of data over 5G networks.
The future outlook for the 5G Radio Frequency Chip RF Chip Market is promising,…

