
Press release
Middle East Data Center Construction Market Investment to Reach USD 11.39 billion by 2031 | Arizton
The question every operator and investor is now asking is the same one: does the war break the growth story, or does the growth story outlast the war?
How Big Is the Middle East Data Center Construction Market?
The short answer: large enough that even a geopolitical shock has not reversed its trajectory.
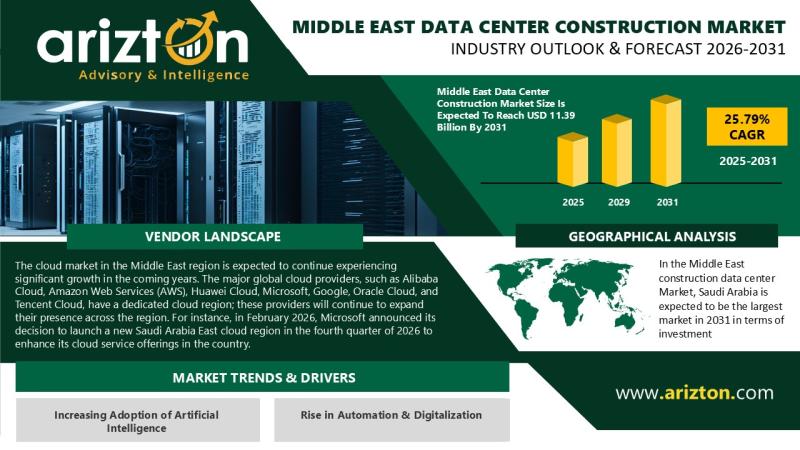
The Middle East data center construction market is projected to reach USD 11.39 billion by 2031, growing at a CAGR of 25.79%.
This is not incremental expansion. It is a structural transformation driven by converging forces, rising cloud adoption, AI workload demand, edge computing proliferation, and the push from governments across the GCC to digitalize entire national economies on accelerated timescales. The GCC data center construction market sits at the epicenter of this buildout, with Saudi Arabia, UAE, Qatar, and Bahrain all running simultaneous, large-scale infrastructure programmes.
Saudi Arabia is projected to hold approximately 35% of regional investment share by 2031, making it the market's dominant force. The UAE follows, then Israel, Turkey, Kuwait, Qatar, Oman, and Bahrain, each at a different stage of maturity but all expanding.
Key Insight: The Middle East data center market is not driven by a single country or a single technology trend. It is running on parallel engines, sovereign capital, hyperscaler expansion, and AI infrastructure demand, which is precisely why short-term disruption has not derailed the growth curve.
Request Sample: https://www.arizton.com/request-sample/5129
What Is Driving Middle East Data Center Market Growth?
Three structural forces explain why the market is growing as fast as it is, and why that growth was already baked in before the current conflict.
1. The first is national AI strategy. Saudi Arabia's National Strategy for Data and Artificial Intelligence, led by the Saudi Data and AI Authority, targets global AI leadership by 2030 through investment incentives, talent development, advanced infrastructure including Project NEOM, and AI integration across healthcare, education, finance, and government. The UAE's Digital Government Strategy 2025 and its National Innovation Strategy are pushing cloud, AI, Web 3.0, and Metaverse infrastructure at a comparable pace. In December 2025, Dubai's leadership held high-level discussions with Elon Musk on AI, space, and digital infrastructure - a signal of how seriously the region treats data infrastructure as geopolitical capital.
2. The second is hyperscaler commitment. AWS, Microsoft Azure, Google Cloud, Oracle, Alibaba Cloud, Huawei Cloud, and Tencent Cloud all operate dedicated cloud regions in the Middle East. In February 2026, Microsoft announced a new Saudi Arabia East cloud region scheduled for Q4 2026. In December 2025, AWS launched its AI Factory offering, enabling enterprises to run NVIDIA GPUs, Trainium chips, and advanced networking inside their own facilities, extending AI infrastructure demand well beyond public cloud campuses.
3. The third is AI workload infrastructure. High-density AI compute cannot run on conventional air-cooled rack infrastructure. Across the Middle East, operators are responding with a rapid shift to liquid cooling and immersion cooling architectures.
Liquid cooling investments accounted for approximately 41% of total cooling technique spend in 2025 and are projected to reach approximately 54% by 2031.
This shift is not cosmetic. It represents a fundamental redesign of what a Middle East data center looks like, how it is built, how it consumes power, and how much it costs to construct. In April 2025, Khazna Data Centers announced a 100 MW AI-ready campus near Ankara, designed specifically to support high-density AI compute and next-generation cloud workloads.
1. Liquid Cooling Share of Investment (2025): ~41%
2. Liquid Cooling Share of Investment (2031): ~54%
3. AWS AI Factory: Launched December 2025
4. Microsoft Saudi Arabia East Region: Scheduled Q4 2026
Know More: https://www.arizton.com/market-reports/middle-east-data-center-construction-market
What Did the 2026 Attacks Actually Do to Middle East Data Center Infrastructure?
This is where the market's story gets complicated - and where the standard growth forecast requires additional context.
The Israel-Iran conflict that escalated in June 2025 did not stay contained. Iran's large-scale retaliatory missile and drone attacks targeted the UAE, Saudi Arabia, Bahrain, Qatar, and Kuwait, countries hosting US military bases and strategic infrastructure. Data centers, despite being civilian in nature, entered the conflict perimeter.
The first publicly confirmed physical attacks on hyperscale data centers in the Middle East occurred in early March 2026, establishing a precedent the industry cannot ignore.
What was confirmed:
1. Amazon Web Services facilities in the UAE and Bahrain were impacted, with multiple sites facing operational disruption
2. Pure Data Centres Group's campus in Abu Dhabi suffered reported damage
3. An Oracle facility in Dubai was separately attacked
4. Two UAE-based facilities were directly struck; the Bahrain facility experienced nearby impact requiring emergency response protocols
These are not theoretical risk scenarios. They are documented incidents - and they have permanently altered how geopolitical risk is priced for Middle East data center investment.
Bottom Line: Before March 2026, physical attack on hyperscale data center infrastructure in the Middle East was treated as a tail risk. After March 2026, it is a base-case variable. Every investment decision made in this region now carries that calculation.
How Has the War Reshaped Investment Behaviour in the Market?
The market has not collapsed. But it has stratified, and the terms of engagement for new capital have changed materially.
Pure Data Centres Group has already publicly paused new Middle East investments, citing geopolitical instability, material shortages, and infrastructure vulnerability concerns. This is the clearest indication that the attacks have moved from headline risk to balance sheet reality for at least one major operator.
The financial consequences are operating simultaneously at multiple levels.
At the operational level, rising energy prices driven by the conflict's disruption of nearly 20% of global oil supply routes are increasing data center operating costs across the region. Supply chain disruptions triggered by the war are extending construction timelines and inflating build costs - making large-scale deployments more complex and more expensive to execute.
At the capital level, the cost of debt and equity for Middle East data center projects will rise. Investors will demand higher returns to compensate for elevated conflict risk. Insurance premiums for facilities in affected markets are increasing. Stricter due diligence and risk assessment frameworks are becoming standard prerequisites for new capital commitments.
At the strategic level, the conflict is reshaping where within the region new investment flows. Sub-markets perceived as lower-risk, Oman's Salalah, Turkey's Ankara corridor, Israel's Negev and Haifa zones, are drawing fresh interest from operators seeking regional exposure without proximity to the primary conflict zones.
1. Global oil supply disruption attributed to the conflict: ~20%
2. Operators that have publicly paused Middle East investment: Pure Data Centres Group (confirmed)
3. Emerging lower-risk sub-markets: Salalah (Oman), Ankara (Turkey), Negev and Haifa (Israel)
Key Insight: The war has not broken the Middle East data center investment thesis. It has sorted the market into risk tiers - and investors are now far more deliberate about which tier they are entering, on what terms, and with what contingencies built in.
Will the Middle East Data Center Market Still Reach USD 11.39 Billion by 2031?
The demand side has not changed. AI adoption is accelerating. Cloud penetration is deepening. National digitalization mandates are being executed with sovereign capital behind them. Saudi Arabia and the UAE are both too far into multi-year infrastructure programmes - and too strategically committed to digital leadership, to reverse course because of a conflict that, while serious, remains geographically concentrated.
What has changed is the cost and conditions under which that demand gets met.
Higher insurance and financing costs will increase the total investment required to hit the same physical capacity targets. Some global capital will migrate toward lower-conflict-exposure markets at the margin. Operators will build more redundancy, hardening, and geographic distribution into their Middle East footprints, raising per-megawatt construction costs while simultaneously increasing resilience.
The net effect is a market that reaches a similar destination by 2031, through a more expensive, more cautious, and more structurally resilient path. The growth is real. The risk is now priced.
Conclusion: The Middle East Data Center Market Is Not Choosing Between Growth and Risk - It Is Managing Both
What makes the Middle East data center story genuinely unusual is that neither the growth nor the risk is exaggerated. A 25.79% CAGR through 2031 is real, underwritten by government mandates, hyperscaler commitments, and AI infrastructure economics that have no short-term substitute. Physical attacks on AWS, Oracle, and Pure Data Centres facilities in early 2026 are also real, and they have permanently changed how the industry thinks about what it means to build in this region.
The operators and investors who will define the market through 2031 are not the ones choosing between these realities. They are the ones building capital structures, risk frameworks, and infrastructure designs that hold up inside both of them simultaneously.
About Us:
Founded in 2017, Arizton Advisory & Intelligence delivers data-driven market research and strategic consulting that empowers clients to make informed decisions and drive growth. Combining quantitative and qualitative insights, we provide in-depth analysis across industries including Agriculture, Consumer Goods, Technology, Automotive, Healthcare, Data Centers, and Logistics. Recognized by top-tier media, our expert team transforms complex market data into actionable strategies, helping clients anticipate trends, seize opportunities, and stay ahead of the competition.
Contact Us
Mail: enquiry@arizton.com
Contact Us: https://www.arizton.com/contact-us
Website: https://www.arizton.com/
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Middle East Data Center Construction Market Investment to Reach USD 11.39 billion by 2031 | Arizton here
News-ID: 4570781 • Views: …
More Releases from Arizton Advisory & Intelligence
South Korea Data Center Colocation Market to Reach USD 3.64 Billion by 2031, wit …
South Korea's data center colocation market was valued at USD 1.35 billion in 2025 and is expected to reach USD 3.64 billion by 2031, growing at a CAGR of 28.32%. The market's expansion is creating opportunities beyond traditional colocation capacity, particularly in AI-ready infrastructure, power supply, and advanced cloud computing. However, electricity economics could become a significant consideration for operators. Industrial electricity prices ranged between USD 0.11 and USD 0.13…
Latin America Sustainable Data Center Market to Reach USD 5.37 Billion by 2031, …
Latin America's sustainable data center market is projected to grow from USD 1.65 billion in 2025 to USD 5.37 billion by 2031, at a CAGR of 21.73%. This growth is creating opportunities across the data center value chain as developers expand capacity and invest in infrastructure designed to meet evolving operational and performance requirements.
For equipment manufacturers, engineering firms, investors, and data center developers, this expansion presents opportunities to strengthen regional…
Robotic Lawn Mowers Research Report to 2031: Market Size, Sales Volume, Growth D …
The global robotic lawn mowers market is projected to grow from USD 3.45 billion in 2024 to USD 7.01 billion by 2030, at a CAGR of 4.73%. Smart technology adoption, labor cost pressures, and expanding landscaping requirements are creating opportunities for manufacturers to differentiate their products and expand into new markets. These report by Arizton provide stakeholders, investors, manufacturers with data backed insights to identify strategic opportunities in fast scaling…
Europe Elevator and Escalator Market Size to Reach 164.03 Thousand Units by 2031 …
Arizton estimates that Europe elevator and escalator market by new installations is projected to grow from 140.37 thousand units in 2024 to 164.03 thousand units by 2030, at a CAGR of 2.63%. The market opportunity is shifting toward infrastructure investment and the replacement of aging vertical transportation systems. Airport and railway expansion projects are creating demand for high-capacity installations, while energy-efficiency requirements are strengthening the case for upgrading existing equipment.…
More Releases for East
Middle East Aircraft Engine Market - Middle East Industry Size & Growth Analysis …
Middle East Aircraft Engine Market Enters a Quiet Reinvention Phase as Local Capabilities and Smart Engines Redefine Growth
The Middle East Aircraft Engine Market is no longer just riding on passenger traffic growth-it's quietly being reshaped by deeper structural changes that many industry observers are only beginning to notice. Currently valued at around USD 8.6 billion in 2024, the market is expected to reach approximately USD 14.2 billion by 2031, growing…
Potential in the East - How the East of Germany is developing
More and more people are discovering eastern Germany - and no longer just as a vacation destination, but as a new place to live and work. What was considered an economically weaker region for decades is now developing into an area full of dynamism, innovation and quality of life. Cities such as Leipzig, Dresden, Jena and Rostock are attracting people who are looking for affordable housing, career prospects and an…
Middle East Auto Component Market Significant Growth over Forecast Period 2020-2 …
Auto Component Market is those markets which are manufacture components or parts required in the automobile industry. Middle East Auto Components market was valued at $ 28 billion in 2019 and is expected to surpass $ 39.7+ billion by 2028. Projected growth in the market can be recognized as snowballing automobile vehicle fleet and rising manufacture and infrastructural activities across different countries of the region. Moreover, mounting demand for vehicle…
Studying the Middle East Yacht Market,Studying the Middle East Yacht Industry, S …
Latest industry research report on: Studying the Middle East Yacht Market : Industry Size, Share, Research, Reviews, Analysis, Strategies, Demand, Growth, Segmentation, Parameters, Forecasts
Our analysts believe that the long-term outlook for the yacht market in the Middle East is positive. Demand for yachts in the Middle East has remained stable and is expected to continue being so. Yachting has emerged as a key aspect of the luxury lifestyle in the…
Middle East Railway Sector Middle East Railway Sales Report
For Report Sample Contact: neeraj@kuickresearch.com or +91-11-47067990
Report Table of Contents
Middle East Outlook
1.1 Countries Overview
1.2 Middle East Economy
1.3 Transportation in Middle East
Middle East Rail Transport Outlook
2.1 Overall Status of Rail Transport in Middle East
2.2 Trends in Railway Infrastructure Development in Middle East
Saudi Arabia
3.1 Existing Railway Infrastructure
3.2 Proposed/Planned Railway Infrastructure
3.3 Regulatory Framework
3.4…
Digital Signage Expo East & Interactive Technology East Debut to Accolades from …
Philadelphia, PA –Digital Signage Expo East (DSE East) and Interactive Technology Expo East (ITEE), the regional versions of the international Digital Signage Expo and Interactive Technology Expo, today announced that qualified attendees to the show surpassed expectations and numbered in excess of 900! (Final and more comprehensive attendance statistics are pending)."
The new regional event delivered on its promise to attract a more regional audience, of end-users, brand and advertising executives…