


Press release
Photovoltaic Market to Hit USD 267.2 Billion by 2035 at 9.0% CAGR
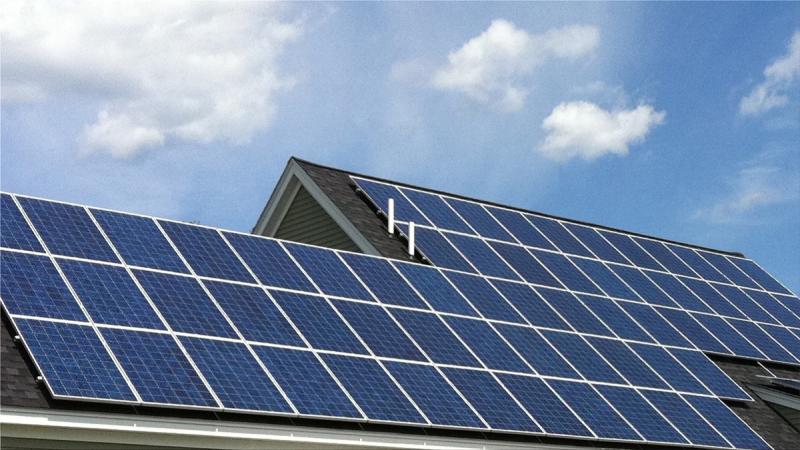
Photovoltaic Market
Market Overview
The Photovoltaic (PV) Market encompasses the design, manufacturing, installation, operation, and maintenance of solar photovoltaic systems that directly convert sunlight into electricity using semiconductor materials that exhibit the photovoltaic effect. Photovoltaic technology is the fastest-growing and most widely deployed renewable energy technology globally, driven by dramatic cost reductions over the past decade (solar module prices have declined by 85-90% since 2010), modularity and scalability (from small residential rooftop systems to utility-scale power plants exceeding 1 GW), and the global imperative to decarbonize electricity generation.
The PV market includes crystalline silicon (c-Si) technologies (monocrystalline and polycrystalline, which dominate with over 95% market share), thin-film technologies (cadmium telluride/CdTe, copper indium gallium selenide/CIGS, amorphous silicon/a-Si, and emerging perovskite and tandem cells), balance of system (BOS) components (inverters, mounting structures, tracking systems, cabling, combiner boxes, monitoring systems, energy storage integration), and associated services (project development, engineering, procurement, construction, operations and maintenance, asset management).
PV systems are deployed across three primary segments: utility-scale (ground-mounted PV power plants feeding electricity into the grid at transmission or distribution voltage, typically >5 MW, often with single-axis tracking and increasingly co-located with battery storage), commercial and industrial (rooftop or ground-mounted systems for office buildings, warehouses, factories, retail centers, typically 50 kW to 5 MW, often for self-consumption to reduce electricity bills), and residential (rooftop or ground-mounted systems for single-family homes, typically 3-15 kW, often with net metering, feed-in tariffs, or behind-the-meter battery storage). The market is global, with major manufacturing concentrated in China (over 80% of global module production), and major deployment across Asia-Pacific (China, India, Japan, Australia, Vietnam, South Korea), Europe (Germany, Spain, Netherlands, Poland, Italy, France, UK), North America (US, Canada), Latin America (Brazil, Chile, Mexico, Argentina), and the Middle East & Africa (UAE, Saudi Arabia, Egypt, South Africa).
The primary growth driver for the Photovoltaic Market is the unsubsidized levelized cost of electricity (LCOE) of solar PV, which is now the cheapest source of new electricity generation in most major economies, undercutting both new coal and gas plants and often competing with existing fossil generation. According to the International Energy Agency (IEA) and BloombergNEF, utility-scale solar PV LCOE has fallen to USD 20-40 per MWh in sunny regions, USD 30-60 per MWh in moderate climates, and is expected to decline further to USD 15-30 per MWh by 2030.
Furthermore, the global push for energy security (following the Russian invasion of Ukraine and subsequent energy price volatility) and climate change mitigation (net-zero emissions targets by 2050) is driving government policies including renewable portfolio standards, feed-in tariffs, net metering, tax credits (US Investment Tax Credit, extended at 30% through 2032-2035 under the Inflation Reduction Act), green certificates, renewable energy auctions, and corporate power purchase agreements (PPAs).
Corporate renewable energy procurement (through physical and virtual PPAs) is a powerful driver, with major corporations including Google, Microsoft, Amazon, Meta, Apple, Walmart, and others contracting gigawatts of solar capacity to meet 100% renewable energy and net-zero commitments. The electrification of transportation (electric vehicles) and heating (heat pumps) is increasing electricity demand, much of which will be met by solar PV. Technological developments include perovskite-silicon tandem cells (achieving over 33% laboratory efficiency, approaching the theoretical limit of 43% for dual-junction tandem cells), heterojunction (HJT) cells, tunnel oxide passivated contact (TOPCon) cells, interdigitated back contact (IBC) cells, bifacial modules (capturing light from both sides, increasing energy yield by 10-30%), and floating PV (FPV) on reservoirs, lakes, and ponds (reducing land use conflicts and increasing efficiency through water cooling).
Policy and regulatory influence is substantial, with governments setting ambitious solar deployment targets (US 2035 goal of 100% clean electricity, EU REPowerEU target of 600 GW solar by 2030, China's 2060 carbon neutrality driving massive annual installations exceeding 200 GW per year, India's 500 GW non-fossil capacity by 2030). The demand outlook is exceptionally strong, with the IEA's Net Zero Emissions scenario requiring annual solar PV additions to reach 630 GW by 2030 (up from approximately 350-400 GW in 2024-2025) and cumulative global installed capacity to exceed 4,500 GW by 2030 and 14,000 GW by 2050.
📍 Get Free Sample Report for Detailed Market Insights:
https://www.marketresearchfuture.com/sample_request/1061
Market Segmentation
The Photovoltaic Market is systematically segmented based on technology type, product type (module type), grid connectivity, deployment type (application), end-user, mounting structure, component, and region to provide a comprehensive view of this dynamic, rapidly evolving industry.
By Technology Type (Cell Technology): The market is divided into crystalline silicon (c-Si) and thin-film technologies. Crystalline silicon dominates with over 95% market share, split between monocrystalline silicon (mono-Si) and polycrystalline silicon (multi-Si). Monocrystalline silicon (mono-PERC, mono-TOPCon, mono-HJT, mono-IBC) has become the dominant technology (over 80% of c-Si market) due to higher efficiency (21-24% module efficiency) and better temperature coefficient and low-light performance compared to poly-Si (16-18% efficiency). Polycrystalline silicon (multi-Si) market share has declined significantly (now under 10% of c-Si market) as mono-Si costs have fallen and efficiency advantages have widened.
TOPCon (tunnel oxide passivated contact) is the fastest-growing segment within c-Si, transitioning from PERC (passivated emitter rear cell, the incumbent technology for 2015-2024) as the next-generation mainstream technology (module efficiencies 22-23%). Heterojunction (HJT) offers higher efficiency (22-24%) and lower temperature coefficient but higher manufacturing cost, targeted at premium and bifacial applications. Interdigitated back contact (IBC) offers highest efficiency (23-25%) but complex manufacturing, used in premium residential and commercial applications (SunPower, Maxeon, LG). Thin-film technologies include cadmium telluride (CdTe, First Solar's dominant technology, 17-19% module efficiency, low-cost, good temperature coefficient, rapidly degrading in lab? but field-stable), copper indium gallium selenide (CIGS, 15-18% module efficiency, flexible substrates for BIPV and specialty applications), and amorphous silicon (a-Si, low efficiency, largely obsolete). Perovskite and perovskite-silicon tandem cells are pre-commercial but rapidly advancing (laboratory efficiency >33% for tandems, pilot production lines operating), expected to enter commercial production by 2026-2028.
By Product Type (Module Type): The market is segmented by module construction: standard monofacial modules (front-side only), bifacial modules (back-side also captures reflected and diffuse light, gaining 10-30% additional energy yield, particularly with single-axis tracking and reflective ground cover (white gravel, sand, snow, water). Bifacial modules are the fastest-growing segment, now accounting for over 50% of new utility-scale deployments (and approaching 70% in favorable markets like US, India, Middle East, Australia).
Double-glass bifacial modules (glass-glass construction) offer better durability, lower degradation (30-year warranties), and are preferred for utility-scale. Transparent backsheet bifacial modules are lighter, lower cost, but less durable. Building-integrated photovoltaics (BIPV) integrates PV into building materials (roof tiles, facades, windows, curtain walls) and is a small but growing segment in premium residential and commercial architecture.
By Grid Connectivity: The market is segmented into on-grid (grid-tied) systems, which dominate utility-scale and most commercial/residential installations, and off-grid systems (standalone, not connected to electricity grid), used in remote and rural areas (developing regions, island communities, off-grid homes, telecom towers, water pumping, vaccine refrigeration). Hybrid systems (grid-tied with battery storage) are the fastest-growing segment, enabling self-consumption (store solar for evening use), backup power, peak shaving (reduce demand charges), grid services (frequency regulation, voltage support), and time-of-use arbitrage.
By Deployment Type (Application): The market is segmented into utility-scale (>5 MW, ground-mounted), commercial and industrial (50 kW - 5 MW, rooftop and ground-mounted), residential (3-15 kW, rooftop and ground-mounted), and floating PV (FPV, mounted on water bodies). Utility-scale dominates total installed capacity (approximately 60-70% of global annual additions), driven by lowest LCOE (economies of scale). Residential is the largest segment by number of installations (millions of rooftops globally) but smaller by capacity (15-20% of annual additions). C&I is 10-15% of additions. Floating PV is a small but rapidly growing segment (projected to reach 10+ GW annually by 2030), attractive in land-constrained regions (Southeast Asia, India, Japan, South Korea, Europe) and for water utilities (reducing evaporation).
By End-User: The market serves diverse sectors including electric utilities (IPP, utility-scale generators), commercial (office buildings, retail, hotels, hospitals, schools, data centers), industrial (factories, warehouses, manufacturing plants, refineries, mines), residential (homeowners), agriculture (agrivoltaics - co-locating PV with crops, livestock, or greenhouse operations), water utilities (floating PV on reservoirs, canal-top PV), and government/institutional (schools, hospitals, military bases, public buildings).
By Mounting Structure: The market is segmented into fixed tilt (ground-mounted or rooftop, fixed angle), single-axis tracking (horizontal or vertical, rotates to track sun across the sky, increasing energy yield by 20-30%, dominant for utility-scale in sunny markets), dual-axis tracking (tracks both azimuth and elevation, highest yield 30-40% increase, higher cost and maintenance, limited to high-value markets), and floating (FPV, anchored on water bodies). Single-axis tracking (particularly horizontal, north-south axis with east-west tracking) is the fastest-growing segment for new utility-scale deployments in markets with high direct normal irradiance (DNI) and low land cost (US Southwest, Middle East, India, Australia, Spain, Chile).
By Component: The market is segmented by system components: modules (PV panels - the largest revenue segment), inverters (string inverters for residential/C&I, central inverters for utility-scale, microinverters for module-level optimization, power optimizers), mounting structures (fixed, tracking, floating), balance of system (BOS) - cables, connectors, combiner boxes, junction boxes, monitoring systems, SCADA, transformers, switchgear, and energy storage systems (battery storage, increasingly co-located with new solar projects).
By Region: The market is segmented into North America, Europe, Asia-Pacific (APAC), Latin America, and the Middle East & Africa. Asia-Pacific is the largest regional market (China dominates, followed by India, Japan, Australia, Vietnam, South Korea, Thailand, Malaysia, Philippines). Europe is the second-largest (Germany, Spain, Netherlands, Poland, Italy, France, UK, Greece, Portugal, Turkey). North America (US, Canada) is third but growing rapidly (US IRA-driven boom). Latin America (Brazil, Chile, Mexico, Argentina, Colombia) and Middle East & Africa (UAE, Saudi Arabia, Oman, Qatar, Egypt, South Africa, Namibia, Morocco) are rapidly growing markets.
🛒 You can buy this market report at:
https://www.marketresearchfuture.com/checkout?currency=one_user-USD&report_id=1061
Regional Analysis
Asia-Pacific: The Asia-Pacific region is the world's largest PV market, accounting for over 60-70% of global annual installations, led by China, the undisputed global solar superpower. China installed over 200 GW of new solar capacity in 2023-2024 (more than the entire cumulative installed capacity of the US), with cumulative capacity exceeding 700 GW. China's massive deployment is driven by government targets (carbon neutrality by 2060, renewable portfolio standards, provincial quotas, grid parity, and massive manufacturing scale).
China dominates PV manufacturing across the entire value chain (polysilicon, wafer, cell, module, inverters, trackers, steel, glass, backsheet, encapsulant, junction boxes, connectors) with over 80-90% global market share in most segments, producing solar modules at costs 30-50% lower than Western manufacturers (though subject to tariffs and trade restrictions in US and Europe). India is the second-largest Asian market and the fastest-growing major PV market globally (10-15+ GW annually, targeting 500 GW non-fossil capacity by 2030, including 280 GW solar).
India's domestic manufacturing capacity is expanding under the Production Linked Incentive (PLI) scheme, though China remains the dominant supplier. Japan is a mature solar market with high cumulative installed capacity (80+ GW) but declining annual additions (4-5 GW) due to grid constraints, land availability, and feed-in tariff reductions. Australia has the world's highest per-capita rooftop solar penetration (over 30% of detached houses), driven by high electricity prices, abundant sunshine, and attractive feed-in tariffs and subsidies. South Korea, Vietnam, Thailand, Malaysia, Philippines, and Taiwan are significant markets with growing utility-scale and rooftop segments.
Europe: The European PV market has experienced a renaissance following the REPowerEU plan (2022), which targeted 600 GW of solar capacity by 2030 (up from approximately 250 GW in 2024) and accelerated deployment in response to the energy crisis (reducing dependence on Russian natural gas). Germany is the European leader (80+ GW cumulative, 10-15 GW annual additions, targeting 200 GW by 2030), with strong distributed generation (residential and C&I rooftop) and utility-scale auctions.
Spain is the second-largest European market (25+ GW cumulative, 5-8 GW annual additions), dominated by utility-scale ground-mounted solar with single-axis tracking, benefiting from exceptional solar resources. The Netherlands has the highest per-capita solar capacity in Europe (driven by rooftop, net metering), but net metering phase-out is slowing growth. Poland has grown rapidly (10+ GW cumulative, 2-3 GW annual) driven by prosumer rooftop subsidies. Italy (25+ GW cumulative), France (15-20 GW cumulative), UK (15+ GW cumulative), Greece, Portugal, Turkey, and Belgium are significant markets. The Nordics (Sweden, Denmark, Finland, Norway) have growing solar markets despite moderate irradiance, driven by falling costs and corporate PPAs. Eastern Europe (Hungary, Czech Republic, Romania, Bulgaria, Ukraine - pre-war significant growth) is emerging.
North America: The North American PV market is dominated by the United States, the world's second-largest solar market after China (approximately 150-200 GW cumulative, 20-30+ GW annual additions). The Inflation Reduction Act (IRA, 2022) transformed the US market by providing a 30% Investment Tax Credit (ITC) for solar projects through 2032-2035 (step-down thereafter), with bonus credits for domestic content (10% adder), energy communities (10% adder), low-income communities (10-20% adder), and for projects co-located with storage.
The ITC, combined with falling module prices (though subject to tariff uncertainty on imports from China and Southeast Asia), has made utility-scale solar the cheapest new power generation source across most of the US. The US utility-scale market is concentrated in the Southwest (Texas, California, Arizona, Nevada, New Mexico, Colorado, Utah), Southeast (Florida, Georgia, North Carolina, Virginia, South Carolina), and Midwest (Ohio, Indiana, Illinois). Texas has surpassed California as the largest utility-scale solar market due to available land, strong solar resource, and deregulated ERCOT market with high price volatility, making merchant solar (selling into wholesale market without long-term PPA) attractive.
California remains the largest rooftop solar market (NEM 3.0 reduced compensation for exported solar, driving storage attachment). New York, Florida (net metering changes), Massachusetts, New Jersey, Illinois (renewable portfolio standards, community solar) are significant state markets. Community solar (shared solar for renters, low-income households, businesses without suitable rooftops) is a growing segment in states with enabling legislation. Canada has moderate solar deployment (4-5 GW cumulative, 1-2 GW annual) concentrated in Ontario, Alberta, and Saskatchewan, driven by federal carbon pricing and provincial targets. Mexico's solar market has slowed due to policy uncertainty (government favoring state utility CFE, changes to grid access and dispatch) but has significant underlying resource potential.
Latin America: Latin America is a rapidly growing solar market, led by Brazil, Chile, and Mexico (though Mexico slowed), with emerging markets in Argentina, Colombia, Peru, and the Dominican Republic. Brazil is the regional leader (30+ GW cumulative, 10+ GW annual additions), driven by distributed generation (net metering for residential and C&I rooftop, which exploded under prior net metering rules, now transitioning to reduced compensation but still attractive), large utility-scale auctions (at extremely low prices, USD 20-25 per MWh), and high retail electricity prices (making solar attractive for self-consumption).
Chile has exceptional solar resources (Atacama Desert, highest DNI globally) and a large utility-scale market (6-8 GW cumulative) selling into the SING and SIC grids, plus a growing distributed generation segment. Chile has also developed a strong market for co-located solar-plus-storage (curtailment of solar in midday has driven storage deployment). Colombia held its first renewable energy auctions, awarding solar projects. Argentina has significant solar potential (Northwest region) and awarded projects under the RenovAr program, though macroeconomic instability and grid constraints limit growth. Mexico (as noted above) has slowed significantly but has installed over 10 GW of utility-scale and distributed solar, with significant resource potential if policy uncertainty resolves.
Middle East & Africa: The Middle East is an emerging solar powerhouse, driven by exceptional solar resources (DNI among the highest globally), low land costs, and government-driven energy transition strategies (diversification away from oil/gas for domestic consumption, preserving hydrocarbon exports). The United Arab Emirates (UAE) is the regional leader with the Mohammed bin Rashid Al Maktoum Solar Park (5 GW planned), record-low solar PPA prices (USD 1.5-2.5 cents per kWh, world record). Saudi Arabia's Vision 2030 includes 40 GW of solar by 2030 (and 58 GW total renewable energy), with massive utility-scale projects (e.g., Sudair 1.5 GW) awarded at extremely low prices (USD 1.04-1.6 cents per kWh).
Oman, Qatar, Kuwait, Bahrain, Jordan, and Israel have active solar markets. Egypt has significant solar deployment (Benban Solar Park, 1.5 GW) and is expanding. Africa's solar market is nascent but growing rapidly, led by South Africa (the largest African market, driven by severe load shedding / rolling blackouts, massive behind-the-meter C&I solar and battery deployment to ensure power reliability, and utility-scale auctions under REIPPPP). Morocco, Kenya, Nigeria, Ghana, Namibia, and Rwanda have growing utility-scale and distributed solar markets. Off-grid solar (home systems, solar lanterns, mini-grids) serves millions of households without grid access in Sub-Saharan Africa.
Competitive Landscape / Key Players
The Photovoltaic Market features a highly concentrated, vertically integrated manufacturing landscape dominated by Chinese companies, with a fragmented downstream (project development, EPC, O&M) landscape with regional and local players.
Key Manufacturing Companies (Modules, Cells, Wafers, Polysilicon):
Longi Green Energy Technology Co., Ltd.: The world's largest solar manufacturer (wafer, cell, module) by shipments and revenue. Longi is the global leader in monocrystalline silicon technology (PERC, TOPCon, HPBC) and has driven the industry transition from poly-Si to mono-Si. Longi's vertically integrated capacity (wafers, cells, modules) exceeds 100 GW annually.
Tongwei Co., Ltd.: The world's largest polysilicon and solar cell manufacturer (separately), with massive integrated capacity. Tongwei has rapidly expanded into modules and is one of the lowest-cost manufacturers globally.
JA Solar Technology Co., Ltd.: A top-5 global module manufacturer (vertically integrated wafers, cells, modules) with deep experience in PV technology (PERC, TOPCon, n-type).
Trina Solar Co., Ltd.: A top-5 global module manufacturer and a pioneer in PERC, bifacial, and n-type (TOPCon, HJT) technology. Trina also has a large tracker business (TrinaTracker).
JinkoSolar Holding Co., Ltd.: A top-5 global module manufacturer with strong global distribution and a diversified manufacturing footprint (including Vietnam, Malaysia, US).
Canadian Solar Inc.: A top-5 global module manufacturer (Chinese company, headquartered in Canada, publicly traded in US) with a large global project development portfolio (CSI Solar / Recurrent Energy).
First Solar, Inc.: The world's largest thin-film (CdTe) module manufacturer (US-based, non-Chinese). First Solar's modules are US-manufactured (Ohio, with expansions in Alabama, Louisiana, and potentially other states), exempt from most tariffs on Chinese modules, and preferred by US utility-scale developers seeking domestic content for ITC bonus credits and supply chain diversification. First Solar's technology offers excellent temperature coefficient, low degradation, and superior performance in high-heat, high-humidity environments.
Risen Energy Co., Ltd., Chint (Astronergy), GCL System Integration, DAS Solar, Suntech, and others.
Key Inverter Manufacturers:
Huawei Technologies Co., Ltd.: The world's largest solar inverter manufacturer (string inverters for all segments), known for high-efficiency, smart inverter technology, and strong digital integration (monitoring, grid support).
Sungrow Power Supply Co., Ltd.: The second-largest inverter manufacturer (both string and central inverters for utility-scale), with strong global market share and a growing energy storage business.
**Ginlong Technologies (Solis), Growatt, GoodWe, Fimer (ABB Inverters, now under new ownership), SMA Solar Technology (German, leading central and string inverter manufacturer, particularly in Europe and US), Enphase Energy (microinverters for residential, leading US market, also energy storage), SolarEdge Technologies (power optimizers and inverters for residential/C&I, leading DC-optimized architecture), TMEIC (utility-scale central inverters), Schneider Electric.
Key Downstream Players (Project Development, EPC, O&M, IPP):
NextEra Energy Resources: The world's largest utility-scale renewable energy developer (US-based, subsidiary of NextEra Energy), with massive solar and solar+storage portfolio.
Lightsource BP: A global solar project developer (50/50 joint venture between BP and Lightsource).
**Brookfield Renewable, AES Corporation, Enel Green Power, Engie, EDF Renewables, RWE, Iberdrola, Orsted (primarily offshore wind, but expanding solar), TotalEnergies, Shell, Ørsted (acquiring solar development platforms), Fotowatio Renewable Ventures (FRV), Scatec, ACWA Power (Middle East developer), Masdar (UAE developer), Adani Green Energy (India), ReNew Power (India), Azure Power (India), SB Energy (SoftBank, India/US), Enel Green Power (global).
Residential and Commercial Installers (many regional/local): Sunnova, Sunrun (leading US residential installer), Tesla (residential solar + Powerwall), Vivint Solar (acquired by Sunrun), ADT Solar, Trinity Solar, Freedom Forever, SolarNeg (Germany), Enpal (Germany), Zolar (Germany), many others.
Strategic Developments: The US Inflation Reduction Act (IRA) has triggered a massive domestic manufacturing build-out in the US, with over 100 GW of announced module assembly capacity, 50+ GW of cell manufacturing, 30+ GW of wafer, 20+ GW of polysilicon, and inverter, tracker, mounting, glass, backsheet, encapsulant facilities under construction or announced. The goal is to reduce US reliance on Chinese and Southeast Asian supply (subject to tariffs, forced labor concerns, supply chain risk).
However, China retains massive cost and scale advantages, and US domestic manufacturing will likely focus on serving the US market (and possibly Europe and other high-value markets) with premium products (bifacial, n-type, large-format modules). Technology transition: the industry is transitioning from PERC (passivated emitter rear cell) to TOPCon (tunnel oxide passivated contact) as the mainstream technology (2024-2027), with HJT (heterojunction) occupying a premium niche and perovskite-silicon tandem cells entering commercial production in 2027-2030.
Bifacial modules, large-format modules (M10, G12, G12R wafers, 182 mm, 210 mm, 2384 mm length, 1300 mm width), and higher wattage (600 Wp, 700+ Wp) are standardizing. Single-axis tracking is becoming standard for new utility-scale deployments in sunny markets. Co-located solar+storage (battery energy storage systems, BESS) is becoming standard for new utility-scale projects, as storage captures evening value, provides grid services, and qualifies for ITC (30% standalone storage under IRA).
Latest Industry News & Developments
Perovskite-Silicon Tandem Module Pilot Production (April 2025): A leading Chinese PV manufacturer (name not disclosed in early announcements, later confirmed as Longi in collaboration with a European research institute) began pilot production of perovskite-silicon tandem modules at a 100 MW pilot line, achieving confirmed module efficiency of 26.5% (aperture area, not just cell). The company announced plans for GW-scale commercial production by 2027, potentially accelerating the industry transition beyond PERC and TOPCon to multi-junction tandems (targeting >30% module efficiency).
US Domestic Module Manufacturing Milestone (March 2025): Cumulative US solar module manufacturing capacity surpassed 50 GW annually, driven by IRA manufacturing tax credits (Section 45X). First Solar, Qcells (Hanwha), LONGi, Trina, JinkoSolar, Canadian Solar, and several new entrants (including Enel, NorSun, Heliene, Meyer Burger, Convalt Energy) have announced or begun construction of US module assembly, cell, wafer, ingot, and polysilicon facilities. However, upstream capacity (cells, wafers, ingots, polysilicon) lags module assembly, with cell manufacturing under 20 GW, wafer under 10 GW, polysilicon under 5 GW, creating continued dependence on imported cells, wafers, and polysilicon (primarily from Southeast Asia, with some China direct).
India Overtakes Japan in Cumulative Solar Capacity (February 2025): India's cumulative installed solar capacity surpassed 85 GW, overtaking Japan (approximately 83 GW) to become the world's third-largest solar market (after China and US). India added over 15 GW in the calendar year 2024, with utility-scale accounting for 70% and rooftop distributed for 30%, driven by strong policy support (national solar mission, state renewable portfolio standards, open access rules, net metering, PLI for domestic manufacturing).
Market Challenges & Opportunities
Key Restraints: The primary challenge facing the Photovoltaic Market is grid integration and intermittency. Solar PV is a variable renewable energy source (generating only when the sun shines, peaking at midday, zero at night), requiring grid flexibility (battery storage, pumped hydro, demand response, flexible gas generation, overbuilding with curtailment) to achieve high penetration levels (>30-40% annual share).
As solar penetration increases, curtailment (spilling excess solar generation) becomes necessary, reducing project revenues and potentially harming project economics. Land use conflicts and permitting challenges: utility-scale solar requires significant land area (approximately 3-6 acres per MW, or 1,500-3,000 acres for a 500 MW plant), leading to conflicts with agriculture, conservation, desert ecosystems, and local opposition (NIMBYism). Transmission infrastructure is often inadequate to connect large solar plants to load centers, with interconnection queues exceeding 1,000 GW of pending projects (US, Europe, India), and wait times of 3-7 years. Supply chain concentration risk: over 80% of global PV manufacturing capacity (polysilicon, wafers, cells, modules) is located in China, creating vulnerability to trade restrictions (tariffs, anti-dumping duties, forced labor import bans - Uyghur Forced Labor Prevention Act), geopolitical tensions, and supply disruptions (pandemic, energy shortages).
Trade policy uncertainty: the US has imposed tariffs on Chinese modules (Section 201, Section 301, AD/CVD), circumvention tariffs on Southeast Asian cells/modules, and the UFLPA, causing project delays and cost uncertainty. Europe is considering similar measures. Falling module prices (while good for deployment) pressure manufacturer profitability, leading to consolidation and bankruptcies (many Western manufacturers have exited or reduced production). Labor shortages for installation (electricians, roofers, heavy equipment operators) in rapidly growing markets (US, Europe, India) can increase installation costs and delay projects.
Emerging Opportunities: The most significant opportunity lies in the development of multi-junction tandem solar cells (perovskite-silicon, perovskite-perovskite, III-V on silicon) achieving module efficiencies >28-30% (compared to 22-24% for PERC/TOPCon), substantially reducing balance-of-system (BOS) costs (land, mounting, cabling, labor, inverters) per watt and accelerating grid parity. Agrivoltaics (co-locating solar PV with crop production, livestock grazing, or greenhouse agriculture) addresses land use conflicts, provides dual land use income for farmers, and can improve crop yields (shade reduces water evaporation, heat stress) and solar efficiency (evapotranspiration cooling).
Floating PV (FPV) on reservoirs, hydropower dams, quarry lakes, water treatment ponds, and coastal waters addresses land constraints in dense, land-constrained regions (Southeast Asia, India, Japan, South Korea, Europe). FPV can also reduce water evaporation (saving water), reduce algae growth, and improve module efficiency (water cooling). Solar-plus-storage (co-located battery storage) enables shifting solar generation to evening peak hours (replacing gas peakers), providing grid services (frequency regulation, voltage support, spinning reserves), capturing higher electricity prices (time-of-use arbitrage), and firming solar output (reducing curtailment).
The IRA's standalone storage ITC (30% through 2032) has accelerated storage deployment. Building-integrated photovoltaics (BIPV) integrates PV into building materials (roof tiles, facades, windows, curtain walls, skylights) for premium architectural applications, electric vehicle charging, net-zero buildings, and green building certifications (LEED, BREEAM, Passive House). Solar for electric vehicle (EV) charging (solar canopies over parking lots, workplace charging, destination charging) is a growing segment, as EV load increases and drivers seek low-carbon charging. Perovskite PV (standalone perovskite modules) may enable low-cost, flexible, lightweight, semi-transparent applications (BIPV, portable, emergency, military, space, building-integrated, agrivoltaics greenhouses) once stability and scalability challenges are solved (expected 2028-2032).
Future Potential: The long-term future of the Photovoltaic Market is defined by the transition to a global energy system dominated by solar PV as the primary electricity source, complemented by wind, hydropower, nuclear (existing), battery storage, long-duration energy storage, and transmission. The IEA's Net Zero Emissions by 2050 scenario requires annual solar PV additions to exceed 630 GW by 2030 (from approximately 350-400 GW in 2024-2025) and cumulative global capacity to reach 4,500-5,000 GW by 2030, 14,000-18,000 GW by 2050. Solar PV LCOE is projected to decline to USD 15-25 per MWh (utility-scale in sunny regions) by 2030 and USD 10-15 per MWh by 2040-2050.
Multi-junction tandem cells (perovskite-silicon, III-V, perovskite-perovskite) will raise module efficiencies to 30-35% (cell) and 28-32% (module) by 2035. Bifacial modules, single-axis tracking, and solar+storage will become standard for all new utility-scale projects. Distributed generation (residential, C&I) will continue to grow, driven by electric vehicle charging, heat pumps, net-zero buildings, and falling storage costs. Agrivoltaics and floating PV will address land constraints and provide co-benefits.
The PV industry will become increasingly circular, with module recycling and recovery of silicon, silver, copper, aluminum, glass, and encapsulation materials becoming economically viable and regulated. Manufacturing will diversify beyond China (US, India, Europe, Southeast Asia) driven by policy incentives (IRA, PLI, Net-Zero Industry Act), trade restrictions, and corporate supply chain diversification. However, China will likely retain the largest global market share (50-60%) for manufacturing due to its scale, supply chain integration, energy costs, and policy continuity.
To explore more market insights, visit us at:
https://www.marketresearchfuture.com/reports/photovoltaic-market-1061
Final Market Summary
The Photovoltaic Market is positioned for strong, sustained growth over the forecast period from 2025 to 2035, driven by unsubsidized cost competitiveness (lowest LCOE among all new electricity generation sources), global decarbonization mandates (net-zero emissions by 2050), energy security concerns (reducing dependence on imported fossil fuels), corporate renewable procurement (PPAs), and supportive policies (US IRA, EU REPowerEU, China's carbon neutrality, India's solar targets).
Driven by a compound annual growth rate (CAGR) of 9.0%, the market is projected to expand from USD 112.87 billion in 2025 to USD 267.2 billion by 2035, reflecting both increasing installation volumes and evolving value capture (energy storage integration, smart inverters, digital services, BIPV, O&M, asset management). The market is undergoing a technology transition from PERC to TOPCon (mainstream 2024-2027), with HJT occupying a premium niche and perovskite-silicon tandem cells entering commercial production (2027-2030). Manufacturing concentration in China poses supply chain risks, prompting domestic manufacturing build-out in the US (IRA) and expansion in India (PLI) and Europe (Net-Zero Industry Act).
Grid integration challenges (intermittency, curtailment) are being addressed by co-located battery storage (solar+storage becoming standard), long-duration storage, and transmission expansion. The long-term potential for solar PV is extraordinary: solar is on track to become the largest global electricity source by 2040-2050, supplying 30-50% of global electricity generation, representing a multi-trillion dollar cumulative investment opportunity across manufacturing, project development, storage, grid integration, and recycling.
More Related Reports from MRFR Library:
Future Of Batteries Market https://www.marketresearchfuture.com/reports/future-of-batteries-market-overview-24970
Offshore Wind Turbine Market https://www.marketresearchfuture.com/reports/offshore-wind-turbine-market-24972
Oil & Gas Analytic Market https://www.marketresearchfuture.com/reports/oil-gas-analytic-market-25019
Oil & Gas Security Market https://www.marketresearchfuture.com/reports/oil-gas-security-market-25020
One Way Degassing Valve Market https://www.marketresearchfuture.com/reports/one-way-degassing-valve-market-25029
Power Plant Boiler Market https://www.marketresearchfuture.com/reports/power-plant-boiler-market-25088
Pressurized Water Reactor Market https://www.marketresearchfuture.com/reports/pressurized-water-reactor-market-25094
Flare Gas Recovery System Market https://www.marketresearchfuture.com/reports/flare-gas-recovery-system-market-25155
Rooftop Solar Photovoltaic Market https://www.marketresearchfuture.com/reports/rooftop-solar-photovoltaic-market-25181
Air Electrode Battery Market https://www.marketresearchfuture.com/reports/air-electrode-battery-market-25197
About Market Research Future:
Market Research Future® (Part of WantStats Research and Media Pvt. Ltd.) has specialized research analysts in the areas of Aerospace & Defense, Automotive, C&M, Energy & Power, F&B, Healthcare & Pharmaceutical, ICT, Industrial Equipment, Packaging Construction & Mining and Semiconductor. Market Research Future (MRFR) is a global market research company that takes pride in its services, offering a complete and accurate analysis with regard to diverse markets and consumers worldwide. MRFR's approach combines the proprietary information with various data sources to give an extensive understanding to the client about the latest key developments, expected events and about what action to take based on these aspects.
Contact
Market Research Future (Part of Wantstats Research and Media Private Limited)
99 Hudson Street, 5Th Floor
New York, NY 10013
United States of America
+1 628 258 0071 (US)
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Photovoltaic Market to Hit USD 267.2 Billion by 2035 at 9.0% CAGR here
News-ID: 4546447 • Views: …
More Releases from MRFR
Power Tools Market to Reach USD 82294.64 Million by 2035 at 6.26% CAGR
As per MRFR analysis, the Power Tools Market Size was estimated at USD 42190.3 Million in 2024. The Power Tools industry is projected to grow from USD 44832.27 Million in 2025 to USD 82294.64 Million by 2035, exhibiting a compound annual growth rate (CAGR) of 6.26% during the forecast period 2025 - 2035.
Market Overview
The Power Tools Market encompasses a wide range of electrically, pneumatically, or fuel-driven devices designed to perform…
Forestry Equipment Market to Reach USD 67.33 Billion by 2035 at 3.31% CAGR
As per Market Research Future analysis, the Forestry Equipment Market Size was estimated at 47.05 USD Billion in 2024. The Forestry Equipment industry is projected to grow from 48.61 USD Billion in 2025 to 67.33 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 3.31% during the forecast period 2025 - 2035.
Market Overview
The Forestry Equipment Market encompasses a comprehensive range of specialized machinery, vehicles, and tools designed…
Residential Cold Climate Heat Pump Market to Reach USD 37.07 Billion by 2035 at …
As per Market Research Future analysis, the Residential Cold Climate Heat Pump Market Size was estimated at 14.26 USD Billion in 2024. The Residential Cold Climate Heat Pump industry is projected to grow from 15.55 USD Billion in 2025 to 37.07 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 9.07% during the forecast period 2025 - 2035.
Market Overview
The Residential Cold Climate Heat Pump Market encompasses advanced…
Hydraulic Elevators Market to Reach USD 19.5 Billion by 2035 at 3.0% CAGR
As per Market Research Future analysis, the Hydraulic Elevators Market Size was estimated at 14.01 USD Billion in 2024. The Hydraulic Elevators industry is projected to grow from 14.44 USD Billion in 2025 to 19.5 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 3.0% during the forecast period 2025 - 2035.
Market Overview
The Hydraulic Elevators Market encompasses vertical transportation systems that utilize hydraulic fluid, a pump system,…
More Releases for Solar
Biohybrid Solar Cell Market Professional Survey Report 2022 - Jinko Solar, JA SO …
The Biohybrid Solar Cell Market Report 2022 provides a comprehensive analysis of observable trends and projections. This research shows how to attract a large number of customers. Our certified crew of economists, researchers, and advisers has made further attempts in projecting the global industry by utilising accredited global Biohybrid Solar Cell market information tools as well as various instruments and ways to successfully review and get information. The research argues…
Home Solar Power System Market Size, Share, Trends, Growth - Tesla, Panasonic So …
The Global Home Solar Power System Market study includes new innovations, market dynamics, strategic profiling in terms of the future market strategies and shares for the subsectors of the industry. This research consists of details related to the size of the industries, the major players, markets, sales volume and value. This study offers a detail data on the historical data pointers as well as forecasts by region/country for the sectors…
Solar PV Module Market Outlook To 2024 - Trina Solar, Canadian Solar Inc., JA So …
Solar PV module market from utility sector has witnessed a substantial growth globally in recent years. In the first quarter of the year, Vietnam's Ministry of Industry and Trade have talked about their FiT scheme related to utility-based solar power projects. Ongoing electrification programs and incentives benefit pertaining to grid connected power generation is surging the demand for on-grid solar PV modules. On-grid connection represented 55% of the overall solar…
Solar Simulator Market Distribution Channel 2019: Spire Solar, Solar Energy Inte …
Solar Simulator Market report aims to examine the developments of market including its market improvements, developments, positions and others.
This report on the Solar Simulator market offers explanatory knowledge on the market parts like dominating players, drivers and restraints, production, revenue, consumption, import and export, and the most effective development within the organization size, deployment type, inside, segmentation comprised throughout this analysis, also major the players have used various strategies such…
Solar PV Module Market By Key Vendors: Trina Solar, Canadian Solar Inc., JA Sola …
UK solar PV module market is set to expand owing to government initiatives towards sustainable energy integration. The export tariff introduced by the UK government facilitates USD 0.06 per unit for the surplus electricity injected back to the grid by the generator. Favorable government reforms with ambitious plan towards carbon footprint reduction will further boost the business outlook.
Request for a sample of this research report @
https://www.gminsights.com/request-sample/detail/1563
Solar PV Module Market size…
Solar Photovoltaic PV Market Outlook by Top Manufacturers (2018-2025) - Hanwha, …
ReportsWeb.com has announced the addition of the “Global Solar Photovoltaic PV Market Professional Survey Report 2018” The report classifies the global Solar Photovoltaic PV Market in a precise manner to offer detailed insights about the aspects responsible for augmenting as well as restraining market growth.
This report studies Solar Photovoltaic PV in Global market, especially in North America, China, Europe, Southeast Asia, Japan and India, with production, revenue, consumption, import and…

