


Press release
Gas Compressor Market to Reach USD 18.29 Billion by 2035 at 3.53% CAGR
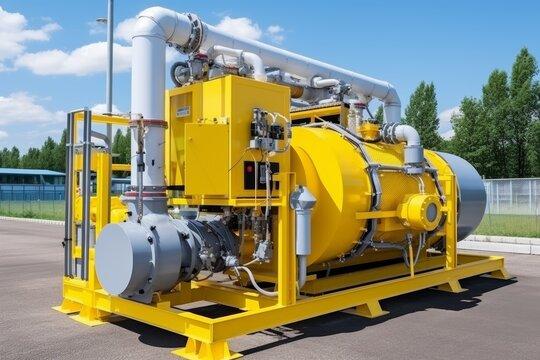
Gas Compressor Market
Market Overview
The Gas Compressor Market encompasses the design, manufacturing, installation, maintenance, and servicing of mechanical devices that increase the pressure of gases by reducing their volume. Gas compressors are critical infrastructure components across the entire oil and gas value chain (upstream production, midstream transportation and storage, downstream refining and petrochemicals), as well as in industrial manufacturing, power generation, chemical processing, refrigeration and HVAC, hydrogen and renewable natural gas production, and emerging energy transition applications.
Compressors perform essential functions: moving natural gas through transmission pipelines over long distances (overcoming frictional pressure losses), boosting pressure from declining oil and gas wells, reinjecting gas for enhanced oil recovery (EOR) or carbon capture and storage (CCS), compressing natural gas for liquefaction (LNG plants), compressing refrigerant gases in cooling systems, supplying compressed air for industrial tools and processes (instrument air, plant air), and compressing hydrogen for transport, storage, and refueling stations.
The market covers a wide range of compressor types including centrifugal compressors (high-flow, lower pressure rise, suitable for continuous operation), reciprocating compressors (high pressure rise, lower flow, suitable for intermittent or high-ratio compression), screw compressors (rotary positive displacement, oil-injected or oil-free, medium flow and pressure), axial compressors (very high flow, low pressure rise per stage, used in gas turbines and large LNG trains), and diaphragm compressors (hermetic, contamination-free, ideal for high-purity gases including hydrogen, helium, and specialty gases). The market is mature and stable, with growth tied to global energy demand, natural gas consumption (including LNG exports and imports), industrial production, and emerging hydrogen and carbon capture applications.
The primary growth driver for the Gas Compressor Market is the ongoing global demand for natural gas as a transition fuel and a baseload power source. Natural gas consumption continues to grow in Asia (China, India, Southeast Asia), the Middle East, and Africa, driving investment in gas production, gathering systems, transmission pipelines, and LNG liquefaction and regasification terminals.
The expansion of LNG export capacity, particularly from the United States (Gulf Coast, Appalachia, West Coast), Qatar, Australia, Russia (Arctic LNG 2, though challenged), Canada (LNG Canada), and Mozambique, requires massive compressor installations for liquefaction (main cryogenic compressors, mixed refrigerant compressors), boil-off gas (BOG) handling, and send-out (regasification).
Furthermore, the growth of hydrogen infrastructure for the energy transition-including hydrogen pipelines, hydrogen refueling stations, hydrogen storage caverns, and hydrogen blending into natural gas networks-is creating new demand for specialized hydrogen compressors (oil-free, leak-tight, high-pressure, capable of handling hydrogen's unique properties including low molecular weight, high diffusivity, and embrittlement potential). Carbon capture, utilization, and storage (CCUS) projects require compressors to raise CO2 pressure for pipeline transport and subsurface injection (geological storage or EOR). Additionally, the replacement of aging compressor fleets in mature markets (North America, Europe, Russia, Middle East) with more efficient, lower-emission, digitally connected equipment provides steady aftermarket and upgrade demand.
Key industry trends include the electrification of gas compressors (replacing gas turbine-driven compressors with electric motor-driven compressors, reducing onsite emissions and fuel costs where grid electricity is low-carbon or low-cost), particularly on new pipelines and LNG facilities. The adoption of variable frequency drives (VFDs) for centrifugal compressors enables efficient turndown and partial load operation, reducing energy consumption.
Digitalization, including predictive maintenance (using IoT sensors, vibration monitoring, AI-based anomaly detection), remote monitoring and diagnostics, digital twins (virtual replicas for performance optimization and failure simulation), and automated control, is improving compressor reliability, uptime, and maintenance scheduling. Technological developments include oil-free and dry-gas seal technologies for contamination-sensitive applications (hydrogen, food-grade gases, electronics gases), high-pressure compressor designs for hydrogen refueling stations (up to 700 bar, 900 bar, 1000 bar for heavy-duty trucks), and magnetic bearing compressors (active magnetic bearings eliminating oil systems, reducing maintenance, enabling high-speed operation).
Policy and regulatory influence includes methane emissions regulations (US EPA's Methane Rule, EU's Methane Regulation), which mandate leak detection and repair (LDAR) and, in some jurisdictions, require replacement of high-bleed pneumatic devices and compressors with low-bleed or zero-bleed technologies. Energy efficiency standards and carbon pricing mechanisms (EU ETS, California Cap-and-Trade) incentivize higher-efficiency compressor retrofits. The demand outlook is stable to moderately positive, with growth driven by LNG expansion, hydrogen infrastructure, industrial production in emerging economies, and aftermarket replacement cycles.
📍 Get Free Sample Report for Detailed Market Insights:
https://www.marketresearchfuture.com/sample_request/41441
Market Segmentation
The Gas Compressor Market is systematically segmented based on compressor type, technology (positive displacement vs dynamic), compression medium, application, end-user industry, power source, pressure rating, lubrication method, and region to provide a comprehensive view of this mature, technically diverse industry.
By Compressor Type (Technology): The market is divided into positive displacement compressors (reciprocating, rotary screw, rotary vane, diaphragm, liquid ring) and dynamic compressors (centrifugal, axial, mixed flow). Centrifugal compressors dominate the market by revenue and capacity, particularly for high-flow, continuous-duty applications including natural gas transmission pipelines (3-50+ MW), LNG liquefaction (main refrigerant compressors 50-200+ MW), gas gathering, gas lift, reinjection, and large industrial processes.
Reciprocating compressors are the second-largest segment, used for high-pressure, lower-flow applications including wellhead gas lift, gas gathering, CNG refueling stations, hydrogen compression (high pressure ratios), chemical and petrochemical processes, and pressure testing. Rotary screw compressors (oil-injected and oil-free) are widely used for medium-pressure, medium-flow industrial compressed air (plants, instrument air, nitrogen generation) and natural gas boosters (pipelines, distribution networks, biogas upgrading). Diaphragm compressors (hermetic, oil-free, leak-tight) are the preferred technology for high-purity gas compression including hydrogen, helium, noble gases, specialty gases for electronics, and hydrogen refueling stations (for high final pressure, 700-1000 bar). Axial compressors are highly specialized for very high-flow, relatively low-pressure ratio applications, primarily in large gas turbines (power generation, LNG and petrochemical plant drivers) and aircraft engines.
By Compression Medium (Gas Type): The market is segmented by gas being compressed: natural gas, hydrogen, carbon dioxide (CO2), nitrogen, oxygen, air (compressed air for industrial use), refrigerant gases (HFCs, HFOs, ammonia, CO2), process and chemical gases (ethylene, propylene, methane, ethane, hydrogen chloride, chlorine, specialty gases), helium, argon, and others. Natural gas is the largest segment, accounting for the majority of compressor value and volume (upstream production, midstream pipelines, storage, LNG, CNG, distribution).
Hydrogen is the fastest-growing segment, driven by hydrogen refueling stations (700-1000 bar diaphragm and reciprocating compressors), hydrogen pipelines (centrifugal and reciprocating), hydrogen storage caverns and vessels, and blending applications. CO2 compression is growing rapidly for carbon capture, utilization, and storage (CCUS) pipelines and injection wells. Air compressors (plant air, instrument air) constitute a large, stable segment supporting industrial facilities globally.
By Application: The market serves distinct applications including upstream (oil and gas production: gas lift, wellhead compression, gas gathering, associated gas compression, vapor recovery, reinjection for EOR), midstream (transmission pipelines, gas storage (depleted reservoirs, salt caverns, LNG terminals (liquefaction and regasification), CNG transport), downstream (refining (hydrocracking, hydrotreating, catalytic cracking, alkylation), petrochemical and chemical plants (process compression), fertilizer production (ammonia, urea)), industrial manufacturing (plant air, instrument air, nitrogen generation), power generation (gas turbine fuel gas compression, CO2 compression for CCS), hydrogen (production, pipeline, refueling station), and refrigeration/HVAC (refrigerant compression for commercial and industrial cooling, cold storage, LNG boil-off gas recondensation). Midstream natural gas pipelines and LNG applications represent the largest revenue segment due to the large size and high value of pipeline and LNG compressors. Hydrogen and CCUS are the fastest-growing application segments.
By End-User Industry: The market serves diverse sectors including oil and gas (upstream, midstream, downstream), chemical and petrochemical, power generation and utilities, manufacturing (automotive, aerospace, electronics, general industrial), mining and metals, food and beverage (refrigeration, compressed air for packaging), pharmaceuticals (compressed air, process gases), and hydrogen and clean energy. Oil and gas remains the largest end-user segment, though its share is gradually declining relative to industrial manufacturing and emerging hydrogen/CCUS.
By Power Source: The market is segmented by compressor driver type: gas turbine (including natural gas, dual fuel), electric motor (including VFD controlled), internal combustion engine (diesel, natural gas), steam turbine (integrated in some refineries, petrochemical plants, and industrial facilities), and hydraulic or other drivers. Electric motors are the dominant driver type in industrial applications where grid power is available and reliable; they are growing in share as operators electrify to reduce onsite emissions.
Gas turbines remain common in remote upstream and midstream applications (pipelines) where grid power is unavailable, though they are gradually being replaced by electric drives with grid extension or on-site solar/ battery (for smaller loads) or by gas turbines with lower emissions (dry low NOx, hydrogen co-firing). Internal combustion engines (gas engines) are widely used for reciprocating compressors in gas gathering and wellhead applications.
By Pressure Rating: The market is segmented by discharge pressure: low pressure (500 bar, primarily hydrogen refueling stations and specialty gas applications). Most natural gas transmission pipelines operate at 50-150 bar. LNG liquefaction compressors operate across a wide pressure range. Hydrogen refueling station compressors for light-duty vehicles require 700-900 bar (storage cascade), and for heavy-duty trucks up to 1000 bar (Type IV and Type V composite cylinders). CO2 injection for EOR or saline storage typically requires 100-300 bar.
By Lubrication Method: The market is segmented into oil-lubricated (oil-flooded screw, oil-lubricated reciprocating) and oil-free (dry screw, diaphragm, oil-free reciprocating, centrifugal, axial, magnetic bearing). Oil-free compressors are essential for applications where oil contamination is unacceptable, including hydrogen, food-grade gases, electronics gases (semiconductor manufacturing), medical gases, and high-purity industrial processes. Oil-free technology is the fastest-growing segment due to increasing purity requirements and hydrogen infrastructure.
By Region: The market is segmented into North America, Europe, Asia-Pacific (APAC), Latin America, and the Middle East & Africa. Asia-Pacific is the largest and fastest-growing regional market, driven by natural gas demand in China, India, and Southeast Asia, industrial manufacturing, and hydrogen infrastructure. North America is a mature market with substantial aftermarket and upgrade activity, LNG export expansion (US Gulf Coast), and growing CCUS and hydrogen projects. The Middle East & Africa is a major market for upstream and gas processing compression. Europe is a mature market transitioning to hydrogen and CCUS applications.
🛒 You can buy this market report at:
https://www.marketresearchfuture.com/checkout?currency=one_user-USD&report_id=41441
Regional Analysis
North America: The North American Gas Compressor Market is mature, stable, and transitioning toward energy transition applications (hydrogen, CCUS) and electrification, while maintaining strong activity in natural gas transmission, LNG export, and upstream production. The United States is the largest natural gas producer globally, driving demand for wellhead, gas gathering, processing, and transmission pipeline compressors. Major interstate natural gas pipeline systems (e.g., TC Energy, Kinder Morgan, Williams, Enbridge, Energy Transfer) operate thousands of compressor stations across the country, requiring ongoing maintenance, upgrades, and capacity expansions.
The US LNG export boom (Sabine Pass, Corpus Christi, Cameron, Calcasieu, Golden Pass, Plaquemines, Port Arthur, Rio Grande, CP2) requires massive compressor installations for liquefaction (axial/centrifugal), boil-off gas handling, and send-out. The Inflation Reduction Act (IRA) and Bipartisan Infrastructure Law (BIL) are funding CCUS projects (carbon capture at industrial facilities, power plants, ethanol plants, and direct air capture hubs) that require CO2 compression. The US hydrogen hub program (H2Hubs, USD 7 billion) is funding several regional hubs (including hydrogen production, storage, pipeline, and end-use compression). Canada's LNG Canada (export facility in Kitimat, BC) is one of the world's largest greenfield LNG projects, with massive compressor requirements. The Canadian oil sands (Alberta) require gas compression for steam-assisted gravity drainage (SAGD) and other enhanced recovery methods. Mexico's natural gas production is declining but domestic consumption is growing, with pipeline imports from the US, driving moderate compressor demand.
Europe: The European Gas Compressor Market is transitioning away from natural gas (following the Russian gas supply shock and EU energy security/decarbonization policies) toward hydrogen, CCUS, and energy efficiency. Europe has a mature natural gas transmission network operated by transmission system operators (TSOs) including Gascade (Germany), Fluxys (Belgium), GRTgaz (France), Snam (Italy), National Gas (UK), Gas Connect Austria, Eustream (Slovakia), and others. The EU's REPowerEU plan (accelerating renewable energy and reducing Russian gas imports) has reduced natural gas demand but increased investment in LNG import terminals (LNG regasification) as alternative supply routes, requiring send-out compressors. Hydrogen is the major growth driver: the European Hydrogen Backbone (EHB) consortium of 33 TSOs plans to build a 40,000 km hydrogen pipeline network by 2040, repurposing existing natural gas pipelines (20-30% of the network) and building new dedicated hydrogen pipelines, both requiring hydrogen compressors.
The EU's European Hydrogen Bank and national hydrogen strategies (Germany, Netherlands, Spain, France, Italy, UK) are funding hydrogen production (electrolysis) and import terminals (ammonia/hydrogen). CCUS projects (Northern Lights in Norway, Porthos in Netherlands, Acorn in Scotland, various projects in the UK's East Coast Cluster) require CO2 compression for pipeline transport and storage. The UK's hydrogen and CCUS clusters (HyNet, East Coast Cluster) include compressor requirements. Norway is a major natural gas producer (export via pipelines to Europe), driving demand for offshore platform compression and onshore processing. Russia, while part of Europe geographically, is substantially isolated from European energy markets following sanctions and pipeline sabotage (Nord Stream), with its gas export infrastructure focused on eastern markets (China via Power of Siberia pipelines).
Asia-Pacific: The Asia-Pacific region is the largest and fastest-growing Gas Compressor Market, driven by surging natural gas demand (China, India, Southeast Asia), industrial manufacturing, LNG import and expansion, and emerging hydrogen economies. China is the world's largest natural gas importer (pipeline gas from Central Asia, Russia, Myanmar; LNG from Qatar, Australia, US, Russia, Africa) and a major domestic producer (onshore conventional, coal-bed methane, tight gas, shale gas). China's massive pipeline network (West-East Gas Pipeline 1/2/3/4, Russia-China Power of Siberia 1/2) requires extensive compressor stations for transmission and distribution.
China is also the world's largest hydrogen producer (primarily grey hydrogen from coal gasification) and is aggressively developing green hydrogen (electrolysis powered by wind/solar in northern and western provinces), with hydrogen pipeline, storage cavern, and refueling station compressor demand growing rapidly. India is the fastest-growing major natural gas market, with government targets to increase the share of natural gas in the energy mix from 6% to 15% by 2030. India's gas pipeline network (GAIL, GSPL, IOCL, HPCL, BPCL) is expanding rapidly, requiring new compressor stations. India's City Gas Distribution (CGD) network (domestic piped natural gas, CNG for vehicles) requires CNG compressors (reciprocating and diaphragm).
Japan and South Korea are major LNG importers (world's largest and second-largest respectively), with extensive regasification terminals requiring send-out compressors. Japan and South Korea are also leaders in hydrogen import infrastructure (liquid hydrogen carriers, ammonia cracking to hydrogen), requiring hydrogen compression for storage and distribution. Southeast Asia (Indonesia, Malaysia, Thailand, Vietnam, Philippines, Singapore) has growing natural gas production (some countries) and LNG import (others), driving regional compressor demand. Australia is a major LNG exporter (North West Shelf, Wheatstone, Gorgon, APLNG, QCLNG, Prelude FLNG), with ongoing compression requirements for gas production, processing, and LNG liquefaction. Australia is also developing large-scale green hydrogen projects (Asian Renewable Energy Hub, Murchison Hydrogen Renewables, Western Green Energy Hub), targeting export to Japan and South Korea.
Latin America: The Latin American Gas Compressor Market is driven by natural gas production (Argentina, Brazil, Bolivia, Trinidad and Tobago, Peru, Colombia), pipeline infrastructure, LNG import (Brazil, Chile, Argentina, Dominican Republic), and upstream oil and gas (Mexico, Brazil, Venezuela, Colombia, Ecuador, Argentina). Brazil's pre-salt oil and gas fields require significant gas compression for production and reinjection (for EOR). Argentina's Vaca Muerta shale formation (Neuquén Basin) is one of the world's largest shale gas resources, requiring massive gas gathering, processing, and pipeline compression (to transport gas from Neuquén to Buenos Aires, and for potential LNG export).
Argentina is also developing natural gas pipelines (Néstor Kirchner pipeline) and LNG import and export facilities. Bolivia (gas production for export to Brazil and Argentina) requires compression for pipelines. Mexico's natural gas production is declining, but domestic consumption is growing, driven by pipeline imports from the US (southwest to central and southern Mexico), requiring pipeline compression and storage. Colombia, Peru, and Ecuador have moderate upstream and pipeline activity. Venezuela's oil and gas production remains severely depressed due to economic collapse and sanctions, with minimal new compressor demand. The region's hydrogen and CCUS markets are nascent.
Middle East & Africa: The Middle East is a major global natural gas producer and exporter (Qatar, Saudi Arabia, UAE, Oman, Iran, Iraq, Kuwait, Bahrain) and is investing heavily in gas expansion (domestic power generation, industrial feedstock, LNG export, blue hydrogen with CCUS). Qatar's North Field expansion (the world's largest natural gas field) is the largest LNG capacity expansion globally, requiring massive compressor installations for gas production, processing, LNG liquefaction (multiple mega-trains), and export. Saudi Arabia is expanding gas production (Jafurah unconventional gas field, the largest non-associated gas field in Saudi Arabia) for domestic power generation (replacing crude oil direct burn), blue hydrogen production (with carbon capture), and petrochemical feedstock.
The UAE (Abu Dhabi) is expanding gas production and processing (including from the Bab, Bu Hasa, Shah fields) and is developing hydrogen and CCUS projects. Oman is expanding natural gas production and LNG export capacity and has major green hydrogen ambitions (the largest announced green hydrogen projects globally). Iran has the world's second-largest natural gas reserves (after Russia) and a large domestic pipeline network, but international sanctions limit new compressor technology imports. Iraq flares significant associated gas (from oil production) and is investing in gas capture, processing, and utilization (power generation), requiring compressor installations. Africa's gas compressor market is driven by Mozambique (Coral South FLNG, Rovuma LNG planned), Nigeria (LNG export, domestic power and industrial gas), Algeria (gas production for pipeline export to Europe via Medgaz, TransMed, Maghreb-Europe), Egypt (Zohr offshore field, LNG export via Idku and Damietta, domestic gas grid), Angola (LNG), Senegal/Mauritania (Greater Tortue Ahmeyim FLNG), and Tanzania (planned LNG). South Africa has moderate gas demand (Sasol synthetic fuels and gas-to-liquids, pipeline imports from Mozambique, and LNG import via Richards Bay). The region's hydrogen and CCUS markets are nascent but growing (Namibia, Mauritania, South Africa).
Competitive Landscape / Key Players
The Gas Compressor Market features a concentrated, globalized competitive landscape dominated by large multinational industrial manufacturers, with significant market share held by a few established players. Competition is based on technology portfolio, global service and aftermarket network, manufacturing scale, engineering capability, and customer relationships (particularly long-term service agreements and frame agreements with major oil and gas and pipeline operators).
Key Companies:
Baker Hughes (General Electric, BHGE): A leading global supplier of centrifugal and reciprocating gas compressors for upstream, midstream, LNG, refining, and industrial applications. Baker Hughes offers a wide portfolio including centrifugal compressors (BCL, PCL, VCL series for pipelines, LNG, refining), reciprocating compressors (Integrally Geared Centrifugal, API 618 reciprocating), and high-speed compressor systems. Baker Hughes is a major supplier to LNG projects (including Qatar North Field, US Gulf Coast LNG, Mozambique LNG, Russia Arctic LNG 2 pre-sanctions), natural gas pipelines (TC Energy, Kinder Morgan, Williams, Enbridge, Gascade, Fluxys, Snam, GAIL), and CCUS (Northern Lights, Porthos, various US projects). The company has an extensive global service network for aftermarket parts, repairs, overhauls, and remote monitoring.
Siemens Energy (formerly Siemens Gas and Power): A major global supplier of gas compressors (centrifugal, axial, reciprocating, screw) for oil and gas, LNG, industrial, and hydrogen applications. Siemens Energy offers centrifugal compressors (STC-GC, STC-SH series), axial compressors (for large gas turbines and LNG), reciprocating compressors, and hydrogen compressors (diaphragm and reciprocating). Siemens Energy is a key supplier to LNG projects (including many US Gulf Coast LNG facilities, Australia LNG, Mozambique LNG, Canada LNG), pipelines (including Nord Stream 1/2 pre-sanctions, various European and Asian pipelines), and hydrogen infrastructure (Germany's H2 pipeline network, H2 refueling stations). The company has a strong digitalization platform (including predictive analytics, digital twins, remote monitoring).
Man Energy Solutions (MAN SE, Volkswagen Group subsidiary): A leading supplier of gas compressors (centrifugal, axial, reciprocating) for upstream, midstream, LNG, refining, petrochemicals, industrial gases, and hydrogen. MAN offers centrifugal compressors (RB, RI, RT series), reciprocating compressors (M series), and axial compressors. MAN is a major LNG supplier (including main refrigerant compressors for liquefaction trains). The company is active in hydrogen compressors (for pipeline, storage, refueling), CCUS, and industrial gases (including air separation unit compressors for oxygen and nitrogen). MAN has a strong European market presence and global service network.
Atlas Copco AB: A global leader in industrial compressors (oil-injected and oil-free rotary screw, reciprocating, centrifugal, diaphragm) for compressed air, process gas, and specialty gas applications. Atlas Copco's compressor portfolio includes oil-free screw compressors (Z-series, for instrument air, plant air, hydrogen, food-grade), centrifugal compressors (for large air and nitrogen compression), diaphragm compressors (for high-purity hydrogen and specialty gases), and reciprocating compressors (high pressure). The company is a leading supplier for hydrogen refueling stations (diaphragm compressors for final stage compression to 700-900 bar), industrial manufacturing, and electronics. Atlas Copco has an extensive global distribution and service network.
Ingersoll Rand Inc.: A diversified industrial manufacturer with a large compressor portfolio including reciprocating, rotary screw, centrifugal, and oil-free compressors for compressed air, process gas, natural gas, and hydrogen. Ingersoll Rand's gas compressor products include high-speed centrifugal compressors, oil-flooded screw compressors, and reciprocating compressors for CNG, wellhead gas, and pipeline boosting. The company serves the industrial compressed air market (large and growing) and oil and gas upstream and CNG.
Howden Group (Howden, a Chart Industries company): A specialist supplier of rotary screw compressors (oil-injected and oil-free), reciprocating compressors, centrifugal compressors, and hybrid compressors for process gas, refrigeration, hydrogen, biogas, and industrial applications. Howden is a leader in screw compressors (SVG series) for refrigeration (cooling, cold storage, industrial refrigeration) and boil-off gas (BOG) handling at LNG terminals (recondensation). Howden is also active in hydrogen (screw and reciprocating compressors), biogas upgrading, and waste heat recovery. Chart Industries is a major cryogenic equipment manufacturer (LNG tanks, heat exchangers, cold boxes) that acquired Howden to provide integrated compressor solutions.
Ariel Corporation: The world's largest manufacturer of separable reciprocating gas compressors for upstream, wellhead, gas gathering, gas lift, CNG, and pipeline applications. Ariel (privately held, headquartered in Ohio, USA) dominates the mid-sized reciprocating compressor market (200-8000 HP, frame sizes JGC, JGJ, JGN, KBU, KBM, KBC, KBB, KBD, etc.) with over 90% market share in North America for certain applications. Ariel compressors are widely used in oil and gas fields (Permian Basin, Eagle Ford, Marcellus, Bakken, Niobrara, Vaca Muerta, etc.), CNG refueling stations, and small pipelines. Ariel does not manufacture centrifugal or screw compressors.
Other Notable Manufacturers: Kobelco Compressors (Kobe Steel, Japan), Mitsubishi Heavy Industries (MHI, Japan), Ebara Corporation (Japan), Sundyne (USA, part of Dover Precision Components), Corken (USA, part of IDEX), Hitachi (Japan, compressor division), Burckhardt Compression (Switzerland, high-pressure reciprocating and diaphragm, particularly hydrogen), PDC Machines (USA, diaphragm compressors for hydrogen), HAUG Sauer (Germany, diaphragm compressors), Hydro-Pac (USA, high-pressure), Fluitron (USA, diaphragm), Mehrer Compression (Germany, dry-running reciprocating), Haskel (USA, air-driven boosters, part of Ingersoll Rand), Sera GmbH (Germany, diaphragm), Maximator (Germany, high-pressure), and many regional and local manufacturers.
Strategic Developments: Major compressor manufacturers are expanding their hydrogen compressor portfolios (diaphragm, reciprocating, oil-free screw) to capture the growing hydrogen refueling station and pipeline market. Strategic acquisitions are consolidating the market: Chart Industries acquired Howden (2023) to combine cryogenic and compression technologies for LNG, hydrogen, and CCUS. Baker Hughes, Siemens Energy, and MAN are expanding their CCUS and hydrogen compression offerings and forming partnerships with project developers, EPCs, and hydrogen producers.
Digitalization and predictive maintenance offerings (IoT sensor integration, cloud analytics, vibration monitoring, AI diagnostics, digital twins) are becoming standard, with manufacturers offering long-term service agreements (LTSAs) that include remote monitoring and guaranteed uptime. Electrification (electric motor drives with VFDs replacing gas turbines or engine drives) is a key trend for new pipeline and LNG facilities, as operators seek to reduce Scope 1 and Scope 2 emissions. Manufacturers are developing hydrogen-capable compressors (capable of handling up to 100% hydrogen, including upgrading existing compressor components for hydrogen service) for hydrogen blending and eventual full hydrogen conversion of natural gas pipelines.
Latest Industry News & Developments
Hydrogen Compressor Certification Standard Released (March 2025): The International Organization for Standardization (ISO) released ISO 19880-3 (Hydrogen fueling stations - Part 3: Compressors) providing uniform safety and performance requirements for hydrogen compressors used in gaseous hydrogen refueling stations (35 MPa, 70 MPa, and higher for heavy-duty). The standard addresses hydrogen embrittlement, leak tightness, materials compatibility, valve and seal design, and testing protocols, providing clarity for manufacturers, station developers, and regulators and accelerating hydrogen infrastructure investment.
US DOE Announces CCUS Compressor Funding (February 2025): The US Department of Energy (DOE) announced USD 125 million in funding for next-generation CO2 compression technologies for carbon capture and storage (CCS) and direct air capture (DAC) hubs. The funding supports development of higher-efficiency, lower-cost CO2 compressors (including integrally geared centrifugal, oil-free reciprocating, and supercritical CO2 compression) capable of handling the unique properties of CO2 (phase behavior, impurities, corrosion). Recipients include Baker Hughes, Siemens Energy, Atlas Copco, and several small businesses and universities.
Largest Hydrogen Compressor Order (January 2025): A leading hydrogen project developer (name not disclosed in early announcements, later identified as a joint venture between two major European energy companies) placed the largest single hydrogen compressor order to date: over USD 150 million for multiple diaphragm and reciprocating hydrogen compressors to be deployed at a large-scale green hydrogen production facility (500 MW electrolysis) and associated hydrogen pipeline, storage, and refueling station network in the Netherlands (part of the Dutch Hydrogen Valley). The compressors (supplied by Burckhardt Compression and PDC Machines) will handle up to 100 tonnes per day of hydrogen at pressures up to 900 bar.
Market Challenges & Opportunities
Key Restraints: The primary challenge facing the Gas Compressor Market is the long-term transition away from fossil fuels (natural gas) toward renewable energy and hydrogen, which, while creating new opportunities for hydrogen compressors, reduces growth in the large natural gas compressor segment in mature markets. High capital cost of compressors (especially large centrifugal units for pipelines and LNG) creates barriers for new entrants and smaller projects. The energy efficiency of compressors (power consumption can be 10-20% of facility energy use) is a major operational cost, and improving efficiency (through VFDs, better aerodynamics, reduced leakage) requires investment. Hydrogen compression is challenging due to hydrogen's low molecular weight (requires high-speed, multi-stage compression), high diffusivity (leakage), embrittlement of metals (requires special materials, coatings, and heat treatments), and wide flammability range (safety systems).
Methane emissions from compressor seals and fugitive emissions are under increasing regulatory scrutiny, requiring low-emission seals (dry gas seals, magnetic bearings, low-blowdown valves) and leak detection and repair (LDAR) programs. Supply chain disruptions (post-COVID, geopolitical) affect lead times for castings, forgings, bearings, seals, instrumentation, and control systems. Skilled labor shortages for installation, commissioning, and maintenance (particularly for high-speed rotating equipment) constrain market growth.
Emerging Opportunities: The most significant opportunity lies in the hydrogen compression market: hydrogen refueling stations (for fuel cell electric vehicles, particularly heavy-duty trucks, buses, drayage, logistics) require diaphragm and reciprocating compressors for final stage compression to 700-1000 bar. Hydrogen pipelines (repurposed natural gas pipelines or new dedicated lines) require centrifugal and reciprocating compressors capable of handling up to 100% hydrogen.
Hydrogen storage (salt caverns, depleted reservoirs, lined rock caverns, composite vessels) requires compressors for injection and withdrawal. Hydrogen blending (injecting hydrogen into natural gas pipelines at 5-20% blend) requires compressors compatible with hydrogen-natural gas mixtures. CCUS presents a second major growth opportunity: CO2 compression for pipelines (typically centrifugal) and injection wells (reciprocating). Carbon capture at industrial facilities (cement, steel, chemicals, refining, ethanol), power plants (natural gas and coal with post-combustion capture), and direct air capture (DAC) facilities requires CO2 compressors.
Electrification of compressors (replacing gas turbines with electric motors) creates aftermarket upgrade opportunities and new equipment sales for both compressors and VFDs. Retrofitting existing compressor stations with low-emission seals, dry gas seals, and vapor recovery units reduces methane emissions and extends asset life. Digitalization and predictive maintenance offerings generate high-margin recurring revenue streams (long-term service agreements) for manufacturers.
Future Potential: The long-term future of the Gas Compressor Market is defined by the energy transition: stable natural gas demand (particularly in Asia and for LNG) through 2035-2040, complemented by rapidly growing hydrogen and CCUS compression demand. The natural gas compressor market (upstream, pipeline, LNG) is projected to grow at moderate rates (2-3% CAGR) through 2035, with strong demand from Asia (China, India, Southeast Asia), the Middle East, and Africa. The hydrogen compressor market (refueling stations, pipelines, storage, production facilities) is projected to grow at 20-30% CAGR through 2035, though from a smaller base.
The CCUS compressor market is projected to grow at 15-25% CAGR through 2035. By 2035, hydrogen and CCUS could account for 20-30% of total gas compressor market revenue (up from less than 5% today), with natural gas remaining the dominant segment (70-80%). The industrial compressed air market (electric motor-driven rotary screw and centrifugal) will continue to grow with global industrial production. Successful participants will develop dual-capability compressors (natural gas today, hydrogen tomorrow), strong aftermarket and digital services, and global supply chains capable of serving both traditional and emerging markets.
To explore more market insights, visit us at:
https://www.marketresearchfuture.com/reports/gas-compressor-market-41441
Final Market Summary
The Gas Compressor Market is positioned for stable, moderate growth over the forecast period from 2025 to 2035, underpinned by continued global natural gas demand (particularly in Asia, the Middle East, and for LNG exports), industrial manufacturing expansion, and emerging growth drivers in hydrogen infrastructure and carbon capture, utilization, and storage (CCUS). Driven by a compound annual growth rate (CAGR) of 3.53%, the market is projected to expand from USD 12.93 billion in 2025 to USD 18.29 billion by 2035.
The market is mature and technically diverse, encompassing centrifugal compressors for high-flow natural gas pipelines and LNG, reciprocating compressors for high-pressure oil and gas and CNG applications, and diaphragm and oil-free screw compressors for high-purity hydrogen and specialty gases. While the long-term energy transition presents a structural challenge to the natural gas segment, the rapid development of hydrogen refueling stations, hydrogen pipelines, hydrogen storage, and CCUS projects (particularly in North America and Europe, supported by the US Inflation Reduction Act and EU Green Deal) creates substantial new compressor demand.
The competitive landscape is concentrated among large multinational manufacturers (Baker Hughes, Siemens Energy, MAN Energy Solutions, Atlas Copco, Ingersoll Rand, Howden/Chart, Ariel) that are expanding their hydrogen and CCUS portfolios, digital and predictive maintenance services, and electrified drive options. The market's long-term growth will depend on the pace of hydrogen infrastructure deployment, CCUS project financing, and natural gas demand in Asia and the Middle East.
More Related Reports from MRFR Library:
Secondary Battery Market https://www.marketresearchfuture.com/reports/secondary-battery-market-22986
Residential Solar Power Market https://www.marketresearchfuture.com/reports/residential-solar-power-market-22987
Smart Water Meter Market https://www.marketresearchfuture.com/reports/smart-water-meter-market-22993
Vision Transformers Market https://www.marketresearchfuture.com/reports/vision-transformers-market-22999
Waste Heat To Power Market https://www.marketresearchfuture.com/reports/waste-heat-to-power-market-23001
Interlocked Armored Cable Market https://www.marketresearchfuture.com/reports/interlocked-armored-cable-market-23767
Oil & Gas Drill Bit Market https://www.marketresearchfuture.com/reports/oil-gas-drill-bit-market-23773
Rooftop Solar PV Module Market https://www.marketresearchfuture.com/reports/rooftop-solar-pv-module-market-23817
Motor Soft Starter Market https://www.marketresearchfuture.com/reports/motor-soft-starter-market-24905
Next Generation Advanced Battery Market https://www.marketresearchfuture.com/reports/next-generation-advanced-battery-market-24932
About Market Research Future:
Market Research Future® (Part of WantStats Research and Media Pvt. Ltd.) has specialized research analysts in the areas of Aerospace & Defense, Automotive, C&M, Energy & Power, F&B, Healthcare & Pharmaceutical, ICT, Industrial Equipment, Packaging Construction & Mining and Semiconductor. Market Research Future (MRFR) is a global market research company that takes pride in its services, offering a complete and accurate analysis with regard to diverse markets and consumers worldwide. MRFR's approach combines the proprietary information with various data sources to give an extensive understanding to the client about the latest key developments, expected events and about what action to take based on these aspects.
Contact
Market Research Future (Part of Wantstats Research and Media Private Limited)
99 Hudson Street, 5Th Floor
New York, NY 10013
United States of America
+1 628 258 0071 (US)
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Gas Compressor Market to Reach USD 18.29 Billion by 2035 at 3.53% CAGR here
News-ID: 4546439 • Views: …
More Releases from MRFR
Power Tools Market to Reach USD 82294.64 Million by 2035 at 6.26% CAGR
As per MRFR analysis, the Power Tools Market Size was estimated at USD 42190.3 Million in 2024. The Power Tools industry is projected to grow from USD 44832.27 Million in 2025 to USD 82294.64 Million by 2035, exhibiting a compound annual growth rate (CAGR) of 6.26% during the forecast period 2025 - 2035.
Market Overview
The Power Tools Market encompasses a wide range of electrically, pneumatically, or fuel-driven devices designed to perform…
Forestry Equipment Market to Reach USD 67.33 Billion by 2035 at 3.31% CAGR
As per Market Research Future analysis, the Forestry Equipment Market Size was estimated at 47.05 USD Billion in 2024. The Forestry Equipment industry is projected to grow from 48.61 USD Billion in 2025 to 67.33 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 3.31% during the forecast period 2025 - 2035.
Market Overview
The Forestry Equipment Market encompasses a comprehensive range of specialized machinery, vehicles, and tools designed…
Residential Cold Climate Heat Pump Market to Reach USD 37.07 Billion by 2035 at …
As per Market Research Future analysis, the Residential Cold Climate Heat Pump Market Size was estimated at 14.26 USD Billion in 2024. The Residential Cold Climate Heat Pump industry is projected to grow from 15.55 USD Billion in 2025 to 37.07 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 9.07% during the forecast period 2025 - 2035.
Market Overview
The Residential Cold Climate Heat Pump Market encompasses advanced…
Hydraulic Elevators Market to Reach USD 19.5 Billion by 2035 at 3.0% CAGR
As per Market Research Future analysis, the Hydraulic Elevators Market Size was estimated at 14.01 USD Billion in 2024. The Hydraulic Elevators industry is projected to grow from 14.44 USD Billion in 2025 to 19.5 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 3.0% during the forecast period 2025 - 2035.
Market Overview
The Hydraulic Elevators Market encompasses vertical transportation systems that utilize hydraulic fluid, a pump system,…
More Releases for LNG
LNG Bunkering Market Growth, Trends & Opportunities 2025 | Top key players - Tre …
LNG Bunkering Market, as analyzed in the study by DataM Intelligence, presents a detailed overview of the industry with in-depth insights, historical data, and key statistics. The report thoroughly examines market dynamics, competitive strategies, and major players, highlighting their product lines, pricing structures, financials, growth plans, and regional outreach.
The Global LNG Bunkering Market is expected to grow at a CAGR of 66.4% during the forecasting period (2024-2031).
Get a Free Sample…
Mea Floating Lng Power Vessel Market Emerging Trends and Growth Prospects 2034 | …
On April 8, 2025, Exactitude Consultancy., Ltd. released a research report titled "Mea Floating Lng Power Vessel Market". In-depth research has been compiled to provide the most up-to-date information on key aspects of the worldwide market. This research report covers major aspects of the Mea Floating Lng Power Vessel Market including drivers, restraints, historical and current trends, regulatory scenarios, and technological advancements. It provides the industry overview with growth analysis…
What's Driving the LNG Bunkering Market Trends? Key Companies are Skangass AS., …
A research report on 'LNG Bunkering Market' Added by DEC Research features a succinct analysis on the latest market trends. The report also includes detailed abstracts about statistics, revenue forecasts and market valuation, which additionally highlights its status in the competitive landscape and growth trends accepted by major industry players.
Request a sample of this research report @ https://www.decresearch.com/request-sample/detail/702
The size of LNG Bunkering Market was registered at USD 800 Million in…
LNG Bunkering Market Key Players Polskie LNG, Eagle LNG, ENN Energy, EVOL LNG, F …
The LNG Bunkering Market report add detailed competitive landscape of the global market. It includes company, market share analysis, product portfolio of the major industry participants. The report provides detailed segmentation of the LNG Bunkering industry based on product segment, technology, end user segment and region.
As per a recent news snippet, the Caribbean is one of the most lucrative regions for LNG bunkering market, as the shipping sector seeks compliance…
LNG Bunkering Industry to surpass $12bn by 2024:ENGIE,Polskie LNG,Eagle LNG, ENN …
LNG Bunkering Market size is set to exceed USD 12 billion by 2024.Growing demand for cleaner fuel coupled with strict emission regulations to reduce the airborne emissions predominantly in North America and Europe will stimulate LNG bunkering market. In 2015, International Maritime Organization (IMO) introduced Tier III norms to curb NOx emissions from marine vessels among Emission Control Areas (ECAs) under maritime boundaries.
Request for a sample copy of this…
Global Liquefied Natural Gas (LNG) Market 2018-22 : LNG bunkering, progressing L …
ResearchMoz presents Professional and In-depth Study of "Global Liquefied Natural Gas (LNG) Market: Industry Analysis & Outlook (2018-2022)" with coming years Industries Trends, Projections of Global Growth, Major Key Player and Case Study, Review, Share, Size, Effect.
' '
Liquefied Natural Gas (LNG) is a liquid form of natural gas, which is composed mainly of methane and other gases such as Ethane, Propane, Butane and Nitrogen. LNG liquefaction is a procedure…

