
Press release
Can SiC Power Semiconductors Redefine the Future of Electric Vehicles and Energy Systems?
SiC Power Semiconductor Market
Get the full PDF sample copy of the report: (Includes full table of contents, list of tables and figures, and graphs) https://www.databridgemarketresearch.com/request-a-sample/?dbmr=global-sic-power-semiconductor-market
The global silicon carbide (SiC) power semiconductor market is witnessing accelerated growth due to increasing electrification across automotive, industrial, energy, and consumer electronics sectors. SiC-based devices provide superior switching performance, higher thermal conductivity, lower energy losses, and enhanced efficiency compared to conventional silicon semiconductors. The growing transition toward high-voltage and high-frequency applications is significantly supporting market expansion. In addition, strong government initiatives promoting EV adoption and renewable energy integration are creating favorable conditions for long-term market growth.
Market Size & Forecast
2025 Market Size: USD 2.21 Billion
2026 Projected Market Size: USD 2.79 Billion
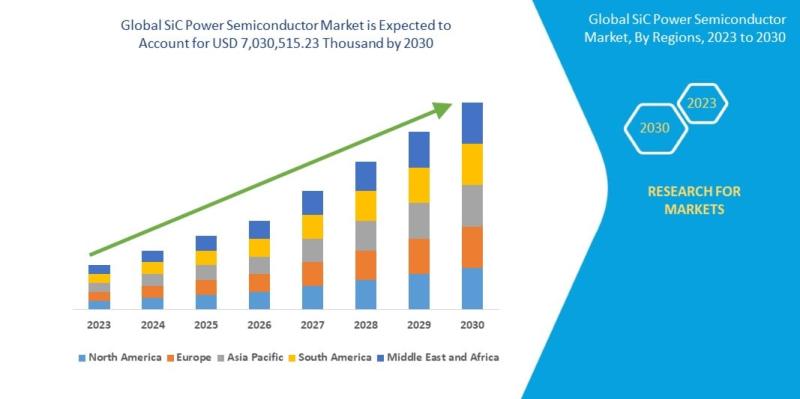
2030 Projected Market Size: USD 7.03 Billion
CAGR (2026-2030): 26.0%
Largest Region: Asia-Pacific
Fastest Growing Region: Asia-Pacific
Key Market Report Takeaways
Asia-Pacific accounts for the largest market share, supported by strong semiconductor manufacturing ecosystems and expanding EV production in China, Japan, and South Korea.
Asia-Pacific is projected to remain the fastest-growing region due to increasing investments in renewable energy infrastructure and government-led electrification initiatives.
SiC MOSFETs represent the highest market share segment owing to their extensive adoption in electric vehicles, industrial motor drives, and charging infrastructure.
Automotive applications dominate the market due to growing penetration of battery electric vehicles and demand for high-efficiency power modules.
Electric vehicle manufacturers remain the leading end-use segment, driven by increasing global EV production and stringent emission reduction targets.
Industrial and energy sectors are increasingly integrating SiC power devices for efficient energy conversion and high-power applications.
Rapid investments in wafer fabrication capacity and vertical integration strategies are intensifying competitive dynamics across the global market.
Market Trends & Highlights
Asia-Pacific leads the global market due to the presence of large-scale semiconductor fabrication facilities, strong EV manufacturing capabilities, and significant investments in industrial automation and renewable energy systems.
North America and Europe continue to witness strong growth supported by government semiconductor initiatives, energy transition policies, and rising adoption of advanced power electronics.
Automotive applications remain the dominant segment as SiC semiconductors improve EV range, charging efficiency, and thermal performance in high-voltage architectures.
Increasing demand for energy-efficient devices, rapid deployment of EV charging infrastructure, and expansion of renewable energy integration are major growth accelerators globally.
Advancements in 200mm SiC wafer technology, high-voltage MOSFETs, and integrated power modules are reshaping manufacturing efficiency and reducing production costs.
Strategic partnerships, capacity expansions, government funding programs, and long-term supply agreements between automakers and semiconductor manufacturers are strengthening market competitiveness.
Access full report information and current publication status: https://www.databridgemarketresearch.com/reports/global-sic-power-semiconductor-market
Market Dynamics
Market Drivers
Rising Adoption of Electric Vehicles
The rapid expansion of the global electric vehicle industry is significantly driving demand for SiC power semiconductors. SiC devices offer higher switching efficiency, reduced energy losses, and improved thermal management compared to conventional silicon devices. Automotive manufacturers are increasingly integrating SiC MOSFETs into onboard chargers, inverters, and DC-DC converters to enhance vehicle performance and extend driving range. Strong EV adoption across China, the U.S., Germany, and other European countries continues to accelerate market demand.
Expansion of Renewable Energy Infrastructure
Growing investments in solar, wind, and energy storage systems are increasing the requirement for high-efficiency power conversion technologies. SiC semiconductors improve energy conversion efficiency in photovoltaic inverters, wind power systems, and grid infrastructure. Governments across Europe, North America, and Asia-Pacific are implementing clean energy initiatives and carbon neutrality goals, supporting large-scale deployment of advanced power electronics. The increasing integration of renewable energy into smart grids is further strengthening market growth.
Growing Demand for Energy-Efficient Industrial Systems
Industrial automation and smart manufacturing trends are accelerating the adoption of SiC-based power modules in motor drives, robotics, and industrial power supplies. SiC devices enable higher operating temperatures, faster switching speeds, and reduced cooling requirements, improving operational efficiency. Industries are increasingly prioritizing energy optimization and reduced operational costs, particularly in high-power applications. The trend is especially prominent in developed manufacturing economies such as Japan, Germany, and the United States.
Advancements in Charging Infrastructure
The rapid deployment of fast-charging infrastructure for electric vehicles is creating strong demand for SiC semiconductors. SiC-based charging systems enable higher power density, reduced charging times, and improved energy efficiency. Public and private investments in ultra-fast charging networks across Europe, China, and North America are significantly contributing to market expansion. Increasing urbanization and EV penetration are further supporting infrastructure development globally.
Government Support for Semiconductor Manufacturing
Governments worldwide are introducing semiconductor incentive programs to strengthen domestic manufacturing capabilities and reduce supply chain dependence. Initiatives such as the U.S. CHIPS Act, European semiconductor investments, and Asia-Pacific industrial policies are driving investments in SiC wafer production and fabrication facilities. Financial incentives, R&D funding, and localization strategies are encouraging capacity expansion among semiconductor manufacturers. These developments are expected to support long-term market competitiveness and supply stability.
Market Restraints
High Manufacturing and Material Costs
SiC power semiconductors involve significantly higher production costs compared to traditional silicon-based devices. The manufacturing process requires advanced crystal growth technologies, specialized fabrication equipment, and expensive raw materials. Limited availability of high-quality SiC wafers further increases production expenses. Cost sensitivity remains a key challenge in price-competitive applications, particularly in emerging economies.
Complex Fabrication Processes
The production of SiC wafers and devices involves complex processing steps and stringent quality control requirements. Challenges related to crystal defects, wafer yield optimization, and thermal stress management continue to impact manufacturing scalability. These technical complexities increase operational costs and limit production efficiency for semiconductor manufacturers. Smaller companies often face difficulties entering the market due to high capital investment requirements.
Supply Chain Constraints
The market continues to experience supply-demand imbalances due to limited global SiC wafer production capacity. Dependence on a relatively concentrated supplier base creates risks related to procurement delays and pricing volatility. Geopolitical tensions, trade restrictions, and logistics disruptions further affect global semiconductor supply chains. Automotive and industrial sectors remain particularly vulnerable to component shortages.
Integration Challenges with Existing Systems
Transitioning from silicon-based power devices to SiC technologies often requires redesigning existing power architectures and thermal management systems. Compatibility issues, engineering complexity, and integration costs can delay adoption across industrial and automotive applications. Small and medium-sized enterprises may face challenges in upgrading legacy systems due to limited technical expertise and budget constraints.
Intense Pricing Competition
Increasing market participation and rapid capacity expansion are intensifying pricing pressure across the industry. Large manufacturers are aggressively investing in scaling production and improving cost efficiency, creating challenges for smaller and regional players. Competitive pricing strategies may affect profit margins, particularly in commoditized application areas. Market participants must continuously invest in innovation to maintain differentiation and technological leadership.
Market Opportunities
Expansion of 800V EV Architectures
The growing adoption of 800V electric vehicle platforms presents significant opportunities for SiC power semiconductor manufacturers. SiC devices are highly suitable for high-voltage systems due to their superior thermal efficiency and reduced switching losses. Automotive OEMs are increasingly transitioning toward advanced powertrain architectures to support ultra-fast charging and extended vehicle range. This trend is expected to create strong long-term revenue opportunities globally.
Development of Smart Grid Infrastructure
Modernization of power grids and deployment of smart energy systems are generating new demand for advanced power semiconductors. SiC devices improve grid efficiency, enable higher power conversion performance, and support renewable energy integration. Governments and utility providers are increasing investments in smart grid technologies to enhance energy reliability and reduce transmission losses. Emerging economies are expected to witness substantial infrastructure-related opportunities.
Growth in Aerospace and Defense Applications
Aerospace and defense sectors are increasingly adopting SiC semiconductors for radar systems, satellite communication, and advanced military electronics. The ability of SiC devices to operate under extreme temperatures and high-voltage conditions makes them highly suitable for mission-critical applications. Rising defense modernization programs and increasing investments in space technologies are expected to support future market growth.
Emergence of 200mm SiC Wafer Technology
The transition toward 200mm SiC wafer manufacturing is expected to significantly improve production scalability and reduce manufacturing costs. Larger wafer sizes enable higher chip output and improved economies of scale for semiconductor manufacturers. Companies investing in advanced wafer technologies are likely to gain competitive advantages through enhanced operational efficiency and improved supply capabilities.
Increasing Strategic Collaborations
Collaborations between automakers, semiconductor companies, and renewable energy firms are creating new opportunities for technology integration and market expansion. Long-term supply agreements and joint development partnerships are improving product innovation and ensuring stable component availability. Strategic alliances are also accelerating commercialization of advanced SiC solutions across automotive, industrial, and energy sectors.
Market Challenges
Limited Global Wafer Production Capacity
The global market faces ongoing challenges related to insufficient SiC wafer manufacturing capacity. Demand from automotive and industrial sectors is growing faster than production expansion, creating supply shortages. Establishing new fabrication facilities requires substantial capital investment and long lead times. Capacity limitations may constrain short-term market growth and increase procurement costs.
Quality Control and Defect Management
SiC wafer manufacturing remains technically challenging due to crystal defects and inconsistencies in substrate quality. Defects can impact device reliability, yield rates, and long-term performance. Manufacturers must invest heavily in advanced quality control systems and process optimization technologies. Maintaining consistent production standards remains critical for high-performance automotive and industrial applications.
Rapid Technological Evolution
Continuous advancements in semiconductor technologies are increasing pressure on manufacturers to accelerate innovation cycles. Companies must regularly upgrade fabrication technologies, improve device performance, and reduce costs to remain competitive. Rapid technological shifts may increase R&D expenditures and shorten product life cycles, particularly among smaller market participants.
Geopolitical and Trade Risks
Global semiconductor supply chains remain vulnerable to geopolitical tensions, export restrictions, and trade policy changes. Dependence on specific regions for raw materials and fabrication capacity increases operational risks for manufacturers. Trade disputes between major economies may disrupt component supply, delay production schedules, and increase pricing uncertainty across the market.
Skilled Workforce Shortages
The semiconductor industry faces increasing shortages of highly skilled engineers and technical professionals required for advanced SiC manufacturing and design. Growing competition for specialized talent may impact R&D capabilities and operational efficiency. Workforce limitations are particularly evident in emerging semiconductor hubs where technical infrastructure is still developing.
Market Segmentation & Analysis
By Product Type
SiC MOSFETs
SiC MOSFETs hold the largest market share due to their extensive deployment in electric vehicles, industrial drives, and renewable energy systems. These devices offer lower switching losses, higher power density, and improved thermal performance compared to traditional silicon-based transistors. Automotive applications remain the primary growth driver, particularly in EV traction inverters and charging systems. The segment is projected to maintain a CAGR above the overall market average due to increasing demand for high-efficiency power electronics.
SiC Schottky Diodes
SiC Schottky diodes are widely used in power supplies, solar inverters, and industrial motor drives due to their high-frequency switching capabilities and low reverse recovery losses. The segment continues to benefit from growing industrial automation and renewable energy adoption. These devices improve system reliability and energy efficiency in high-power applications. Increasing deployment in data centers and telecommunications infrastructure is supporting segment expansion globally.
SiC Power Modules
SiC power modules are gaining traction across automotive and industrial applications requiring compact and high-performance power systems. The segment is witnessing strong demand due to rising adoption of integrated power electronics solutions. Power modules simplify system integration while improving thermal management and energy conversion efficiency. Growing investments in EV production and industrial automation are expected to support long-term growth.
By Application
Automotive
The automotive segment dominates the market and accounts for the highest revenue share. Increasing production of battery electric vehicles and hybrid electric vehicles is driving substantial demand for SiC semiconductors. SiC devices enhance inverter efficiency, reduce vehicle weight, and support high-voltage powertrain architectures. The segment is projected to witness the highest growth rate due to accelerating EV adoption across China, Europe, and North America.
Industrial
Industrial applications represent a significant market segment driven by rising automation and energy efficiency requirements. SiC semiconductors are increasingly deployed in motor drives, robotics, industrial power supplies, and factory automation systems. The demand for efficient high-power systems is encouraging manufacturers to transition toward advanced semiconductor technologies. Industrial modernization initiatives across developed economies continue to support segment growth.
Energy & Power
The energy and power segment is expanding steadily due to increasing deployment of renewable energy systems and smart grid infrastructure. SiC devices are widely used in solar inverters, wind turbines, and energy storage systems for efficient power conversion. Government investments in clean energy transition and grid modernization are creating favorable market conditions. The segment is expected to witness strong long-term growth globally.
By End-User
Electric Vehicle Manufacturers
Electric vehicle manufacturers represent the dominant end-user segment due to the extensive integration of SiC devices in EV powertrains and charging systems. Rising global EV production and increasing consumer demand for long-range vehicles are driving segment expansion. Automotive OEMs are entering long-term supply agreements with semiconductor manufacturers to secure component availability. The segment is expected to maintain strong revenue growth throughout the forecast period.
Industrial Equipment Manufacturers
Industrial equipment manufacturers are increasingly adopting SiC semiconductors for high-performance motor control and power conversion applications. Demand for energy-efficient industrial machinery and automation systems is supporting growth across manufacturing sectors. Advanced power electronics are becoming essential for improving operational productivity and reducing energy consumption.
Renewable Energy Companies
Renewable energy companies are adopting SiC devices to improve the efficiency of solar, wind, and energy storage systems. Growing investments in renewable infrastructure and clean energy targets are supporting market demand. The increasing deployment of distributed energy systems is further expanding application opportunities for SiC semiconductors.
By Technology
Discrete Devices
Discrete SiC devices account for a substantial market share due to their widespread usage in power electronics systems requiring flexibility and customization. These devices are commonly deployed across automotive, industrial, and consumer electronics applications. Increasing demand for compact and energy-efficient systems continues to support segment growth.
Integrated Power Modules
Integrated power modules are projected to witness the fastest growth due to increasing demand for compact, high-efficiency, and thermally optimized solutions. These modules simplify system design and improve performance reliability in high-voltage applications. The segment is benefiting from strong adoption in EVs and industrial automation systems.
Unlock detailed market insights and customized analysis today: https://www.databridgemarketresearch.com/inquire-before-buying/?dbmr=global-sic-power-semiconductor-market
Regional Analysis
By geography, the market is categorized into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
North America
North America represents a major market for SiC power semiconductors due to strong technological capabilities and increasing investments in electric mobility and semiconductor manufacturing. The United States accounts for the largest regional share supported by the presence of leading semiconductor companies, EV manufacturers, and government-backed semiconductor initiatives. Rising deployment of renewable energy systems and advanced industrial automation technologies is further driving demand. The region benefits from robust R&D infrastructure and strong regulatory support for energy-efficient technologies.
Europe
Europe is an established and steadily growing market driven by stringent emission regulations and strong electrification initiatives. Germany, the U.K., and France remain key contributors due to their advanced automotive industries and growing semiconductor investments. The region is witnessing increasing adoption of SiC devices in EV manufacturing, renewable energy systems, and industrial automation. European governments are actively supporting semiconductor supply chain localization and sustainable energy transition programs.
Asia Pacific
Asia Pacific dominates the global market and is projected to remain the fastest-growing region during the forecast period. China, Japan, South Korea, and India are major contributors due to strong semiconductor manufacturing ecosystems and expanding EV production. Rapid industrialization, rising energy demand, and government support for clean energy adoption are accelerating market expansion. The region also benefits from large-scale electronics manufacturing and growing investments in charging infrastructure and renewable energy projects.
Latin America
Latin America represents an emerging market with gradual adoption of advanced power semiconductor technologies. Brazil and Mexico are leading regional markets supported by expanding industrial activities and increasing investments in renewable energy projects. Infrastructure modernization and improving electrification initiatives are creating growth opportunities for SiC applications. However, economic volatility and limited semiconductor manufacturing capabilities continue to restrict market expansion.
Middle East & Africa
The Middle East & Africa region is witnessing steady but comparatively slower market growth. Increasing investments in renewable energy infrastructure, industrial diversification, and smart city projects are supporting demand for advanced power electronics. Government initiatives focused on energy efficiency and sustainable infrastructure development are contributing to market expansion. However, limited local manufacturing ecosystems and infrastructure gaps remain key growth constraints across several countries.
Key Insights:
Largest Region: Asia-Pacific
Fastest Growing Region: Asia-Pacific
Competitive Landscape
Market Structure Overview
The global SiC power semiconductor market is moderately consolidated with the presence of several multinational semiconductor manufacturers and specialized regional players. Competition is driven by technological innovation, wafer manufacturing capabilities, product efficiency, and long-term supply agreements with automotive and industrial customers. Leading companies are heavily investing in capacity expansion, R&D activities, and advanced SiC wafer technologies to strengthen market positioning. Competitive landscape analysis helps evaluate strategic positioning, product differentiation, and operational strengths of major industry participants.
Key Industry Players
Leading companies are focusing on portfolio diversification, vertical integration, and expansion of fabrication capabilities to improve market competitiveness. Major players maintain strong geographic presence across North America, Europe, and Asia-Pacific while emphasizing advanced power electronics solutions for automotive and industrial applications. Companies are increasingly prioritizing long-term customer partnerships and next-generation SiC device development.
List of Key Industry Players
Wolfspeed, Inc.
STMicroelectronics N.V.
Infineon Technologies AG
ON Semiconductor Corporation
ROHM Co., Ltd.
Mitsubishi Electric Corporation
Fuji Electric Co., Ltd.
Microchip Technology Inc.
Toshiba Corporation
GeneSiC Semiconductor Inc.
Competitive Strategies
Companies are actively investing in new product launches, advanced SiC MOSFET technologies, and large-scale wafer fabrication facilities to enhance production efficiency. Strategic partnerships with EV manufacturers and renewable energy companies are becoming increasingly common across the industry. Mergers, acquisitions, and joint ventures are helping companies strengthen supply chains and expand geographic reach. Market participants are also focusing on 200mm wafer technology and integrated power module development to achieve competitive differentiation and improve operational scalability.
Emerging Players & Market Dynamics
Emerging startups and niche semiconductor companies are intensifying market competition through specialized product offerings and innovative manufacturing technologies. New entrants are increasingly targeting automotive and industrial applications with cost-effective and customized solutions. Venture capital investments and government funding initiatives are supporting innovation across the semiconductor ecosystem. Growing focus on digital transformation, electrification, and energy efficiency continues to create opportunities for both established and emerging market participants.
Latest Developments
January 2025 - Wolfspeed, Inc.: The company expanded its SiC wafer production capacity to address rising demand from electric vehicle manufacturers and renewable energy applications. The expansion is expected to strengthen global supply availability and improve production scalability.
October 2024 - STMicroelectronics: The company introduced advanced automotive-grade SiC MOSFET solutions designed for next-generation EV platforms. The development supports higher power efficiency and faster charging performance in electric vehicles.
July 2024 - Infineon Technologies AG: Infineon announced investments in new SiC fabrication capabilities to enhance manufacturing capacity for industrial and automotive applications. The investment supports the company's long-term supply chain expansion strategy.
March 2024 - ON Semiconductor Corporation: The company expanded strategic partnerships with automotive OEMs for long-term SiC semiconductor supply agreements. The collaboration strengthens component availability for EV powertrain systems.
November 2023 - ROHM Co., Ltd.: ROHM launched next-generation SiC power modules optimized for industrial automation and renewable energy systems. The products focus on improving energy efficiency and reducing thermal losses.
August 2023 - Mitsubishi Electric Corporation: The company announced increased investments in advanced power semiconductor production facilities in Asia-Pacific. The initiative supports growing regional demand for EV and industrial power electronics.
May 2023 - Toshiba Corporation: Toshiba introduced new high-voltage SiC devices for fast-charging infrastructure and industrial motor control systems. The launch strengthens the company's position in high-efficiency power electronics applications.
February 2023 - European Union Semiconductor Initiative: European policymakers announced expanded semiconductor investment programs to strengthen regional manufacturing capabilities and reduce dependence on external supply chains. The initiative is expected to accelerate innovation and production capacity across Europe.
Explore additional market intelligence reports published by Data Bridge Market Research:
https://www.databridgemarketresearch.com/reports/global-elevator-market
https://www.databridgemarketresearch.com/reports/global-industrial-valves-market
https://www.databridgemarketresearch.com/reports/global-flavored-water-market
https://www.databridgemarketresearch.com/reports/global-building-automation-system-market
https://www.databridgemarketresearch.com/reports/middle-east-and-africa-industrial-valves-market
Contact Us:
Data Bridge Market Research
US: +1 614 591 3140
UK: +44 845 154 9652
APAC : +653 1251 975
Email:- corporatesales@databridgemarketresearch.com
About Data Bridge Market Research:
An absolute way to forecast what the future holds is to comprehend the trend today!
Data Bridge endeavors to provide appropriate solutions to the complex business challenges and initiates an effortless decision-making process. Data Bridge is an aftermath of sheer wisdom and experience which was formulated and framed in the year 2015 in Pune.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Can SiC Power Semiconductors Redefine the Future of Electric Vehicles and Energy Systems? here
News-ID: 4529936 • Views: …
More Releases from Data Bridge Market Research
Europe Epigenetics Diagnostic Market Size Projected to Hit USD 5.43 billion by 2 …
Market Summary
As per Data Bridge Market Research analysis, the Europe Epigenetics Diagnostic Market was estimated at USD 2.34 billion in 2025. The market is expected to grow from USD 2.08 billion in 2024 to USD 5.43 billion by 2032, at a CAGR of 12.70% during the forecast period driven by the rising demand for early-stage precision oncology, expanding utilization of non-invasive liquid biopsy platforms, increasing research investments in histone modification…
Age-Related Macular Degeneration (AMD) Anti-VEGF Therapeutics Market: Industry A …
Market Summary
As per Data Bridge Market Research analysis, the Age-Related Macular Degeneration (AMD) Disease - Anti-VEF Market was estimated at USD 15.59 billion in 2025. The market is expected to grow from USD 16.65 billion in 2026 to USD 24.71 billion in 2032, at a CAGR of 6.80% during the forecast period with driven by the rising demand for effective retinal disease therapies, increasing prevalence of age-related vision disorders, advancements…
Yogurt Powder Market Size Expected to Reach USD 1.41 Billion by 2032 at a CAGR o …
Market Summary
As per Data Bridge Market Research analysis, the Yogurt Powder Market was estimated at USD 0.28 billion in 2025. The market is expected to grow from USD 0.30 billion in 2026 to USD 1.41 billion in 2032, at a CAGR of 8.10% during the forecast period with driven by the rising demand for shelf-stable dairy ingredients, growing consumption of functional and protein-enriched foods, expansion of the food processing industry,…
Pressure Transmitter Market Size, Share & Industry Trends Analysis Report - Glob …
As per Data Bridge Market Research analysis, the Pressure Transmitter Market was estimated at USD 3.41 billion in 2025. The market is expected to grow from USD 3.54 billion in 2026 to USD 4.44 billion in 2032, at a CAGR of 3.86% during the forecast period (2026-2032), driven by the rising demand for industrial automation, increasing adoption of Industry 4.0 technologies, expansion of oil & gas and process industries, and…
More Releases for SiC
SiC Schottky Barrier Diodes (SiC SBD) Market Research Report
Global Info Research announces the release of the report "Global SiC Schottky Barrier Diodes (SiC SBD) Market 2025 by Manufacturers, Regions, Type and Application, Forecast to 2031" . The report is a detailed and comprehensive analysis presented by region and country, type and application. As the market is constantly changing, the report explores the competition, supply and demand trends, as well as key factors that contribute to its changing demands…
Global SiC MOSFETs Market
SiC MOSFETs Market Overview
Silicon carbide MOSFETs have the characteristics of low on-resistance and small switching losses, which can reduce device losses and improve system efficiency, and are more suitable for high-frequency circuits. It is widely used in the fields of new energy vehicle motor controller, vehicle power supply, solar inverter, charging pile, UPS, PFC power supply and other fields. This report provides a deep insight into the global SiC MOSFETs…
SIC Discrete Device Market
The "SIC Discrete Device Market" is expected to reach USD xx.x billion by 2031, indicating a compound annual growth rate (CAGR) of xx.x percent from 2024 to 2031. The market was valued at USD xx.x billion In 2023.
Growing Demand and Growth Potential in the Global SIC Discrete Device Market, 2024-2031
Verified Market Research's most recent report, "SIC Discrete Device Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2023-2030," provides…
SiC MOSFET and SiC SBD Market Analysis,Demand,Trends and Forecast 2029
Global Info Research announces the release of the report "Global SiC MOSFET and SiC SBD Market 2023 by Manufacturers, Regions, Type and Application, Forecast to 2029" . The report is a detailed and comprehensive analysis presented by region and country, type and application. As the market is constantly changing, the report explores the competition, supply and demand trends, as well as key factors that contribute to its changing demands across…
Global High Purity SiC Powder for SiC Single Crystal Market Insights, Forecast …
Global Info Research announces the release of the report "Global High Purity SiC Powder for SiC Single Crystal Market 2023 by Manufacturers, Regions, Type and Application, Forecast to 2029" . The report is a detailed and comprehensive analysis presented by region and country, type and application. As the market is constantly changing, the report explores the competition, supply and demand trends, as well as key factors that contribute to its changing demands across many markets. Company…
Latest Ceramic Matrix Composites Market by Matrix Type (C/C, C/Sic, Oxide/Oxide, …
The Ceramic Matrix Composites research report is valuable for every market enthusiast, stakeholder, policymaker, and market player. It offers vital information about the industry, including crucial facts, figures, expert opinions, and the latest developments across the globe. In addition, the Ceramic Matrix Composites research report provides data on the patterns and outcomes, target business sectors and materials, limits, and advancements.
Download FREE Sample Report @ https://www.reportsnreports.com/contacts/requestsample.aspx?name=319907
The ceramic matrix composites market…