


Press release
Ultra-thin Lenses Market: High-Index Materials, Premium Eyewear and Myopia Correction Support Global Growth, 2026-2032
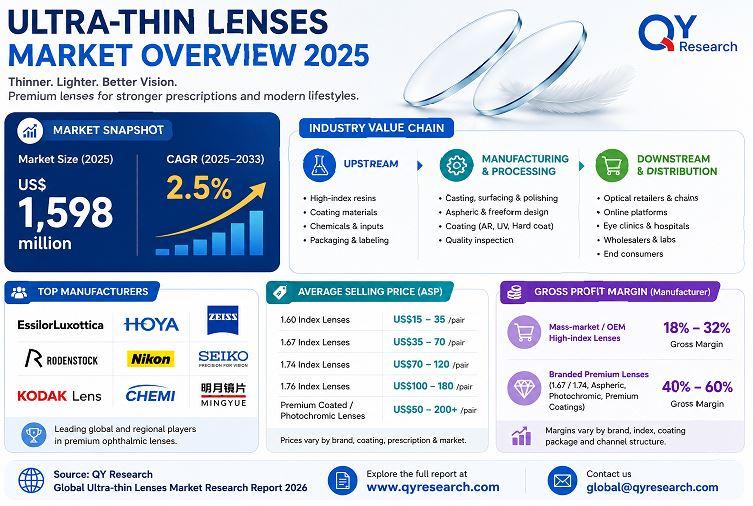
QY Research examines the Ultra-thin Lenses market, including high-index lens materials, manufacturer gross margin estimates, etc.
Ultra-thin lenses, also known as high-index prescription lenses, are optical lenses designed to reduce thickness and weight while maintaining the required corrective power for myopia, hyperopia, astigmatism and other refractive errors. The product category is especially important for consumers with stronger prescriptions because standard lenses can become thick, heavy and less attractive at higher diopter levels.
The market should be understood as the premium prescription lens segment associated with high-index materials, aspheric design, double-sided aspheric processing, lightweight optics, thin lens profiles and premium coating packages.
The global Ultra-thin Lenes market was valued at US$ 1671 million in 2025 and is anticipated to reach US$ 1981 million by 2032, at a CAGR of 2.5% from 2026 to 2032. The market is expected to continue growing as optical retailers, lens manufacturers and consumers increasingly emphasize comfort, appearance, optical clarity and customized eyewear. Demand is supported by rising myopia prevalence, premium eyewear consumption, digital freeform lens processing and the expansion of optical retail chains.
Manufacturer gross profit margin in the Ultra-thin Lenses market is estimated at approximately 25% to 55% depending on brand, refractive index, coating package and channel structure. Mass-market OEM high-index lenses may operate around 18% to 32% gross margin, while branded 1.67/1.74 lenses, double-sided aspheric lenses, photochromic lenses and premium coating packages may reach 40% to 60% manufacturer gross margin. Retail optical margins can be higher than manufacturer margins because fitting, prescription service and retail mark-up are added downstream.
Ultra-thin lenses are both medical correction products and lifestyle products. Consumers purchase them not only to see clearly but also to reduce edge thickness, improve comfort, select lighter frames and achieve better cosmetic appearance. This dual medical-consumer value makes the market attractive for lens manufacturers, optical retailers and eyewear brands.
Market Overview
The Ultra-thin Lenses market is part of the broader ophthalmic lens and prescription eyewear industry. Unlike standard plastic lenses, ultra-thin products use higher refractive index materials such as 1.60, 1.67, 1.70, 1.71, 1.74 and 1.76 index lenses. A higher refractive index allows the lens to bend light more efficiently, reducing the amount of material required to correct a given prescription. This produces thinner and lighter lenses, especially for strong prescriptions.
Market demand is shaped by both healthcare and consumer trends. On the healthcare side, uncorrected refractive error and myopia remain widespread global vision issues. On the consumer side, eyewear has become a fashion and lifestyle category. Consumers increasingly choose lens upgrades such as anti-reflective coatings, blue-light filtering, UV protection, scratch resistance, water repellency, dust resistance, photochromic functionality and digital freeform design.
The market is supported by premiumization. Optical retailers often use ultra-thin lenses as an upselling category because the value proposition is easy for consumers to understand: thinner appearance, lighter weight and better comfort. The benefit is most visible for consumers with strong myopia or hyperopia, where standard lenses can look bulky or distort the face through the lens edge.
Regional demand is strongest in urban markets, developed economies and higher-income consumer groups, but Asian manufacturers are improving affordability and expanding access to high-index products. China, Japan, South Korea and Southeast Asia are particularly important because of high myopia prevalence and growing consumer acceptance of premium eyewear.
The competitive landscape includes global ophthalmic lens groups, Japanese and Korean high-index specialists, Chinese lens manufacturers, eyewear retailers and material suppliers. Competition is based on optical clarity, coating durability, brand trust, prescription customization, retail channel strength and price positioning.
Industry Value Chain
Upstream Materials and Coating Inputs
• High-index resin monomers for 1.60, 1.67, 1.71, 1.74 and 1.76 lenses.
• Polycarbonate and specialty optical polymers.
• Photochromic materials, UV absorbers and blue-light filtering additives.
• Hard-coat chemicals, anti-reflective coating layers and hydrophobic top coats.
• Mold materials, casting chemicals, tinting materials and cleaning solutions.
• Packaging, lens envelopes, verification labels and traceability systems.
Midstream Lens Manufacturing and Processing
• Lens casting, curing, surfacing, edging, polishing and inspection.
• Aspheric, double-sided aspheric and digital freeform design processing.
• Coating application, including hard coating, AR coating, UV protection and water-repellent layers.
• Quality control for optical power, prism, center thickness, Abbe value, coating adhesion and cosmetic defects.
• OEM production for optical chains, eyewear brands and private-label distributors.
Downstream Sales and Distribution
• Optical retail chains and independent opticians.
• Online eyewear platforms and direct-to-consumer brands.
• Hospitals, eye clinics and optometry practices.
• Eyewear wholesalers and lens laboratories.
• Fashion eyewear brands bundling premium lenses with frames.
• Consumers with strong prescriptions, premium eyewear preferences or lightweight comfort needs.
Major Market Participants
The Ultra-thin Lenses market is served by global ophthalmic lens companies, Japanese and Korean high-index lens specialists, Chinese optical lens manufacturers, eyewear retailers and lens material suppliers.
Major market participants and relevant industry companies include:
• EssilorLuxottica
• HOYA Corporation
• Carl Zeiss Vision
• Nikon-Essilor
• Tokai Optical
• Seiko Optical Products
• Rodenstock
• Shamir Optical Industry
• Mitsui Chemicals
• Thai Optical Group
• Wanxin Optical
• Mingyue Optical Lens
• Jiangsu Conant Optical
• Shanghai Conant Optical
• Chemi Lens
• KODAK Lens
• Younger Optics
• Zhenjiang Ideal Optical
• JINS Holdings
• OWNDAYS
• LensCrafters
• Fielmann Group
• Specsavers
• Vision Express
• Safilo Group
• Luxottica Retail
• Bausch + Lomb
• CooperVision
• GKB Opticals
• Asia Optical
Global lens leaders such as EssilorLuxottica, HOYA, Carl Zeiss Vision, Nikon-Essilor and Rodenstock compete through optical technology, premium coatings, prescription customization, brand recognition and professional optical retail relationships. Japanese companies such as Tokai Optical and Seiko Optical are associated with high-index and premium lens technology, while Chinese manufacturers such as Wanxin, Mingyue and Conant support large-scale production and cost-efficient supply.
Retailers and optical chains influence demand because ultra-thin lenses are often sold through recommendation and fitting consultation. The retail channel plays a major role in educating consumers about index selection, lens thickness, coating upgrades and frame compatibility.
Product Types and Estimated Pricing
Pricing below is an indicative market-level estimate based on publicly observed product positioning, typical B2B quotation logic and comparable component pricing. Actual selling prices vary by specification, order volume, certification, brand, region, project size and service scope.
1.60 Index Thin Lenses
1.60 index lenses are entry-level high-index lenses suitable for moderate prescriptions. They are thinner than standard CR-39 lenses and provide a balance between price, optical clarity and comfort.
• Estimated price range: Estimated manufacturer selling price: US$5-18 per pair for basic uncoated or standard coated OEM lenses; branded retail prices are substantially higher.
• Good option for moderate myopia and daily eyewear.
• Often bundled with anti-reflective and UV coatings.
• Estimated manufacturer gross margin: 20%-35%.
1.67 Index Ultra-thin Lenses
1.67 index lenses are widely used for stronger prescriptions and are one of the mainstream premium thin-lens categories. They provide a noticeable reduction in thickness while remaining more affordable than 1.74 or 1.76 products.
• Estimated price range: Estimated manufacturer selling price: US$12-45 per pair depending on coating and volume.
• Popular upgrade option in optical retail.
• Suitable for stronger myopia or hyperopia.
• Estimated manufacturer gross margin: 28%-45%.
1.74 / 1.76 High-Index Ultra-thin Lenses
1.74 and 1.76 lenses are premium high-index products designed for strong prescriptions where thickness reduction is a major purchasing factor. They are often sold with advanced coatings and aspheric designs.
• Estimated price range: Estimated manufacturer selling price: US$35-120+ per pair depending on brand, material and coating package.
• Premium category for strong prescriptions.
• Higher material and processing cost but stronger value-added pricing.
• Estimated manufacturer gross margin: 40%-60%.
Aspheric and Double-Sided Aspheric Ultra-thin Lenses
Aspheric and double-sided aspheric lenses use advanced surface design to reduce distortion, improve appearance and make lenses flatter and thinner. They are often marketed as premium comfort and cosmetic lenses.
• Estimated price range: Estimated manufacturer selling price: US$20-150+ per pair depending on index, coating and customization.
• Improves cosmetic appearance and peripheral optical performance.
• Requires more advanced design and processing capability.
• Estimated manufacturer gross margin: 35%-55%.
Photochromic, Blue-Light and Premium Coated Ultra-thin Lenses
These lenses combine high-index thin profiles with functional coatings or materials such as photochromic darkening, blue-light filtering, anti-reflective coating, UV protection and hydrophobic layers.
• Estimated price range: Estimated manufacturer selling price: US$25-200+ per pair depending on function and brand.
• High upselling value for retailers.
• Combines optical correction with lifestyle and comfort features.
• Estimated manufacturer gross margin: 40%-60%.
Classification by Application and Product Positioning
By Refractive Index
Ultra-thin lenses are primarily classified by refractive index. Higher index lenses are thinner for the same prescription but generally cost more and may require stronger coating performance to maintain optical comfort.
• Estimated price / commercial range: 1.60: US$5-18/pair; 1.67: US$12-45/pair; 1.74/1.76: US$35-120+/pair.
• Index choice depends on prescription strength, frame selection and budget.
• Higher index products are more premium and margin-rich.
• Retailers often recommend index upgrades for strong prescriptions.
By Lens Design
Design types include spherical, aspheric, double-sided aspheric, digital freeform and progressive designs. More advanced designs improve comfort and appearance but require higher processing capability.
• Estimated price / commercial range: Standard high-index: US$5-45/pair; customized digital/freeform: US$50-200+/pair.
• Aspheric designs reduce edge thickness and distortion.
• Progressive and freeform products command higher prices.
• Design differentiation supports premium positioning.
By Coating Package
Coating packages include hard coating, anti-reflective coating, blue-light filtering, UV protection, hydrophobic coating, oleophobic coating and photochromic layers. Coatings strongly influence final price and gross margin.
• Estimated price / commercial range: Basic coating: +US$2-10/pair; premium coating package: +US$10-80+/pair at manufacturer level.
• Coating performance affects scratch resistance, clarity and consumer satisfaction.
• Premium coatings are a major source of value-added margin.
• Coating durability is a key brand differentiator.
End-Use Applications
Strong Myopia and Hyperopia Correction
Ultra-thin lenses are most relevant for consumers with stronger prescriptions because lens thickness becomes more visible and uncomfortable at higher diopters. High-index materials reduce edge thickness and improve frame compatibility.
This application is the core driver of the market because the functional benefit is clear and easy for optical retailers to communicate.
Premium Fashion Eyewear
Consumers increasingly view eyewear as part of personal style. Ultra-thin lenses allow people with strong prescriptions to choose lighter, thinner and more fashionable frames without excessive lens edge thickness.
Demand is supported by urban consumers, premium optical chains, designer frames and social preference for better-looking eyewear.
Office, Digital and Daily Wear
Many consumers use premium lenses for daily work, screen exposure and long wearing hours. Thin, lightweight lenses with anti-reflective, blue-light and UV coatings improve comfort and perceived product value.
This creates opportunities for bundled packages that combine high-index materials with functional coatings.
Online and Retail Optical Channels
Online eyewear platforms and optical chains use high-index lenses as an upgrade option during checkout or consultation. Retail education, fitting accuracy and frame recommendation influence conversion to premium lenses.
Because consumers may not understand index differences, retailer recommendation plays a major role in market adoption.
Technology Trends
• Rising adoption of 1.67, 1.74 and 1.76 high-index lens materials.
• Growth of aspheric and double-sided aspheric designs for thinner profiles and better appearance.
• Expansion of premium coating packages, including AR, blue-light, UV and hydrophobic coatings.
• Digital freeform surfacing and personalized prescription optimization.
• Increasing consumer willingness to pay for lightweight and aesthetically attractive eyewear.
• Growth of Asian manufacturing capacity improving affordability of high-index lenses.
Market Challenges
• High-index materials increase cost and may limit adoption among price-sensitive consumers.
• Higher index lenses can require better coatings to manage reflection and optical comfort.
• Consumers may not understand the difference between index levels without professional explanation.
• Online eyewear channels must manage fitting accuracy and frame compatibility.
• Competition from low-cost manufacturers can pressure OEM pricing.
Strategic Outlook
The Ultra-thin Lenses market is expected to benefit from the long-term growth of myopia correction, premium eyewear consumption and high-index material adoption. The most attractive margin opportunities will remain in 1.67-and-above lenses, double-sided aspheric designs, photochromic products and premium coating packages. Manufacturers that can combine optical clarity, consistent coating quality, OEM scalability and strong retail partnerships will be better positioned. The market will continue to sit between healthcare necessity and lifestyle-driven premiumization, creating room for both global brands and cost-efficient Asian suppliers.
Report Coverage
This report is designed for ophthalmic lens manufacturers, optical retailers, eyewear brands, material suppliers, investors and strategy teams that need to evaluate product demand, competitive positioning, pricing logic, regional opportunities and technology trends in the Ultra-thin Lenses market.
The full QY Research report covers market definition, product segmentation, major participants, applications, technology trends, regional demand and commercial considerations.
Report Link: https://www.qyresearch.com/reports/6532356/ultra-thin-lenes
Contact Information:
Tel: +1 626 2952 442 (US); +86-1082945717 (China); +84 865 216594 (Vietnam)
Email: global@qyresearch.com; tranlethanhhang@qyresearch.com
Website: www.qyresearch.com
Address: Room 2905, Vili International, 167 Linhe West Road, Tianhe District, Guangzhou, Guangdong Province, China
About QY Research
QY Research has established close partnerships with over 71,000 global leading players. With more than 20,000 industry experts worldwide, we maintain a strong global network to efficiently gather insights and raw data. Our 36-step verification system ensures the reliability and quality of our data. With over 2 million reports, we have become the world's largest market report vendor. Our global database spans more than 2,000 sources and covers data from most countries, including import and export details. We have partners in over 160 countries, providing comprehensive coverage of both sales and research networks. A 90% client return rate and long-term cooperation with key partners demonstrate the high level of service and quality QY Research delivery. More than 30 IPOs and over 5,000 global media outlets and major corporations have used our data, solidifying QY Research as a global leader in data supply. We are committed to delivering services that exceed both client and societal expectations.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Ultra-thin Lenses Market: High-Index Materials, Premium Eyewear and Myopia Correction Support Global Growth, 2026-2032 here
News-ID: 4519672 • Views: …
More Releases from QY Research
Global Clay Ventilation Block Market: Opportunities for Manufacturers, Exporters …
Executive Investment Snapshot
Clay ventilation blocks are not a new invention. They are one of the oldest ways to make walls breathe. What is changing is the commercial logic around them. As cities face hotter summers, higher cooling loads, tighter carbon expectations and stronger demand for distinctive architectural facades, the product is moving from a low-cost decorative masonry item toward a passive design component that can support shading, airflow, thermal comfort…
Green Building Materials Market Surges as Construction Shifts from ESG to Cost a …
Executive Summary: The Construction Industry's New Pressure Point
Construction is under pressure from several directions at once. Developers are facing higher material costs, rising energy expenses, stricter building codes, investor ESG requirements and growing concern about climate resilience. At the same time, building owners want healthier indoor environments, lower operating costs and more efficient envelopes that can reduce cooling and heating demand.
This is why green building materials are moving from a…
Indonesia Wrinkle Release Spray Market (2024 Onward): Economic and Regulatory Op …
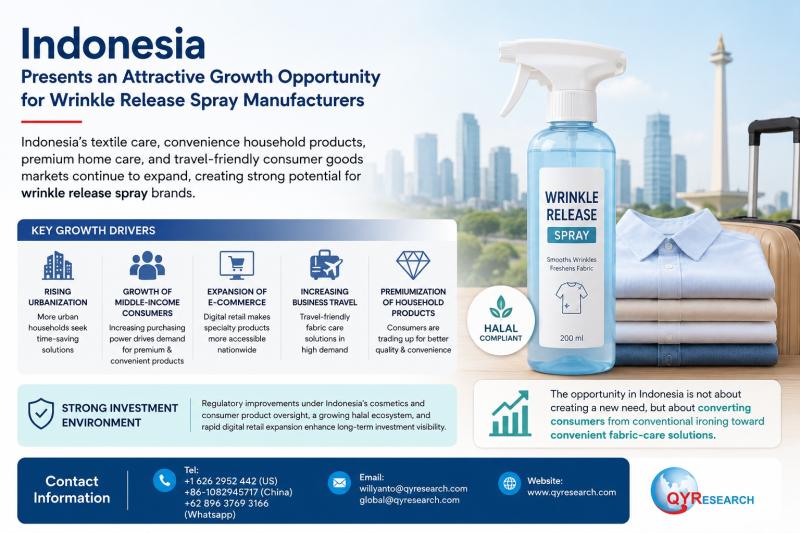
Indonesia presents an attractive growth opportunity for wrinkle release spray manufacturers as the country's textile care, convenience household products, premium home care, and travel-friendly consumer goods markets continue to expand. Although wrinkle release spray remains a niche category compared with traditional fabric softeners or ironing aids, several structural trends including rising urbanization, growth of middle-income consumers, expansion of e-commerce, increasing business travel, and premiumization of household products to create favorable…
Premium Kitchen Appliances Drive the Next Expansion Cycle for Stainless Steel El …
The global Stainless Steel Automatic Electric Can Opener market is entering a non-linear value inflection where future value creation depends less on shipment expansion and increasingly on premium hardware integration, higher-quality stainless steel construction, ergonomic engineering, food-safe certifications, and automated manufacturing efficiency. Historically, manufacturers competed primarily through low-cost production and retail distribution. That competitive model is gradually giving way to capital-intensive manufacturing requiring precision motor assembly, long-life gearbox systems, improved…
More Releases for Lens
Lens Market
The "Lens Market" is expected to reach USD xx.x billion by 2031, indicating a compound annual growth rate (CAGR) of xx.x percent from 2024 to 2031. The market was valued at USD xx.x billion In 2023.
Growing Demand and Growth Potential in the Global Lens Market, 2024-2031
Verified Market Research's most recent report, "Lens Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2023-2030," provides an in-depth examination of the industry…
Infrared Lens (IR Lens) Market Size 2024 to 2031.
Market Overview and Report Coverage
An Infrared Lens (IR Lens) is a type of lens designed specifically for infrared imaging applications, allowing infrared radiation to pass through while blocking visible light. These lenses are commonly used in various industries such as automotive, military and defense, surveillance, and healthcare.
The current outlook for the Infrared Lens (IR Lens) Market is positive, with a growing demand for IR lenses in the expanding…
Global Lens Cleaner Market, Global Lens Cleaner Industry, Covid-19 Impact Global …
Lens cleaner is used to disinfect eyeglass lenses, contact lenses, and digital camera lenses. It plays a significant role in improving the hygiene & safety of the contact lenses. It is highly preferred for spectacle & contact lens cleaning. On the other hand, wipes and tissues for cleaning digital cameras are most preferred. The wipes are available in wet or dry form depending on the needs of the end user.…
Global Lens Cloth Market, Global Lens Cloth Industry, Covid-19 Impact Global Len …
Lens cloth is special type of cleaning cloth, which is generally made from different fabrics. This type of cloth can be micro-fiber cloth or wet wipes that depend on the lens to be cleaned. It helps remove dirt and grease particles that stick to the lens in daily use. Cleaning the lens helps to preserve the life of expensive lenses and prevents scratches on the lens surface. Microfiber lens cloths…
Infrared Lens (IR Lens) Market: Competitive Dynamics & Global Outlook 2026
Market Research Report Store offers a latest published report on Infrared Lens (IR Lens) Market Analysis and Forecast 2019-2025 delivering key insights and providing a competitive advantage to clients through a detailed report.
This intelligence Infrared Lens (IR Lens) Market report by Market Research Report Store includes investigations based on the current scenarios, historical records, and future predictions. An accurate data of various aspects such as type, size, application, and end…
Soft Contact Lens Market | Daily Wear Contacts Lens, Extended Wear Contacts Lens …
Soft contact lens are used to correct the vision of the eye. These lenses are made of soft water absorbing flexible and translucent polymers (hydrogels) and a high amount of plasticizer. These are more flexible than the hard contact lens and can be easily molded into the desired shapes. Soft contact lens fit easily to the eyeball compared to a rigid gas-permeable lens and provides comfort. Most contact lens patients…

