


Press release
Green Cement Manufacturing Plant DPR & Unit Setup - 2026: Demand Analysis and Project Cost
Market Overview and Growth Potential
The global green cement market demonstrates exceptional growth trajectory, valued at USD 42.57 Billion in 2025. According to IMARC Group's comprehensive market analysis, the market is projected to reach USD 112.45 Billion by 2034, exhibiting a robust CAGR of 10.2% from 2026-2034. This extraordinary expansion is driven by tightening carbon emission regulations and mandatory low-carbon procurement rules in government infrastructure spending creating structural demand for green cement alternatives to ordinary Portland cement, widespread adoption of supplementary cementitious materials including fly ash and slag reducing clinker content by 20-60%, the rapid maturation of LC3 limestone calcined clay cement technology capable of reducing CO2 emissions by up to 40% while leveraging geographically widespread clay resources, surging ESG-linked construction financing rewarding certified low-carbon building material choices, and the accelerating emergence of geopolymer and carbon-negative cement technologies storing CO2 during production for zero or net-negative embodied carbon outcomes.
Request for a Sample Report: https://www.imarcgroup.com/green-cement-manufacturing-plant-project-report/requestsample
Green cement encompasses a broad family of low-carbon and environmentally optimized cement formulations that achieve significant reductions in CO2 emissions per tonne of cementitious product compared to ordinary Portland cement (OPC), which emits approximately 0.82-0.89 tonnes of CO2 per tonne of clinker produced. The commercial product range includes fly ash-based cement-commanding the largest market share at 41.3% in 2025-produced by replacing 20-40% of clinker with coal combustion fly ash pozzolan meeting ASTM C618 and EU EN 450 specifications; slag-based cement incorporating ground granulated blast furnace slag at 22.1% market share for superior long-term strength and marine application; limestone calcined clay cement (LC3) replacing 45-55% of clinker with calcined clay and limestone; geopolymer cement using entirely industrial by-product binders including fly ash and slag activated by alkaline solutions eliminating Portland clinker entirely; silica fume-enhanced ultra-high performance concrete with sub-10% CO2 intensity; and emerging carbon-negative cement technologies including CarbonCure's concrete carbon mineralization and Calfrac's carbon-absorbing curing systems.
The green cement market is witnessing exceptional demand growth due to the global construction industry's accelerating response to climate change requiring embodied carbon reduction in building materials, the increasing deployment of carbon pricing mechanisms making conventional high-clinker cement progressively more costly to produce and procure, and the mainstream adoption of green building certification programs including LEED, BREEAM, Green Star, and GRIHA that mandate or strongly incentivize low-carbon cement use. According to the Economic Survey 2024-25, India's green cement sector is experiencing significant momentum through initiatives including the Confederation of Indian Industry-Green Business Centre collaboration with the Cement Manufacturers Association for Green Cementech 2025 held in Hyderabad in May 2025 under the theme 'Road towards Net Zero Carbon', reflecting the Indian cement industry's accelerating transition toward net-zero production and the government's growing policy emphasis on sustainable construction materials in public infrastructure programs. Government-led green building mandate programs and sustainable infrastructure investment further strengthen market prospects.
Plant Capacity and Production Scale
The proposed green cement manufacturing facility is designed with an annual production capacity ranging between 200,000 - 500,000 MT, enabling economies of scale while maintaining operational flexibility. This capacity range allows manufacturers to cater to diverse market segments-from fly ash-based blended cement for mass-market residential construction supply to slag-based cement for marine, infrastructure, and heavy civil engineering applications, LC3 limestone calcined clay cement for markets with abundant clay resources and limited fly ash availability, geopolymer concrete products for commercial and industrial building construction, ultra-high performance green concrete for bridges and specialized structural applications, and carbon-certified and EPD-documented green cement for ESG-committed developer and green building certification project supply-ensuring steady demand and consistent revenue streams across residential, commercial, and infrastructure construction verticals.
Ask Analyst for Customization:
https://www.imarcgroup.com/request?type=report&id=7568&flag=C
Financial Viability and Profitability Analysis
The green cement manufacturing business demonstrates healthy profitability potential under normal operating conditions. The financial projections reveal:
• Gross Profit Margins: 30-40%
• Net Profit Margins: 12-18%
These margins are supported by stable and exceptionally growing demand across residential, commercial, and infrastructure construction sectors, value-added low-carbon certified, EPD-documented, and LEED-compliant product positioning enabling pricing premiums of 8-25% above conventional OPC while simultaneously offering cost advantages through reduced clinker content and industrial by-product material utilization, and the regulatory tailwind of carbon pricing that progressively penalizes conventional cement economics while improving green cement's competitive position. The project demonstrates strong return on investment (ROI) potential, particularly for producers with direct access to industrial by-product fly ash and slag feedstocks and established supply relationships with green-committed construction developers and government procurement programs.
Operating Cost Structure
Understanding the operating expenditure (OpEx) is crucial for effective financial planning and cost management. The cost structure for a green cement manufacturing plant is primarily driven by:
• Raw Materials: 50-60% of total OpEx
• Utilities: 20-25% of OpEx
Raw materials for green cement manufacturing differ fundamentally from conventional OPC in their lower clinker content and higher supplementary cementitious material proportions-with fly ash, ground granulated blast furnace slag, calcined clay, limestone powder, and silica fume sourced as industrial by-products at significantly lower cost than clinker, providing a structural raw material cost advantage over conventional cement. Utilities represent the second-largest cost component, reflecting the thermal energy requirements of reduced-scale clinker kiln operations, calcined clay calcination, and grinding mill operations, where the lower clinker-to-cement ratio intrinsically reduces specific energy consumption per tonne of finished product. Securing long-term supply agreements for fly ash from power plants and slag from steel mills at competitive by-product pricing, and maximizing mill efficiency in grinding blended cement formulations, are the most critical cost management strategies.
Capital Investment Requirements
Setting up a green cement manufacturing plant requires substantial capital investment across several critical categories:
Land and Site Development: Selection of an optimal location with strategic proximity to industrial by-product feedstock supply sources-power plant fly ash, steel mill slag, and limestone quarries-and logistics connectivity to construction material distribution networks, ready-mix concrete plants, and precast concrete manufacturers. Proximity to major urban construction markets minimizes distribution costs and enables timely delivery to time-sensitive construction project supply chains. The site must have robust transportation infrastructure, utilities, and environmental compliance systems for cement plant dust, noise, and wastewater management.
Machinery and Equipment: The largest portion of capital expenditure (CapEx) covers specialized grinding, blending, calcination, and quality assurance equipment essential for green cement production.
Key machinery includes:
• Vertical roller mills and horizontal ball mills for grinding clinker, slag, fly ash, and limestone to target fineness specifications
• Rotary kilns and flash calciners for calcining clay at 700-850°C to produce reactive metakaolin for LC3 cement production
• Proportioning and blending systems for precise multi-component supplementary cementitious material dosing and homogenization
• Fly ash processing and classification equipment for conditioning and standardizing received industrial fly ash to product specification
• Slag drying and granulation systems for processing wet blast furnace slag into ground granulated blast furnace slag (GGBS)
• Carbon capture and mineralization systems for injecting CO2 into concrete mix water to permanently mineralize carbon as calcium carbonate within concrete
• Quality control laboratory with XRF elemental analysis, particle size analysis, and compressive strength testing capability
• Automated packing lines and bulk loading systems for bagged and bulk green cement dispatch to construction supply channels
Civil Works: Industrial cement plant construction with dust control, noise abatement, and environmental management infrastructure meeting pollution control standards. The layout should incorporate raw material receiving and stockpiles for fly ash, slag, clinker, and clay, pre-processing and drying section, grinding mill hall, blending and homogenization silos, calciner and kiln section for LC3 production, quality control and testing laboratory, finished cement storage silos, bulk loading and bagging dispatch section, environmental control systems including bag filters and electrostatic precipitators, utility block, and administrative offices.
Buy now: https://www.imarcgroup.com/checkout?id=7568&method=2175
Other Capital Costs: Pre-operative expenses, equipment installation and commissioning costs, BIS certification for cement grades including IS 455 Portland slag cement and IS 1489 Portland pozzolana cement, environmental clearance and consent to operate, ISO 14001 environmental management system certification, third-party Environmental Product Declaration (EPD) preparation and verification, green building program material certification, initial fly ash and slag procurement working capital, and contingency provisions for blend optimization and strength development qualification during plant establishment.
Major Applications and Market Segments
Green cement products find extensive applications across diverse construction market segments, demonstrating their growing role as the primary low-carbon building material enabling sustainable infrastructure development globally:
Residential Construction: Largest application segment at 43.2% of market demand in 2025, where fly ash-based and slag-based green cement is used in foundations, structural columns, slabs, and masonry construction of single-family homes, apartment buildings, and housing complexes, with green building certification programs including LEED for Homes and GRIHA promoting low-carbon cement adoption in residential projects, and government affordable housing programs increasingly specifying sustainable construction materials.
Infrastructure and Civil Engineering: High-volume application where slag-based cement with superior sulfate resistance, reduced heat of hydration, and long-term strength development is the preferred binder for bridges, tunnels, marine structures, water treatment plants, dams, and mass concrete applications where conventional Portland cement's high heat of hydration creates cracking risk and durability concerns, with global infrastructure investment programs mandating or incentivizing low-embodied-carbon materials under Buy Clean and Environmental Product Declaration policy frameworks.
Commercial and Industrial Buildings: Growing application where ESG-committed commercial real estate developers, corporate occupier sustainability programs, and institutional investors increasingly require third-party verified low-carbon building materials including green cement with Environmental Product Declarations to achieve LEED Platinum, BREEAM Outstanding, and net-zero embodied carbon building certifications that command premium rents, higher asset valuations, and access to green mortgage and sustainability-linked loan financing.
Precast Concrete Manufacturing: Specialized application where green cement formulations including ultra-high performance concrete with silica fume, slag-based cement, and fly ash concrete are used in precast concrete panels, hollow core slabs, structural elements, and architectural cladding manufactured under factory-controlled conditions, with precast producers' ability to precisely control curing conditions enabling optimal performance from supplementary cementitious material-rich green cement mixes.
Ready-Mix Concrete and Specialty Applications: Large-volume channel where ready-mix concrete producers incorporate green cement and supplementary cementitious materials including fly ash and GGBS directly into concrete mixes for delivery to construction sites, alongside specialty applications in oil well cementing, mine backfill, and soil stabilization where geopolymer and alkali-activated cement systems offer superior performance in aggressive chemical environments compared to conventional OPC.
Why Invest in Green Cement Manufacturing?
Decarbonization Regulatory Megatrend: The global construction industry's mandatory decarbonization under national carbon pricing, net-zero building codes, Buy Clean government procurement mandates, and EU Taxonomy-aligned sustainable finance requirements is creating an irreversible structural demand shift toward green cement that accelerates with every tightening of carbon pricing and green procurement regulation, providing green cement manufacturers with a regulatory-protected competitive advantage that grows stronger as conventional clinker-intensive cement faces progressively higher carbon costs.
10.09% CAGR Exceptional Growth Rate: The green cement market's extraordinary CAGR of 10.09% through 2034-more than twice the overall global cement market growth rate of 5.20%-reflects a fundamental and accelerating market share shift from conventional OPC to green alternatives driven by carbon regulation, ESG investment mandates, and technology advancement, providing green cement producers with volume growth and pricing power dynamics unavailable in the mature conventional cement market.
Industrial By-Product Cost Advantage: Green cement producers incorporating fly ash from coal power plants and ground granulated blast furnace slag from steel mills source primary raw material components as industrial by-product waste streams at costs of USD 15-40 per tonne-compared to USD 60-90 per tonne for Portland clinker production-creating a systematic and structurally durable raw material cost advantage that improves both production economics and the carbon footprint of the finished product simultaneously.
LC3 Technology India Advantage: Limestone calcined clay cement (LC3) technology-capable of reducing cement CO2 intensity by up to 40% using low-grade kaolinitic clay abundantly available across India, Africa, and Latin America where fly ash and slag availability is limited-provides Indian green cement manufacturers with a technically proven, domestically resourced, and cost-competitive low-carbon cement pathway that does not depend on power plant or steel mill by-product proximity, enabling green cement production in geographies currently underserved by fly ash or slag-based products.
Government Support: Government-led green building mandate programs under the Bureau of Energy Efficiency's Star Rating and GRIHA certification systems, National Action Plan on Climate Change construction sector decarbonization targets, BIS standards for Portland pozzolana and Portland slag cement enabling domestic green cement quality assurance, smart cities program sustainable material procurement policies, and CII-Green Business Centre industry collaboration initiatives such as Green Cementech 2025 further strengthen market prospects and directly support green cement manufacturing investment.
Import Substitution Opportunities: India's green cement market is currently dominated by the blended cement products of established players including UltraTech, ACC, and Ambuja which command significant market positions, with the rapid expansion of India's green building and sustainable infrastructure sectors creating growing demand for new entrants offering differentiated LC3, geopolymer, and carbon-certified green cement products supported by Environmental Product Declarations, third-party carbon verification, and green building program compliance documentation that enables access to ESG-committed premium construction market segments.
Manufacturing Process Excellence
The green cement manufacturing process involves several precision-controlled stages:
• Raw Material Sourcing and Quality Assessment: Fly ash, ground granulated blast furnace slag, limestone, and clay raw materials are received from power plants, steel mills, and quarries, sampled for chemical composition by X-ray fluorescence, pozzolanic activity index, and physical properties including fineness and specific gravity, and approved or rejected against incoming material specifications before stockpiling
• Supplementary Material Pre-processing: Fly ash is classified and beneficiated to remove carbon and coarse particles to target fineness; slag is dried and granulated or receives supplementary grinding; and clay is crushed, dried, and calcined in flash calciners or rotary kilns at 700-850°C to dehydroxylate kaolinite and produce highly reactive metakaolin for LC3 cement production
• Clinker and SCM Grinding: Portland clinker-at a significantly reduced proportion of 40-60% versus 90-95% in OPC-and supplementary cementitious materials are co-ground or separately ground in vertical roller mills or ball mills to target Blaine fineness, with separate grinding enabling optimization of each component's particle size distribution for maximum pozzolanic reactivity and strength development
• Blend Formulation and Proportioning: Ground clinker and supplementary cementitious materials are precisely proportioned using automated weigh feeders and blended in homogenization silos to achieve target chemical composition, clinker factor, and physical properties meeting BIS, EN, or ASTM green cement grade specifications for fly ash cement, slag cement, or LC3 cement
• Carbon Integration: For carbon-capturing green cement production, CO2 is injected into the cement production process stream or concrete mix water using CarbonCure-type mineralization technology, permanently mineralizing carbon dioxide as calcium carbonate within the cement matrix and contributing to net CO2 reduction in the product's embodied carbon footprint
• Quality Testing and EPD Documentation: Each cement lot is tested for chemical composition, specific surface area, setting time, soundness, and compressive strength at 3, 7, and 28 days before dispatch, with third-party verified Environmental Product Declarations documenting the batch-specific CO2 emission factor per tonne for green building certification project compliance
• Packaging and Dispatch: Quality-released green cement is filled into 50 kg bags with green cement grade identification and EPD reference coding, or dispatched in bulk tankers to ready-mix concrete plants, precast manufacturers, and construction project batching plants with carbon performance certificates and green building material compliance documentation
Industry Leadership
The global green cement manufacturing industry is led by established construction materials companies and innovative low-carbon cement technology pioneers with extensive production capabilities and strong sustainable construction customer relationships. Key industry players include:
• ACC Ltd.
• CeraTech
• CRH plc
• CEMEX S.A.B. de C.V.
• LafargeHolcim Ltd
These companies serve diverse end-use sectors including residential construction, infrastructure and civil engineering, commercial and industrial buildings, precast concrete manufacturing, and ready-mix concrete and specialty applications, demonstrating the broad and accelerating commercial applicability of green cement products across the full spectrum of global construction, infrastructure, and sustainable building development.
Browse Full Report: https://www.imarcgroup.com/green-cement-manufacturing-plant-project-report
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company excel in understanding its client's business priorities and delivering tailored solutions that drive meaningful outcomes. We provide a comprehensive suite of market entry and expansion services. Our offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape, and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No:(D) +91 120 433 0800
United States: (+1-201971-6302)
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Green Cement Manufacturing Plant DPR & Unit Setup - 2026: Demand Analysis and Project Cost here
News-ID: 4513191 • Views: …
More Releases from IMARC Group
Brazil Corporate Wellness Market Size to Reach USD 2.7 Billion by 2034, Exhibiti …
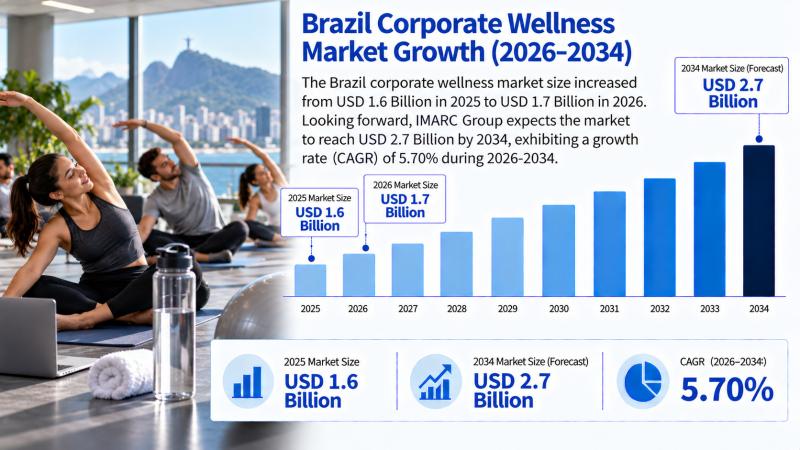
Brazil Corporate Wellness Market Report 2026
Market Size in 2025: USD 1.6 Billion
Market Size in 2026: USD 1.7 Billion
Market Forecast in 2034: USD 2.7 Billion
Market Growth Rate: 5.70% (2026-2034)
According to the latest report by IMARC Group, titled "Brazil Corporate Wellness Market: Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034," the Brazil corporate wellness market grew from USD 1.6 Billion in 2025 to USD 1.7 Billion in 2026. Looking forward, the…
R-PET Prices Show Significant Regional Variation in Q2 2026 Across Major Global …
R-PET Prices Q2 2026
The global recycled polyethylene terephthalate (R-PET) market displayed varied pricing conditions across major consuming regions during the second quarter of 2026. Germany recorded the highest assessed price among the covered markets, while Japan registered the lowest. The United States and China maintained comparatively elevated price levels, whereas Saudi Arabia remained at a lower regional benchmark. These differences reflected variations in recycled feedstock availability, collection efficiency, downstream packaging…
United States Pest Control Market Size, Share & Industry Trends Report 2034
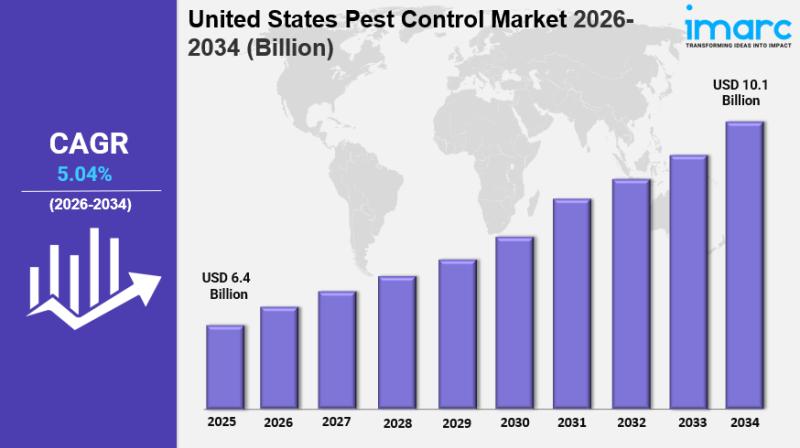
IMARC Group has recently released a new research study titled "United States Pest Control Market Size, Share, Trends and Forecast by Pest Type, Control Method, Application and Region, 2026-2034," offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.
United States Pest Control Market Outlook 2026-2034: Trends, Opportunities and Strategic Insights
The United States pest control market size was…
India Sodium Sulphate Prices Shift in 2026: What the Latest Price Data Reveals
Sodium Sulphate Prices in India are being shaped in 2026 by a combination of downstream demand, supply availability, production economics and regional logistics. In the Q2 2026 pricing data, Sodium Sulphate was assessed at USD 225/MT in the USA, USD 116/MT in Japan, USD 241/MT in Brazil, USD 115/MT in Indonesia and USD 223/MT in Canada. The wide regional spread highlights the importance of local supply structures and freight costs…
More Releases for Green
Green-Card.md Simplifies Green Card Application Process
Image: https://www.getnews.info/wp-content/uploads/2024/07/1722343980.png
Green-Card.md is a premier immigration consultancy firm. Specializing in green card applications, the company offers a wide range of services designed to assist individuals in obtaining permanent residency in the United States. With a commitment to personalized service and expert guidance, Green-Card.md is dedicated to helping clients achieve their immigration goals.
Green-Card.md, a leading immigration consultancy firm, is excited to announce its dedicated services aimed at assisting individuals in obtaining…
Green Logistics Market Is Flourishing worldwide with DHL, Green India Transport, …
Green logistics describes all attempts to measure and minimize the ecological impact of logistics activities. This includes all activities of the forward and reverse flows of products, information and services between the point of origin and the point of consumption. It is the aim to create a sustainable company value using a balance of economic and environmental efficiency. Green logistics has its origin in the mid-1980s and was a concept…
Green Logistics Market Is Thriving with DHL, Green India Transport, The Green Gr …
Green logistics describes all attempts to measure and minimize the ecological impact of logistics activities. This includes all activities of the forward and reverse flows of products, information and services between the point of origin and the point of consumption. It is the aim to create a sustainable company value using a balance of economic and environmental efficiency. Green logistics has its origin in the mid-1980s and was a concept…
Global Indocyanine Green Market 2019 - Diagnostic Green, Akorn
Apex Market Research, recently published a detailed market research study focused on the "Indocyanine Green Market" across the global, regional and country level. The report provides 360° analysis of "Indocyanine Green Market" from view of manufacturers, regions, product types and end industries. The research report analyses and provides the historical data along with current performance of the global Indocyanine Green industry, and estimates the future trend of Indocyanine Green market…
A green hotel on a green island
Mitsubishi Electric Hydronics & IT Cooling Systems, through its brand Climaveneta, has recently supplied HVAC units to the new luxury hotel now under construction at Benitses Beach in Corfu, also known as the “Green Island” for its thick vegetation. The complex includes a 5-star hotel, 40 bungalows and furnished villas, with a total capacity of 893 beds. It is the first large hotel in Greece, designed to avoid the use…
Green Information Technology Services Market | #green IT #Green Technology @Adva …
Global Green Information Technology (IT) Services Market: Overview
Green information technology (IT) covers services related to environmentally sustainable computing and IT optimization. The technology aims at minimizing the negative impacts of IT operations by manufacturing, designing, and disposing of servers, computers, and other associated subsystems such as networking systems, communication systems, printers and monitors, and storage devices in an environmentally-friendly manner.
The motive behind deploying green IT practices is to reduce the…

