
Press release
Data Center Piping Market Size to Reach USD 7,430.99 Million by 2033 as AI Rack Density, Liquid Cooling Adoption, and Hyperscale Expansion Redefine Thermal Infrastructure
Data Center Piping Market
Ready to scale in the Data Center Piping Market? Connect with the right partners and unlock new growth opportunities today: https://www.datamintelligence.com/partner-identification-enquiry/data-center-piping-market?kailas
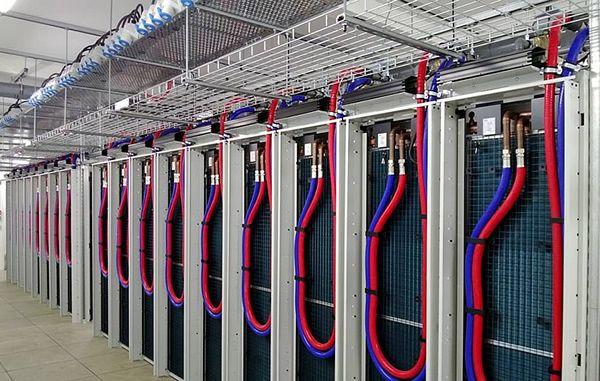
According to DataM Intelligence, the commercial outlook for data center piping is improving because the market is no longer tied only to conventional chilled-water loops. It is increasingly connected to direct-to-chip liquid cooling, immersion cooling, rear-door heat exchange, secondary-fluid distribution, coolant distribution units, and outdoor heat rejection systems. Schneider Electric states that many AI servers with accelerators now generate enough heat to require liquid cooling and are equipped with input and output piping, along with manifolds, CDUs, and outdoor heat rejection. That is a direct signal that piping is becoming a design-critical layer in AI-ready facilities rather than a standard balance-of-plant item.
The demand case is also being reinforced by the pace of infrastructure redesign. Uptime Institute's 2025 survey says average server rack power densities continue to rise, driven by growing adoption of racks in the 10 kW to 30 kW range, while its separate AI density analysis notes that only about 1% of operators reported racks above 100 kW in 2024. That gap is important. It shows that the broader installed base is still moderate in density, but the leading edge of AI deployment is already pushing cooling methods far beyond traditional air-only designs. In this environment, chilled-water systems, direct liquid cooling loops, flexible thermal connections, and corrosion-resistant pipe materials are becoming increasingly important to data center capacity planning.
Market Dynamics
AI workloads are increasing the need for liquid-based thermal transport
The strongest growth driver is the rise of AI workloads that demand higher rack densities and more stable thermal control. Vertiv said in June 2025 that its NVIDIA GB300 NVL72 reference architecture supported densities of up to 142 kW per rack, while in January 2026 it launched Vertiv MegaMod HDX, a modular liquid-cooling solution that can support up to 1.25 MW in a 13-rack standard module and up to 10 MW in a 144-rack extended configuration. Once rack power reaches these levels, piping architecture becomes central to coolant delivery, hydraulic balance, leak prevention, and maintainability.
Cooling efficiency is becoming a board-level cost issue
Cooling is no longer a secondary efficiency topic. It is now one of the main economic variables in AI-ready facilities. Schneider Electric said in January 2026 that liquid cooling can reduce cooling energy consumption by 30% to 60% in many cases, while also lowering operating costs and emissions. That matters because as power demand grows, the cost of moving heat becomes almost as important as the cost of powering compute. According to DataM Intelligence, this is one of the clearest reasons the data center piping market is growing so quickly: efficient liquid movement is becoming a direct contributor to facility economics, not just a mechanical necessity.
Hyperscale and colocation expansion are increasing system complexity
The market is also being supported by the scale of new data center development. The IEA says the United States will account for nearly half of electricity demand growth from data centers between now and 2030, while the United States, China, and Europe together account for around 85% of global data center electricity consumption today. Schneider Electric's 2025 liquid-cooling brochure also states that global data center capacity is expected to triple by 2030 as GPU-intensive workloads expand. This combination is translating into larger and more standardized liquid-cooling deployments, especially in hyperscale and colocation environments where design repeatability and cooling efficiency have direct financial value.
Polymer and corrosion-resistant piping are gaining strategic importance
Material choice is becoming a more important commercial differentiator inside the market. GF Piping Systems stated in March 2026 that direct liquid cooling benefits from liquids' thermal capacity, which is about 3,500 times greater than air, but it also emphasized that coolant purity, corrosion resistance, and hydraulic stability make piping material a strategic design decision. Aquatherm and GF are both positioning polypropylene and polymer-based systems around corrosion-free operation, lower weight, and stable flow in mission-critical cooling environments. This is significant because as liquid cooling scales, the market is shifting from conventional steel-centric utility thinking toward lifecycle-oriented decisions about contamination control, joining methods, flexibility, and serviceability.
Request Executive Sample | Market Intelligence: https://www.datamintelligence.com/download-sample/data-center-piping-market?kailas
Market Disruption
The main disruption in the data center piping market is the shift from air-cooled legacy layouts to hybrid and liquid-dominant cooling architectures. That transition is changing what buyers value. In older facilities, piping was often treated as a conventional MEP component. In AI-ready facilities, it is increasingly judged on leak resistance, cleanliness, corrosion behavior, thermal compatibility, prefabrication speed, and adaptability to future compute generations. Uptime Institute says the industry is facing rising costs, power constraints, and uncertainty in meeting AI demand, while Schneider Electric says many AI servers now require liquid cooling ecosystems built around piping, manifolds, CDUs, and outdoor rejection. In practical terms, the market is moving from commodity piping toward engineered flow infrastructure.
Recent Developments
1. On November 11, 2025, GF Piping Systems launched LiquidCore, a polymer piping solution engineered for direct-to-chip liquid cooling.
2. On December 14, 2025, Motivair by Schneider Electric introduced new corridor-installed CDUs for HPC and AI workloads
3. on January 21, 2026 it introduced a new CDU platform with capacity to scale to 10 MW and beyond, including a 2.5 MW unit.
4. On January 14, 2026, Vertiv launched MegaMod HDX for high-density AI deployments.
5. On February 18, 2026, Schneider Electric opened a Motivair liquid cooling solutions factory in India
6. on March 16, 2026, Vertiv announced its role in NVIDIA's Vera Rubin DSX AI factory reference design. Together, these moves show that liquid-cooling hardware, including the pipework and fluid-distribution layer, is being scaled for mainstream AI infrastructure rather than specialty deployments.
Market Segmentation
Application Segment - Direct-to-chip liquid cooling is becoming the fastest-growth demand center
Among applications, direct-to-chip liquid cooling is emerging as the strongest growth vector because it sits closest to the AI heat source and requires dedicated supply and return piping, manifolds, hoses, and CDU integration. GF's March 2026 technical brief notes that liquid has roughly 3,500 times the thermal capacity of air, while Vertiv's 2025 and 2026 announcements show support for densities reaching 142 kW per rack and infrastructure blocks up to 10 MW. These figures make direct-to-chip cooling the clearest high-growth application for specialized piping, especially in hyperscale AI clusters and retrofit-ready colocation environments.
Material Segment - Plastic and composite pipes are gaining traction in precision-cooling loops
In material terms, plastic and composite piping is gaining more strategic attention because of corrosion resistance, lighter weight, and compatibility with controlled coolant environments. GF and Aquatherm are both actively promoting polymer-based systems for data center cooling, while GF's direct-liquid-cooling brief emphasizes coolant purity and long-term hydraulic stability as critical design parameters. That does not mean stainless steel, carbon steel, and copper disappear. Those materials remain relevant in plant rooms, rigid headers, and certain high-pressure or legacy-compatible applications. But the growth edge is moving toward materials that can help reduce contamination risk and simplify installation in compact AI cooling layouts.
Data Center Type - Hyperscale and colocation are likely to account for the largest share of new demand
By data center type, hyperscale and colocation are positioned to generate the largest share of new piping demand because they are the most likely to deploy standardized liquid-cooling architecture at scale. The IEA expects the United States to account for nearly half of data-center-related electricity demand growth to 2030, and Schneider Electric's 2025 liquid-cooling material says global data center capacity is expected to triple by 2030. These trends strongly favor large operators building repeatable cooling infrastructure across multiple sites, especially where direct liquid cooling and heat rejection systems are being integrated into new AI-ready halls. This is an inference from demand patterns and infrastructure announcements rather than a published segment-share figure.
Regional Analysis
North America
North America remains the benchmark commercial region because the United States is the center of AI-led data center growth. The IEA says the United States will account for nearly half of data center electricity demand growth through 2030, and Schneider Electric's July 2025 grid-readiness analysis said seven of 13 major U.S. grid regions are expected to operate below critical safety margins for most of the 2025-2030 period. That combination is important for the piping market. It means operators are under pressure to build more thermally efficient infrastructure, especially chilled-water, liquid-cooling, and heat-rejection systems that can support higher compute density without proportionally higher cooling waste.
Europe
Europe remains a major region because it is already one of the largest markets for data center electricity demand and because the region has a strong base of engineering-led liquid-cooling suppliers. The IEA says the United States, China, and Europe together account for around 85% of current global data center electricity consumption. Europe is also home to several of the market's visible piping and liquid-cooling infrastructure suppliers, including GF, Aquatherm, and Victaulic's large project base. In commercial terms, Europe's role is strengthened by its mix of hyperscale buildouts, mature colocation ecosystems, and retrofit demand in existing facilities that now need to accommodate higher rack densities.
Asia Pacific
Asia Pacific is becoming more strategically important because data center power demand is rising fast and new liquid-cooling capacity is being localized. The IEA says Southeast Asia's data center electricity demand is expected to more than double by 2030, in part because of Singapore and southern Malaysia. Schneider Electric's new liquid-cooling factory in India and Vertiv's February 2026 AI factory announcement with NxtGen AI also show that supply-chain and deployment activity are moving deeper into the region. According to DataM Intelligence, Asia Pacific is likely to become one of the strongest long-term growth regions for data center piping as AI infrastructure, sovereign compute, and high-density colocation continue to expand.
Buy This Exclusive Report: https://www.datamintelligence.com/buy-now-page?report=data-center-piping-market?kailas
Company Profile
GF Piping Systems
GF is one of the clearest pure-play infrastructure names in this market. Georg Fischer's 2025 annual report says its Flow Solutions businesses generated CHF 3 billion in sales, employed about 13,300 people, and operated in 46 countries. GF has also moved directly into AI cooling infrastructure with LiquidCore, launched in November 2025 as a polymer piping solution for direct-to-chip liquid cooling. Its positioning around coolant purity, corrosion resistance, and modular installation makes it especially relevant in hyperscale and colocation deployments that are shifting toward repeatable liquid-cooling designs.
Parker Hannifin
Parker brings scale and component depth rather than a single dedicated piping system brand. The company reported USD 19.9 billion in fiscal 2025 sales, operates in 44 countries, and employs approximately 58,000 people. Its relevance to the data center piping market comes through quick disconnects, hose assemblies, and liquid-cooling connection systems for servers, supercomputers, and CDUs. Parker's UQD, NSG, CDT, and related liquid-cooling products are positioned around non-spill, interoperable, high-reliability connections for modern data center and server environments, which makes Parker an important enabler in the broader pipe-and-fluid-distribution chain.
Aquatherm
Aquatherm is one of the most visible polypropylene pipe specialists in the market. The company describes itself as the world's leading manufacturer of plastic piping systems made of polypropylene and says its products are installed in more than 70 countries, with a strong North American presence and dedicated data center positioning through aquatherm blue. Its core value proposition in data centers centers on corrosion-free cooling, lower weight, and long-term thermal stability, which makes it particularly relevant in chilled-water and liquid-cooling loops where operators want lower maintenance risk and cleaner fluid paths.
Victaulic
Victaulic remains highly relevant through joining technology, modular pipework, and mission-critical installation capability. The company says it is the global leader in mechanical pipe joining solutions, and its 2022 sustainability report notes nearly 5,000 employees, 55 international facilities, and customer reach in 140 countries. Its data center work includes the IT4Innovations project in the Czech Republic, where it supported data center cooling infrastructure using DN50-DN300 carbon steel piping, BIM coordination, prefabrication, and VDC services. That gives Victaulic a strong position in large, schedule-sensitive cooling installations where speed and reliability of assembly matter as much as pipe material selection.
Analyst View
According to DataM Intelligence, the Data Center Piping Market is entering a high-growth phase because liquid cooling is moving from edge use case to core infrastructure. Pre-insulated, flexible, and rigid piping all remain relevant, but the fastest value creation is likely to come from systems tied to direct-to-chip cooling, high-density chilled-water loops, and modular heat-rejection architecture. Hyperscale and colocation should remain the strongest demand centers, while North America leads in near-term commercialization and Asia Pacific strengthens as a manufacturing and deployment hub. In this market, the winners are unlikely to be the cheapest pipe suppliers. They are more likely to be the companies that can deliver clean flow, high reliability, fast installation, and compatibility with next-generation AI thermal designs.
Contact:
Fabian
DataM Intelligence 4market Research LLP
Ground floor, DSL Abacus IT Park, Industrial Development Area
Uppal, Hyderabad, Telangana 500039
USA: +1 877-441-4866
Email: fabian@datamintelligence.com
About DataM Intelligence
DataM Intelligence is a market research and business intelligence firm delivering decision-ready insights across technology, industrial, healthcare, agriculture, consumer, and energy markets. The company provides premium research reports, custom studies, competitive intelligence, and growth strategy support for organizations making high-value commercial decisions.
This release was published on openPR.
Permanent link to this press release:
Copy
Please set a link in the press area of your homepage to this press release on openPR. openPR disclaims liability for any content contained in this release.
You can edit or delete your press release Data Center Piping Market Size to Reach USD 7,430.99 Million by 2033 as AI Rack Density, Liquid Cooling Adoption, and Hyperscale Expansion Redefine Thermal Infrastructure here
News-ID: 4462766 • Views: …
More Releases from DataM intelligence 4 Market Research LLP
Beyond Battery Limits-UAV Propulsion Moves Toward Longer Endurance and Fuel Flex …
New engine tests and hybrid demonstrations are widening propulsion options for unmanned aircraft, while natural-gas use remains a distinct and early-stage proposition.
UAV propulsion development is expanding beyond battery-only designs as manufacturers and research organizations test gas turbines, hybrid-electric systems and fuel-flexible engines. The commercial opportunity is strongest where aircraft need longer flight time, higher payload capacity or sustained operation between refueling or charging. Recent announcements from India, Japan and the…
Biosimilars Market to Reach US$129.29 Billion by 2035, Driven by Rising Biologic …
The global biosimilars market reached US$34.57 billion in 2025 and is projected to reach US$129.29 billion by 2035, growing at a CAGR of 14.1% during 2026 to 2035. Market growth is supported by the increasing number of patent expiries for high-value biologic drugs, rising healthcare expenditure, and growing demand for affordable alternatives to originator biologics. Increasing adoption across oncology, immunology, ophthalmology, diabetes, and other specialty therapeutic areas is further supporting…
Tandem PV Cell Market to Reach USD 6.18 Billion by 2035, Growing at a CAGR of 41 …
The global tandem PV cell market size was valued at USD 1.27 billion in 2025 and is projected to reach USD 6.18 billion by 2035, growing at a CAGR of 41.24% during 2026 to 2035. The market is supported by increasing demand for high-efficiency solar technologies, growing investments in renewable energy infrastructure, and advancements in perovskite-silicon tandem solar cells. Manufacturers are focusing on improving solar conversion efficiency and developing scalable…
AI Server Market to Reach USD 1.25 Trillion by 2035, Driven by Generative AI, Hy …
The global AI server market size was estimated at USD 172.6 billion in 2025 and is projected to reach approximately USD 1.25 trillion by 2035, growing at a CAGR of 21.9% during 2026to 2035. The market is driven by increasing demand for artificial intelligence (AI) infrastructure, generative AI applications, large language models (LLMs), high-performance computing, and cloud-based services.
Download Free Sample Report PDF: https://www.datamintelligence.com/download-sample/ai-server-market?akash
AI Server Market Recent…
More Releases for Data
Data Catalog Market: Serving Data Consumers
Data Catalog Market size was valued at US$ 801.10 Mn. in 2022 and the total revenue is expected to grow at a CAGR of 23.2% from 2023 to 2029, reaching nearly US$ 3451.16 Mn.
Data Catalog Market Report Scope and Research Methodology
The Data Catalog Market is poised to reach a valuation of US$ 3451.16 million by 2029. A data catalog serves as an organized inventory of an organization's data assets, leveraging…
Big Data Security: Increasing Data Volume and Data Velocity
Big data security is a term used to describe the security of data that is too large or complex to be managed using traditional security methods. Big data security is a growing concern for organizations as the amount of data generated continues to increase. There are a number of challenges associated with securing big data, including the need to store and process data in a secure manner, the need to…
HOW TO TRANSFORM BIG DATA TO SMART DATA USING DATA ENGINEERING?
We are at the cross-roads of a universe that is composed of actors, entities and use-cases; along with the associated data relationships across zillions of business scenarios. Organizations must derive the most out of data, and modern AI platforms can help businesses in this direction. These help ideally turn Big Data into plug-and-play pieces of information that are being widely known as Smart Data.
Specialized components backed up by AI and…
Test Data Management (TDM) Market - test data profiling, test data planning, tes …
The report categorizes the global Test Data Management (TDM) market by top players/brands, region, type, end user, market status, competition landscape, market share, growth rate, future trends, market drivers, opportunities and challenges, sales channels and distributors.
This report studies the global market size of Test Data Management (TDM) in key regions like North America, Europe, Asia Pacific, Central & South America and Middle East & Africa, focuses on the consumption…
Data Prep Market Report 2018: Segmentation by Platform (Self-Service Data Prep, …
Global Data Prep market research report provides company profile for Alteryx, Inc. (U.S.), Informatica (U.S.), International Business Corporation (U.S.), TIBCO Software, Inc. (U.S.), Microsoft Corporation (U.S.), SAS Institute (U.S.), Datawatch Corporation (U.S.), Tableau Software, Inc. (U.S.) and Others.
This market study includes data about consumer perspective, comprehensive analysis, statistics, market share, company performances (Stocks), historical analysis 2012 to 2017, market forecast 2018 to 2025 in terms of volume, revenue, YOY…
Long Term Data Retention Solutions Market - The Increasing Demand For Big Data W …
Data retention is a technique to store the database of the organization for the future. An organization may retain data for several different reasons. One of the reasons is to act in accordance with state and federal regulations, i.e. information that may be considered old or irrelevant for internal use may need to be retained to comply with the laws of a particular jurisdiction or industry. Another reason is to…